
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Water Sink Market Size 2023 | USD 47,225 Million |
| Water Sink Market, CAGR | 2.7% |
| Water Sink Market Size 2032 | USD 58,443.4 Million |
Market Overview
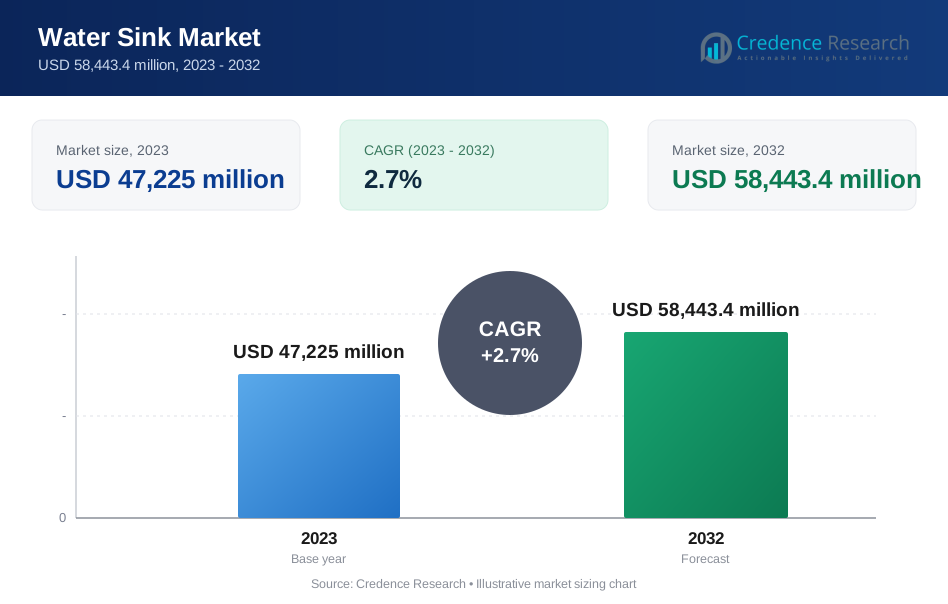
The Global Water Sink Market is projected to grow from USD 47,225 million in 2023 to an estimated USD 58,443.4 million by 2032, with a compound annual growth rate (CAGR) of 2.7% from 2024 to 2032. This growth reflects the rising demand for water sinks across residential, commercial, and industrial segments, driven by increasing urbanization, construction, and renovation activities worldwide.
Key market drivers include the surge in urban housing, coupled with growing consumer preferences for home décor and remodeling projects. Additionally, an increased emphasis on hygiene and sanitation, as well as new construction developments, is contributing to the demand for functional and aesthetically appealing sinks. Industry trends include the adoption of eco-friendly materials, smart sinks with advanced functionalities, and customizable sink designs that cater to evolving consumer tastes.
From a geographical perspective, the market growth is notably robust in regions such as Asia-Pacific due to rapid urbanization and construction activities. North America and Europe remain significant markets, driven by high consumer spending on home improvement projects. Key players in the market include Kohler Co., Blanco GmbH & Co. KG, Franke Kitchen Systems, Elkay Manufacturing Company, Roca Sanitario S.A., Teka Group, and Duravit AG, among others, who compete on innovation, material quality, and design differentiation.
Market Drivers
Rapid Urbanization and Residential Construction Boom
One of the most significant drivers of the Global Water Sink Market is rapid urbanization, which has led to a surge in residential construction worldwide. As more people move to urban areas seeking better living standards, the demand for modern housing, including multi-family apartments and single-family homes, has increased. For instance, according to UN estimates, more than 4 billion people now live in urban areas, with the Global Human Settlement Layer (GHSL) estimating that around 45% of people live in cities and an additional 35% live in towns and semi-dense areas. The urbanization trend is particularly notable in countries like India, where the urban population has almost doubled since 1990.This trend has directly boosted the demand for water sinks, as they are essential fixtures in kitchens and bathrooms. The ongoing trend of smart cities and urban redevelopment projects further strengthens this demand. The preference for high-quality, durable, and aesthetically pleasing sinks has led manufacturers to introduce a wide range of styles, materials, and innovative designs to meet diverse consumer needs, ensuring their homes are both functional and visually appealing.
Growing Home Improvement and Remodeling Activities
The increasing focus on home improvement and remodeling has emerged as a key driver for the water sink market. Consumers are investing more in enhancing the aesthetics and functionality of their living spaces, with kitchens and bathrooms being focal points of such projects. For instance, the median annual spending per household on home improvements was $24,000 in 2023, which is 60% higher than the median spending in 2020 ($15,000). Moreover, U.S. homeowners are expected to spend significant amounts on specific remodeling projects, such as $56,116 - $104,438 on a full kitchen remodel and $4,500 - $9,000 on a bathroom remodel.The popularity of renovation TV shows and social media trends showcasing luxurious and modern home designs have played a role in inspiring homeowners to upgrade their interiors. As sinks play a central role in the functionality and design of these areas, consumers are opting for stylish and high-performance models. This trend has encouraged manufacturers to innovate and offer customizable sinks in terms of shape, material, and features, such as antimicrobial coatings and sound-absorbing technology, to cater to the needs of the remodeling market.
Rising Consumer Awareness Toward Hygiene and Sanitation
The heightened focus on hygiene and sanitation has become a crucial factor driving demand for water sinks, especially in residential, commercial, and healthcare settings. For instance, the World Health Organization estimated that poor WASH (Water, Sanitation & Hygiene) practices were responsible for 829,000 deaths from diarrheal disease in 2016, highlighting the critical importance of hygiene. In India, government initiatives like the "Swachh Bharat Abhiyan" (Clean India Campaign) have raised awareness about sanitation, leading to increased adoption of modern bathroom fixtures.In the wake of global health crises and increasing awareness of the importance of hygiene, there has been a marked increase in the installation of sinks that offer enhanced cleanliness features, including touchless or sensor-operated faucets and sinks with antimicrobial properties. These innovations not only help in reducing the spread of bacteria and viruses but also improve user convenience. Additionally, sinks designed with advanced drainage and cleaning systems are gaining traction as they help minimize maintenance efforts and ensure better sanitation standards, making them an essential component in a variety of settings.
Technological Advancements and Sustainable Solutions
The integration of technology and sustainability in water sink designs is transforming the market landscape. Smart sinks with innovative features, such as automatic temperature control, touchless operations, and water-saving mechanisms, are gaining popularity among environmentally conscious consumers. The increasing adoption of such technologies aligns with growing global concerns about water conservation and sustainable living. Manufacturers are also focusing on producing eco-friendly sinks made from recycled or sustainable materials to reduce their environmental impact. Additionally, sinks with energy-efficient designs, low water consumption rates, and smart water monitoring capabilities have become attractive options for both residential and commercial users, driving further market growth. The shift toward sustainable products also reflects changing consumer behavior, where people are increasingly making conscious choices to support environmentally responsible brands.
Market Trends
Rising Demand for Customization and Aesthetic Appeal**
A key trend in the Global Water Sink Market is the increasing consumer preference for customized and aesthetically pleasing sinks. With modern homeowners placing greater emphasis on the visual appeal of their kitchens and bathrooms, manufacturers have responded by offering a wide range of designs, materials, and finishes. For instance, in the commercial segment, there is an increasing demand for upgraded sink versions, with specific types like top-mount, undermount, and wall-mount water sinks seeing growing popularity across hotels, resorts, and various commercial establishments.Consumers are increasingly seeking sinks that reflect their personal style and complement their interiors. This trend has led to the availability of sinks made from unconventional materials such as quartz, copper, and granite, alongside traditional stainless steel and ceramic models. Additionally, there is a growing demand for uniquely designed sinks, including under-mount, vessel, and farmhouse sinks, which can enhance the overall aesthetic of a space. Customization options, such as choosing sink size, shape, color, and additional features, allow homeowners to create a look that aligns with their preferences while ensuring optimal functionality.
Adoption of Smart and Sustainable Technologies**
The integration of smart and sustainable technologies in water sink designs is gaining traction across the market. Smart sinks equipped with touchless faucets, temperature control features, and motion sensors have become increasingly popular due to their convenience, water-saving capabilities, and ability to improve hygiene. For instance, the U.S. Environmental Protection Agency (EPA) reports that smart water-saving systems integrated into multifunction sinks can reduce water usage by up to 20%, demonstrating the tangible environmental benefits of these technological innovations. Additionally, touchless faucets and motion sensors are now enabling users to minimize surface contact, with smart sink features offering customizable water flow and temperature controls.These features are particularly appealing in light of growing health and sanitation concerns. In addition, sustainability is a key focus, with consumers and manufacturers alike prioritizing eco-friendly materials and water-efficient designs. Sinks that reduce water consumption, minimize maintenance, and feature recyclable materials are now in high demand. This trend aligns with the broader global movement toward sustainability, as consumers seek to minimize their environmental footprint. As a result, manufacturers are introducing energy-efficient designs, adopting greener production processes, and exploring innovative technologies that promote water conservation, thereby enhancing both product functionality and eco-credentials.
Market Restraints and Challenges
High Competition and Price Sensitivity
One of the primary challenges facing the Global Water Sink Market is the intense competition among manufacturers, which leads to price sensitivity. The market comprises a wide range of players, from large multinational corporations to small regional producers. This competitive landscape often results in price wars, which can compress profit margins, particularly for smaller players who may struggle to maintain economies of scale. Moreover, the high availability of low-cost alternatives, including imported products, poses a challenge for premium brands trying to maintain market share without compromising on quality. Price sensitivity among end-users, especially in cost-conscious markets, further complicates matters, as consumers often prioritize cost over quality, design, or advanced features. As a result, manufacturers must strike a balance between pricing strategies and maintaining product innovation to stay competitive.
Fluctuating Raw Material Costs and Supply Chain Disruptions
The volatility of raw material costs represents a significant restraint for the water sink market. Water sinks are commonly manufactured using materials such as stainless steel, ceramic, stone, and composite materials, which are subject to price fluctuations based on market conditions, trade policies, and supply-demand dynamics. Any increase in raw material costs can lead to higher production expenses, ultimately impacting product pricing and profit margins. Additionally, global supply chain disruptions, driven by geopolitical tensions, trade restrictions, or unexpected events such as pandemics, pose a serious challenge. Delays in the availability of key materials and components can hinder production timelines and lead to stock shortages, affecting manufacturers' ability to meet market demand efficiently. The combined impact of raw material volatility and supply chain uncertainties makes it critical for companies to adopt agile sourcing strategies and robust inventory management practices to mitigate risks and maintain consistent supply levels.
Market Segmentation Analysis
By Type
The Global Water Sink Market is segmented by type into fixed and portable water sinks. The fixed water sink segment holds the majority share, driven by its widespread use in residential, commercial, and industrial settings. Fixed sinks are known for their durability and integration within kitchen and bathroom designs, making them a popular choice for permanent installations. They offer various customization options, including different shapes, sizes, and materials, which cater to diverse consumer needs. On the other hand, the portable water sink segment is experiencing increasing demand, particularly in outdoor, healthcare, and commercial applications where mobility and flexibility are essential. Portable sinks, often equipped with built-in water reservoirs and waste disposal systems, are ideal for temporary setups and locations with limited access to plumbing. As hygiene awareness grows, portable sinks are finding greater utility in events, construction sites, and food service applications.
By Installation Type
The market is further segmented by installation type, encompassing drop-in, under mount, workstation sinks, and others, such as bar sinks. Drop-in sinks are among the most widely used due to their ease of installation and compatibility with different countertop materials. Their affordability and versatility make them a favored choice in residential and commercial applications, particularly in areas where quick replacement or retrofitting is necessary. Under mount sinks offer a sleek, modern appearance, seamlessly integrating with countertops to provide a clean, continuous look. They are particularly popular in luxury and high-end kitchens and bathrooms, as they enhance the overall aesthetic appeal and simplify countertop cleaning. Workstation sinks represent a growing market segment, driven by the need for multifunctional and space-efficient solutions. These sinks often come with integrated accessories such as cutting boards, colanders, drying racks, and more, transforming a traditional sink area into a highly functional workspace. The rising popularity of open-concept kitchens and the trend toward maximizing efficiency have fueled demand for this segment. Other sinks, including bar sinks, fulfill niche requirements and cater to specific settings such as entertainment areas, bars, and outdoor kitchens, offering smaller footprints with practical functionality.
Segments
Based on Type
- Fixed Water Sink
- Portable Water Sink
Based on Installation Type
- Drop-in
- Under Mount
- Workstation Sinks
- Others (Bar Sinks etc.)
Based on Material
- Stainless Steel
- Granite/Quartz
- Cast Iron Sink
- Fireclay Sink
- Others (Copper Sinks etc.)
Based on Configuration
- Single Bowl sink
- Double Bowl sink
Based on Application
- Residential
- Commercial
Based on Distribution Channel
- Direct Sales
- Indirect Sales
Based on Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- MEA
- Saudi Arabia
- UAE
- South Africa
- Rest of MEA
Regional Analysis
North America (30%):
North America holds a significant share of the global market, accounting for approximately 30% of the total market share. The demand for water sinks in this region is driven by a robust housing market, high levels of remodeling activities, and consumer interest in premium home improvement products. The presence of established manufacturers, coupled with the growing popularity of multifunctional and smart sinks, continues to boost the market. In addition, there is a strong emphasis on eco-friendly and sustainable sinks, reflecting broader trends toward environmentally conscious consumption.
Europe (25%):
Europe represents around 25% of the market share, with steady demand attributed to the region’s mature construction and renovation sectors. European consumers prioritize high-quality materials and advanced designs, leading to an increase in the adoption of under-mount and workstation sinks. The market is also driven by stringent regulations encouraging sustainable construction practices, which has prompted manufacturers to focus on eco-friendly and energy-efficient sink solutions. Key countries such as Germany, France, and the United Kingdom play a crucial role in driving regional market growth.
Key players
- Acorn Engineering Company, Inc.
- Carysil
- CERA
- Duravit AG
- Elkay Manufacturing Company
- Franke Group
- GROHE Pacific Pte Ltd.
- Hindware Appliances
- Kohler Co.
- Kraus Plumbing LLC
- LEFTON
- LIXIL Corporation
- Pelham & White Corp.
- Ruvati
- Sinkology
Competitive Analysis
The Global Water Sink Market is highly competitive, with key players striving to differentiate themselves through innovation, quality, and customer-centric designs. Companies such as Kohler Co., Elkay Manufacturing, and Franke Group lead the market, offering a comprehensive range of high-quality sinks that cater to residential and commercial needs. Innovation in materials, design aesthetics, and smart sink features has become a major competitive edge. Meanwhile, emerging brands like Ruvati and Sinkology focus on niche segments, including customizable and budget-friendly offerings. Global players such as LIXIL Corporation and Duravit AG leverage strong distribution networks and brand reputation to maintain market dominance. Price competition, sustainable product development, and technological advancements remain critical for companies to capture market share and cater to evolving consumer preferences.
Recent Developments
- In **July 2023**, Duravit AG announced its plans to establish a fully automated plant in Matane, Quebec, Canada. This will be Duravit’s first production site in North America, focusing on high-end bathroom ceramics and aiming to achieve net-zero emissions by 2045.
- On **November 11, 2024**, Franke Group successfully completed the acquisition of WESCO Group, a premium supplier of extractor hoods and ventilation systems in Switzerland and Germany. This acquisition strengthens Franke’s portfolio in home solutions.
- In **December 2023**, LIXIL launched the GROHE SPA collection in the Asia-Pacific region, offering personalized luxury bathroom experiences with multisensory shower systems and customizable faucet designs.
- In **October 2024**, Hindware rebranded its consumer appliances business under the name "Hindware Smart Appliances," aligning all products under one brand to enhance market presence and consumer connection.
- In **November 2023**, Kohler Co. announced the establishment of its Energy group as an independent entity through a partnership with Platinum Equity, with the transaction expected to close in Q1 2024.
Market Concentration and Characteristics
The Global Water Sink Market exhibits a moderate to high level of market concentration, characterized by the presence of a mix of established multinational corporations and regional players. Dominant companies such as Kohler Co., Franke Group, and Elkay Manufacturing hold a significant market share, driven by their strong brand presence, innovation capabilities, and extensive distribution networks. However, the market also features a notable segment of smaller and emerging players, particularly in niche areas such as customizable and eco-friendly sinks. The market is distinguished by a focus on product innovation, sustainable materials, and technologically advanced features, including smart and multifunctional sinks. Intense competition and price sensitivity underscore the market's dynamics, while consumer demand for aesthetics, durability, and efficient water management continue to shape product development and industry growth.
Report Coverage
The research report offers an in-depth analysis based on Type, Installation Type, Material, Configuration, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see sustained demand for customized sinks as consumers prioritize unique designs and features that match their preferences and interior aesthetics.
- Smart sinks equipped with touchless controls, automated water regulation, and temperature management will continue to gain traction, enhancing user convenience and hygiene.
- Eco-conscious consumers will drive the demand for sinks made from sustainable and recyclable materials, encouraging manufacturers to adopt greener production processes.
- Rapid urbanization and rising disposable incomes in regions such as Asia-Pacific and Latin America will offer significant growth opportunities for market players.
- Advanced sink designs with multifunctional capabilities, such as built-in accessories and water-saving features, will drive market differentiation and attract diverse consumer segments.
- Companies will invest more in research and development to introduce innovative designs, materials, and technologies that address changing consumer preferences and market demands.
- The demand for under-mount and workstation sinks will grow as consumers seek sleek designs and space-efficient solutions that enhance kitchen and bathroom functionality.
- Artificial Intelligence (AI) and Internet of Things (IoT) integration will lead to smart water sink solutions capable of monitoring water usage and providing real-time data for efficient water management.
- Increasing awareness of hygiene will spur demand for sinks with antimicrobial coatings, touchless features, and advanced drainage systems, especially in healthcare and public settings.
- Strategic mergers, acquisitions, and partnerships will characterize the market as key players aim to strengthen their market positions, expand product portfolios, and reach new geographic regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Global Water Sink Market in 2023 and 2032, and what is the expected CAGR?
What are the main factors driving the growth of the Global Water Sink Market?
Which regions show the highest growth potential in the water sink market?
How is sustainability impacting the water sink market?
What role do technological advancements play in the water sink market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Water Sink Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Water Sink Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 47,225 million → 2032: USD 58,443.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Water Sink Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Water Sink Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Water Sink Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Water Sink Market Drivers
- 3.3 Water Sink Market Restraints & Challenges
- 3.4 Water Sink Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Water Sink Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Water Sink Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Water Sink category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Water Sink Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Water Sink Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Water Sink market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Water Sink Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Water Sink Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Water Sink Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Water Sink (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Water Sink Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Water Sink Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Water Sink Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Water Sink Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Water Sink Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Water Sink Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Water Sink Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Water Sink Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Water Sink Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
