
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
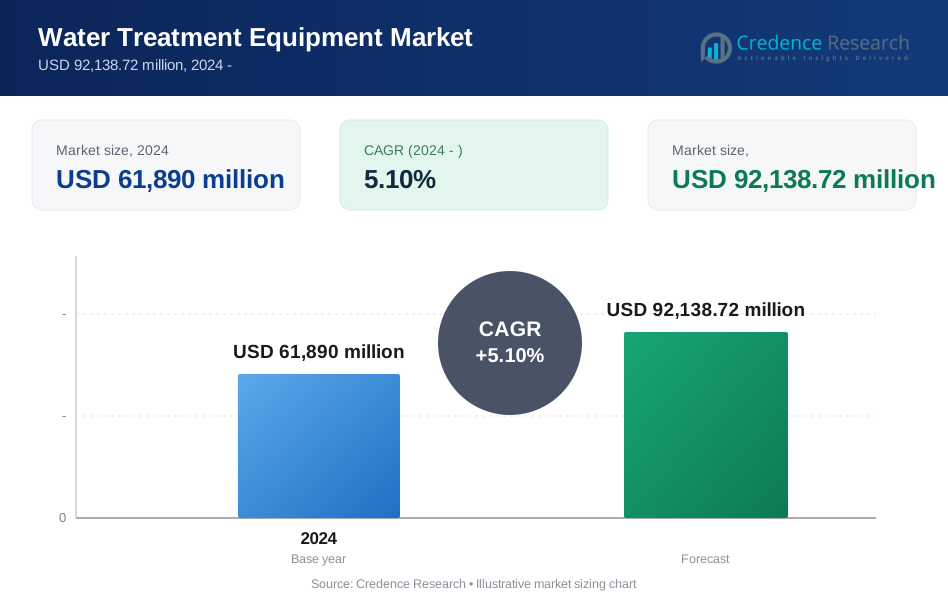
| Water Treatment Equipment Market Size 2024 | USD 61,890 Million |
| Water Treatment Equipment Market, CAGR | 5.1% |
| Water Treatment Equipment Market Size 2032 | USD 92,138.72 Million |
Market Overview:
The global Water Treatment Equipment Market is projected to grow from USD 61,890 million in 2024 to USD 92,138.72 million by 2032, at a compound annual growth rate (CAGR) of 5.1%. Water treatment equipment includes a range of technologies, such as filtration, desalination, disinfection, and membrane processing systems, used to purify water for residential, industrial, and municipal use. Growing concerns over water scarcity, pollution, and the demand for clean water in rapidly urbanizing regions drive market expansion. Additionally, increased industrial activities and rising population densities contribute to higher water treatment requirements, bolstering the adoption of advanced treatment technologies worldwide.
Key drivers of market growth include stringent environmental regulations, increasing awareness about waterborne diseases, and technological advancements in water purification. Government regulations, such as those enforced by the U.S. Environmental Protection Agency (EPA) and European Union directives, mandate strict water quality standards across industrial and municipal sectors. Moreover, the rise in water pollution from industrial waste and urban runoff has raised public health concerns, prompting investments in effective treatment solutions. Technological advancements, such as the development of energy-efficient desalination and membrane filtration systems, enhance the capability and cost-effectiveness of water treatment equipment, making these solutions more accessible across sectors.
Regionally, North America holds a substantial share of the water treatment equipment market due to established regulatory standards, high public awareness, and significant investments in water infrastructure across the U.S. and Canada. Europe follows closely, driven by strict water quality regulations and sustainability initiatives across countries like Germany, France, and the UK. The Asia-Pacific region is expected to witness the fastest growth, driven by rising urbanization, industrialization, and population growth in countries like China, India, and Japan. Government initiatives aimed at improving water access and quality, especially in developing regions, further support market expansion in Asia-Pacific.
Market Drivers:
Stringent Environmental Regulations:
Increasingly strict environmental regulations are a primary driver in the water treatment equipment market, as governments worldwide enforce high standards for water quality. Regulatory bodies, such as the U.S. Environmental Protection Agency (EPA) and the European Union, mandate compliance with water discharge and treatment standards, particularly in industrial sectors. For instance, the EPA’s Clean Water Act requires industries to reduce pollutants in discharged water, motivating companies to adopt advanced water treatment systems. Similarly, the European Water Framework Directive emphasizes reducing water pollution, pushing industries to adopt compliant treatment equipment.
Rising Concerns over Waterborne Diseases:
Public health concerns related to waterborne diseases are another major factor encouraging investment in water treatment solutions. According to the World Health Organization (WHO), unsafe drinking water causes over 485,000 diarrheal deaths annually. This alarming statistic has driven governments and private organizations to prioritize clean water initiatives. For example, the U.S. Centers for Disease Control and Prevention (CDC) collaborates with local governments to monitor waterborne pathogens, promoting investments in filtration and disinfection technologies. This growing emphasis on public health has led municipalities to invest in reliable water treatment equipment for safer drinking water.
Increasing Industrial Activities and Urbanization:
Rapid industrialization and urbanization have escalated water pollution, creating an urgent need for efficient treatment equipment to manage contaminants in wastewater. In heavily industrialized regions, sectors such as manufacturing, mining, and agriculture contribute significantly to water pollution. For instance, the United Nations reports that untreated industrial wastewater continues to pollute freshwater supplies globally. As a response, countries like China have introduced policies requiring industries to install advanced treatment systems. These initiatives underscore the necessity for advanced water treatment solutions in managing industrial waste.
Technological Advancements in Water Treatment:
Technological advancements in water treatment equipment, such as the development of energy-efficient membrane filtration and desalination systems, further fuel market growth. Innovations like reverse osmosis and ultraviolet (UV) disinfection offer highly effective purification methods that are both environmentally friendly and cost-efficient. Companies like Xylem Inc. have introduced advanced desalination technologies that reduce energy consumption while providing high-quality treated water. Such advancements not only enhance treatment efficiency but also lower operational costs, making these systems more accessible to a broader range of sectors.
Market Trends:
Rise of Smart Water Treatment Solutions:
A notable trend in the water treatment equipment market is the increasing adoption of smart water treatment solutions, powered by Internet of Things (IoT) technology. IoT sensors enable real-time monitoring of water quality parameters, allowing for predictive maintenance and efficient system management. For example, Veolia and SUEZ have integrated IoT into their water treatment operations, enabling continuous data collection and analysis. This advancement helps companies optimize water usage, reduce waste, and address potential system issues before they escalate, which is especially valuable in municipal and industrial applications.
Growing Focus on Decentralized Water Treatment:
Decentralized water treatment systems are gaining popularity, particularly in rural and remote areas where centralized systems may be costly or impractical. These systems allow for localized water treatment, reducing the need for extensive distribution networks. For instance, Fluence Corporation has developed modular water treatment solutions that provide flexible, on-site treatment for small communities and industries. Government agencies in countries like India and Kenya are increasingly supporting decentralized systems to expand access to clean water in underserved areas, aligning with global goals for universal water access.
Increased Demand for Advanced Filtration Technologies:
Advancements in filtration technologies, such as membrane filtration and reverse osmosis, are reshaping the water treatment landscape. These methods offer high efficiency and reliability in removing contaminants, making them suitable for applications ranging from municipal water systems to industrial wastewater treatment. For example, companies like Dow Water & Process Solutions have introduced ultra-filtration membranes that are effective against even the smallest contaminants. The U.S. Environmental Protection Agency (EPA) promotes these technologies to ensure compliance with stringent water quality standards, driving their adoption in various sectors.
Emphasis on Energy-Efficient and Sustainable Solutions:
As environmental sustainability becomes a priority, energy-efficient water treatment systems are in high demand. Solutions that use renewable energy sources, such as solar-powered desalination plants, are being explored in regions with high energy costs or limited grid access. Companies like Xylem and Siemens are leading the way by developing energy-efficient water treatment equipment that reduces carbon emissions and operational costs. Government initiatives, such as the European Union’s Green Deal, support these efforts, incentivizing companies to adopt sustainable practices in water treatment and reduce environmental impact.
Market Challenges Analysis:
High Initial Costs and Maintenance Requirements:
A significant challenge in the water treatment equipment market is the high initial cost and ongoing maintenance of advanced treatment systems. Technologies such as reverse osmosis, ultrafiltration, and UV disinfection systems require substantial investment in equipment and infrastructure. For small to mid-sized municipalities and industries, these costs can be prohibitive, limiting the adoption of state-of-the-art water treatment solutions. The U.S. Environmental Protection Agency (EPA) highlights that smaller utilities often struggle to secure funding for advanced treatment technologies, particularly in rural and underserved communities.
Complexity of Regulatory Compliance:
Ensuring compliance with diverse and stringent regulations is another major challenge for the water treatment equipment market. Regulations vary significantly across regions, with authorities like the EPA in the U.S. and the European Union enforcing high standards for water quality and discharge. These regulations mandate rigorous testing and treatment protocols that require sophisticated equipment and regular monitoring, increasing operational complexity. Adapting to evolving standards often necessitates expensive upgrades, which can be challenging for smaller facilities with limited budgets. The European Union’s Water Framework Directive, for example, imposes strict standards on pollutant levels, compelling companies to adopt advanced but costly equipment to maintain compliance.
Limited Access to Skilled Labor and Technical Expertise:
Operating and maintaining advanced water treatment equipment requires specialized skills, yet there is a shortage of professionals trained in managing complex systems. The U.S. Bureau of Labor Statistics indicates that demand for water and wastewater treatment operators continues to rise, but many regions face a shortage of qualified personnel. Limited access to skilled operators affects the effectiveness of water treatment processes, as underqualified staff may struggle with complex installations, maintenance routines, and troubleshooting. This shortage can limit the adoption and proper utilization of advanced treatment systems, particularly in developing countries or rural areas where access to training resources is limited.
Market Segmentation Analysis:
By Type
The water treatment equipment market is segmented by type into filtration, disinfection, desalination, and membrane processes. Filtration systems hold a significant market share due to their broad application across municipal, residential, and industrial water treatment. Disinfection technologies, including ultraviolet (UV) and chemical-based systems, are increasingly in demand for drinking water safety. Desalination equipment, essential for treating seawater, is gaining traction in regions facing freshwater scarcity, particularly in the Middle East and coastal cities. Membrane processes like ultrafiltration and reverse osmosis offer high-precision water purification, making them popular in both industrial and municipal settings.
By Technology
By technology, the market includes chemical, physical, and biological treatment methods. Chemical treatments, using agents like chlorine and coagulants, are widely used for effective disinfection and contaminant removal. Physical methods, such as sedimentation and filtration, are preferred for primary treatment stages. Biological treatment technologies, including activated sludge and biofilm reactors, are essential in wastewater treatment for organic waste breakdown. The push for sustainable practices drives demand for energy-efficient and eco-friendly biological and physical methods.
By End User
End users in the water treatment equipment market include residential, industrial, and municipal sectors. Municipalities form the largest segment due to the need for large-scale water purification and wastewater management to meet public health standards. The industrial sector, particularly in manufacturing, pharmaceuticals, and food processing, also contributes significantly, as these industries require strict water quality control. The residential segment is growing, driven by increasing awareness of waterborne health risks, fueling demand for home filtration and purification systems.
Segmentations:
By Product type
- Sedimentation tanks
- Filtration systems
- Disinfection equipment
- Softening equipment
- Membrane systems
- Others
By Technology
- Reverse osmosis
- Microfiltration
- Clarifier
- Distillation
- Ion exchange
- Others
By End-Use
- Residential
- Agriculture
- Chemical manufacturing
- Food processing
- Construction
- Pharmaceutical production
- Others
By Distribution channel
- Direct
- Indirect
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the water treatment equipment market, accounting for approximately 35% of global revenue. This dominance is largely driven by stringent water quality standards and established regulatory frameworks across the United States and Canada. The U.S. Environmental Protection Agency (EPA) enforces strict guidelines under the Safe Drinking Water Act, pushing industries and municipalities to adopt advanced treatment solutions. High consumer awareness and government funding for water infrastructure further support market growth. Canada’s proactive approach toward clean water initiatives, particularly in addressing indigenous and rural water quality challenges, also contributes to regional demand. Industrial activities, including oil and gas, food processing, and manufacturing, heavily invest in water treatment technologies to comply with environmental regulations.
Europe
Europe follows closely, with around 30% of the global market share, driven by stringent environmental policies and sustainability initiatives. The European Union’s Water Framework Directive mandates strict water treatment and discharge standards, which compel industries to invest in advanced treatment equipment. Countries like Germany, France, and the United Kingdom lead in adopting these technologies due to their strong industrial sectors and commitment to environmental conservation. In Germany, the focus on industrial wastewater treatment and sustainable solutions fosters demand for energy-efficient equipment. France has been investing in advanced desalination technologies, particularly for its coastal regions, while the UK prioritizes water quality improvements across urban and rural areas, supporting market growth.
Asia-Pacific
The Asia-Pacific region is anticipated to experience the fastest growth, capturing approximately 25% of the global market share. Rapid industrialization, urbanization, and population growth in countries like China, India, and Japan drive demand for water treatment solutions. In China, government initiatives such as the “Action Plan for Prevention and Control of Water Pollution” mandate stringent water quality controls, fueling the need for advanced water treatment equipment across sectors. Japan, known for its technological advancements, focuses on innovative and energy-efficient water treatment solutions to address water scarcity. India’s push for better water infrastructure through projects like the Clean Ganga Mission and Smart Cities Mission further stimulates demand for municipal and industrial water treatment technologies.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively hold approximately 10% of the global market. In Latin America, countries like Brazil and Mexico are investing in water treatment equipment due to increasing urbanization and industrial growth, with a particular focus on wastewater management. The Middle East, led by countries such as Saudi Arabia and the UAE, heavily invests in desalination technologies to ensure a sustainable water supply, as fresh water is scarce in the region. In Africa, the market is in a growth phase, with several international aid programs and government initiatives focusing on clean water access and improved sanitation, especially in areas with limited infrastructure.
Key Player Analysis:
- Veolia Environment S.A.
- SUEZ Water Technologies & Solutions
- Xylem Inc.
- Pentair Plc
- Ecolab Inc.
- General Electric Company (GE Water)
- 3M Company
- Danaher Corporation
- DuPont de Nemours, Inc.
- Thermo Fisher Scientific Inc.
Competitive Analysis:
The water treatment equipment market is highly competitive, with established players like Veolia Environment, SUEZ, and Xylem Inc. leading due to their comprehensive service portfolios and strong global presence. These companies maintain a competitive advantage by focusing on advanced treatment technologies, including filtration, desalination, and membrane processes, which address complex water quality issues across industrial, municipal, and residential applications. Emerging companies, such as Danaher Corporation and Ecolab, enhance market competition by offering specialized solutions with an emphasis on sustainability and energy efficiency. The market also sees intensified competition from players like DuPont and Thermo Fisher Scientific, which are investing in R&D to improve cost-efficiency and performance. These firms leverage technological advancements and strategic partnerships to expand their offerings and meet strict regulatory requirements, making the market a dynamic space focused on sustainable, high-performance solutions for water quality management.
Recent Developments:
- Xylem Inc. completed its acquisition of Evoqua Water Technologies in 2023, expanding its portfolio in wastewater treatment solutions. This acquisition strengthens Xylem's capabilities in serving industrial and municipal sectors with a focus on advanced filtration and water reuse technologies, addressing the increasing need for sustainable water management.
- Veolia introduced a Climate Solidarity Initiative in 2023, focusing on reducing greenhouse gas emissions and advancing water conservation. As part of this initiative, Veolia has invested in optimizing water treatment processes to lower environmental impact, aligning with the company’s goal to lead in ecological transformation through sustainable water management solutions.
- Ecolab partnered with WaterEquity in 2024, contributing to a $100 million fund aimed at improving water and sanitation infrastructure in underserved regions. This initiative supports climate-resilient water projects across Africa, Asia, and Latin America, showcasing Ecolab’s commitment to expanding access to clean water while advancing sustainable development goals.
- SUEZ has enhanced its smart water treatment offerings by incorporating IoT and real-time monitoring capabilities into its solutions as of 2023. This upgrade allows for more efficient water resource management by enabling predictive maintenance and improved data analytics, meeting the demands for digitalized water solutions in urban and industrial settings.
Market Concentration & Characteristics:
The water treatment equipment market is moderately concentrated, with major players such as Veolia Environment, SUEZ, and Xylem Inc. leading due to their extensive portfolios and strong global reach. These established companies leverage advanced technologies, including smart water management solutions and sustainable practices, to maintain competitive advantages and align with evolving environmental regulations. High entry barriers, such as substantial capital investment in R&D and the necessity of compliance with strict water quality standards, limit new entrants. Companies like Ecolab and Pentair further contribute to market diversity by offering specialized solutions for industrial and municipal water treatment. The market’s defining characteristics include a strong emphasis on sustainable practices, energy efficiency, and digitalization, as providers focus on smart technologies and IoT integration to enhance monitoring and operational efficiency. As a result, the competitive landscape continues to evolve with increasing attention on eco-friendly solutions and strategic partnerships that expand technological capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Product type, Technology, End-Use, and Distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for advanced water treatment solutions will rise due to increasing regulations on water quality and wastewater discharge, especially in industrial and municipal sectors.
- Smart water management and IoT-integrated equipment will gain traction, enabling real-time monitoring and predictive maintenance to optimize resource efficiency.
- Energy-efficient water treatment technologies will grow in popularity as companies prioritize sustainable operations, particularly those that lower carbon emissions.
- Decentralized water treatment systems will expand, meeting the needs of rural and remote areas where centralized systems are not feasible.
- Desalination technologies, especially those powered by renewable energy, will see increased adoption in regions facing water scarcity, such as the Middle East and parts of Africa.
- Advanced filtration methods, including reverse osmosis and membrane filtration, will remain crucial in meeting stringent purification standards for drinking and industrial water.
- Public and private investments in water infrastructure will continue to grow globally, particularly in regions where aging infrastructure requires upgrades.
- Partnerships between water treatment companies and governments will strengthen, aiming to address water access challenges in developing regions.
- Digital solutions and data analytics will play a larger role in water treatment, enhancing operational insights and supporting compliance with regulatory standards.
- Consumer awareness of waterborne health risks will boost demand for residential water filtration solutions, driving growth in the residential segment.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Water Treatment Equipment Market?
What factors are driving the growth of the Water Treatment Equipment Market?
What are some challenges faced by the Water Treatment Equipment Market?
Who are the major players in the Water Treatment Equipment Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Water Treatment Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Water Treatment Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 61,890 million → forecast year: USD 92,138.72 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Water Treatment Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Water Treatment Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Water Treatment Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Water Treatment Equipment Market Drivers
- 3.3 Water Treatment Equipment Market Restraints & Challenges
- 3.4 Water Treatment Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Water Treatment Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Water Treatment Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Water Treatment Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Water Treatment Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Water Treatment Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Water Treatment Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Water Treatment Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Water Treatment Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Water Treatment Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Water Treatment Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Water Treatment Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Water Treatment Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Water Treatment Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Water Treatment Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Water Treatment Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Water Treatment Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Water Treatment Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Water Treatment Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Water Treatment Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
