
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
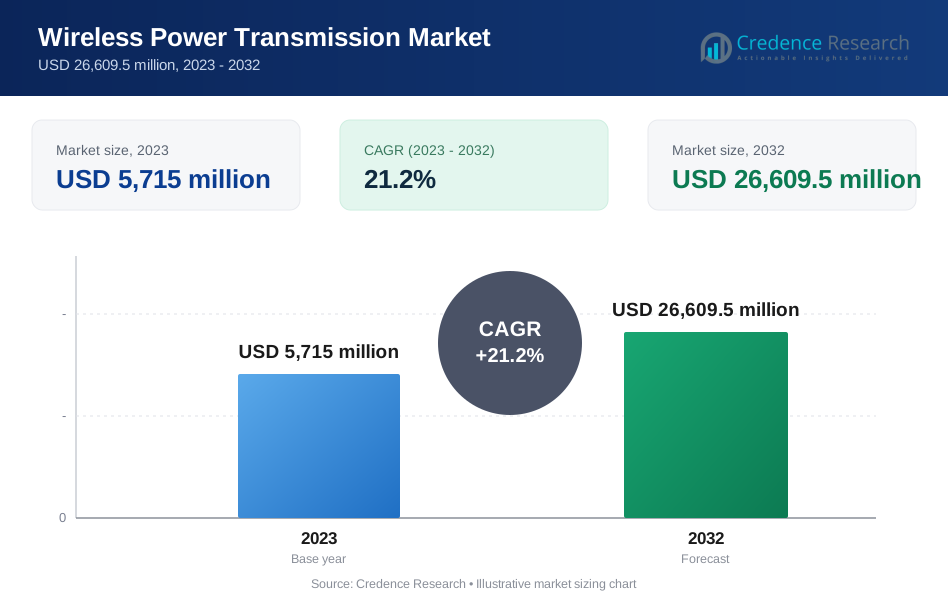
| Wireless Power Transmission Market Size 2023 | USD 5,715 Million |
| Wireless Power Transmission Market, CAGR | 21.2% |
| Wireless Power Transmission Market Size 2032 | USD 26,609.5 Million |
Market Overview
The Global Wireless Power Transmission Market is projected to grow from USD 5,715 million in 2023 to an estimated USD 26,609.5 million by 2032, registering a robust compound annual growth rate (CAGR) of 21.2% from 2024 to 2032. This growth trajectory is driven by increasing demand for efficient energy transfer and advancements in wireless technologies.
Key drivers for the market include the rising need for convenient and cable-free charging solutions, particularly in the consumer electronics segment, where the popularity of smartphones, wearable devices, and electric vehicles continues to surge. Technological advancements such as resonant inductive coupling, radiofrequency, and capacitive coupling have significantly improved power transmission efficiency and range, boosting market penetration. Trends like the integration of wireless power systems into smart home devices, medical implants, and electric vehicles further solidify the market's appeal.
Geographically, the Asia-Pacific region is expected to hold the largest share due to strong consumer electronics production, rapid urbanization, and the presence of major market players. North America and Europe are also key regions driven by robust technological adoption and regulatory support for wireless charging infrastructure. Prominent market players include companies such as WiTricity Corporation, Qualcomm Incorporated, Energous Corporation, Samsung Electronics Co., Ltd., and Texas Instruments, Inc., who continue to drive innovation and market competitiveness.
Market Drivers
Increasing Demand for Consumer Electronics and Portable Devices
The continuous surge in consumer electronics, including smartphones, tablets, laptops, and wearable devices, has created a strong demand for efficient and convenient power solutions. As users increasingly rely on these devices for daily activities, the need for a hassle-free charging experience has intensified. Wireless power transmission technology, offering a cable-free charging solution, addresses this demand and improves user convenience. This trend is further bolstered by the integration of wireless charging in flagship devices from leading brands, which has normalized its use and increased consumer awareness. As a result, wireless power solutions for portable devices continue to be a primary growth driver for the market. Moreover, technological advancements, such as magnetic resonance and radiofrequency-based charging solutions, are enhancing charging speed and distance, making wireless charging more viable for a broader range of products. For instance, in 2023, over 2.5 billion smartphones were in use globally, with a significant portion featuring wireless charging capabilities.
Adoption in Electric Vehicles (EVs) and Automotive Sector
The automotive industry, especially electric vehicles (EVs), has been a significant driver for the adoption of wireless power transmission. As the demand for EVs increases globally due to climate concerns and governmental policies promoting clean energy, the need for convenient, efficient, and safe charging methods grows. Wireless EV charging eliminates the need for cumbersome cables and enhances convenience for consumers. It also allows for new applications such as dynamic wireless charging, which can charge vehicles while they are in motion. Leading automotive companies and component suppliers are actively investing in R&D for wireless charging technologies, creating a strong growth trajectory for this application. Additionally, governments across various regions have recognized the importance of wireless power systems in supporting electric mobility and are supporting their development through investments, incentives, and regulatory measures. For instance, the number of electric vehicles on roads worldwide surpassed 10 million units in 2023, driving demand for wireless charging infrastructure.
Growth in the Healthcare Sector with Medical Device Integration
The healthcare sector has rapidly adopted wireless power transmission technologies due to the increasing use of portable medical devices, implantable devices, and wireless surgical instruments. For example, wirelessly powered implantable devices such as pacemakers, insulin pumps, and neurostimulators reduce the risk of infections associated with traditional wired devices and offer improved patient comfort. Moreover, medical equipment that can wirelessly charge or function without physical connections significantly enhances safety, reduces maintenance, and improves operational efficiency within hospitals and clinical settings. As healthcare systems seek to modernize and integrate advanced technologies, wireless power solutions are increasingly being embedded in medical devices to enable continuous monitoring and treatment, enhancing patient care and outcomes. For instance, over 1 million patients worldwide were using implantable medical devices with wireless charging capabilities in 2023, showcasing the technology's growing adoption in critical medical applications.
Advancements in Wireless Charging Technologies and Regulatory Support
Technological advancements in wireless power transmission methods, such as resonant inductive coupling, radiofrequency, and capacitive coupling, have significantly improved the efficiency, distance, and reliability of wireless charging systems. These innovations have made it possible to support a wider range of applications and have paved the way for more extensive adoption in both consumer and industrial sectors. Additionally, the rise of the Internet of Things (IoT) and the growing trend of smart homes and cities have driven the demand for interoperable wireless charging systems. Regulatory bodies across different regions are also promoting wireless power technologies through standardization initiatives, which help streamline the adoption process and ensure compatibility across devices and manufacturers. Supportive policies and standards encourage industry collaboration and foster consumer confidence, providing a conducive environment for market growth.
Market Trends
Integration of Wireless Charging Technology in Smart Devices and IoT Applications
One of the key trends in the global wireless power transmission market is the growing integration of wireless charging technology in smart devices and Internet of Things (IoT) applications. Smart home devices, including smart speakers, thermostats, and lighting systems, increasingly incorporate wireless power solutions to enhance user convenience and device aesthetics by eliminating cable clutter. IoT devices across various industrial applications, such as sensors, monitoring systems, and smart meters, benefit from wirelessly powered solutions that facilitate efficient energy management and uninterrupted operations. The expansion of wireless charging standards, such as Qi for consumer devices, has further accelerated this trend, allowing seamless compatibility between multiple devices and chargers. As smart and connected devices continue to proliferate in residential, commercial, and industrial environments, the demand for efficient wireless power transmission solutions is set to rise significantly. For instance, according to a report by the Wireless Power Consortium, over 1 billion Qi-certified wireless charging devices were shipped globally by 2021, demonstrating the widespread adoption of wireless charging technology in consumer electronics.
Advancements in Long-Range and High-Power Wireless Charging Technologies
Another significant trend is the advancement in long-range and high-power wireless charging technologies. Traditional wireless charging was primarily limited to short-range, inductive charging, suitable mainly for small devices like smartphones. However, recent technological breakthroughs have enabled more efficient medium and long-range power transmission through methods such as magnetic resonance and radiofrequency waves. These developments have expanded wireless charging's application scope to include electric vehicles (EVs), industrial robots, drones, and even household appliances. Long-range wireless power transmission can provide energy over greater distances, improving convenience for users and enabling new use cases, such as dynamic in-motion EV charging. These technological advancements are further supported by ongoing investments in research and collaboration among industry stakeholders to enhance efficiency, safety, and interoperability. For instance, researchers at the University of Tokyo have successfully demonstrated wireless power transmission over a distance of 10 meters using a system based on magnetic resonance coupling, capable of delivering up to 50 watts of power. As these innovations gain market traction, they are expected to transform the energy infrastructure of various sectors and redefine the possibilities for wireless power applications.
Market Restraints and Challenges
Limited Efficiency and Power Transfer Range
One of the significant challenges facing the wireless power transmission market is the relatively limited efficiency and power transfer range of current technologies. While advances in wireless power transmission have improved charging efficiency, it remains lower than that of traditional wired charging methods. Wireless power transmission technologies like inductive charging still require relatively close proximity between the transmitter and receiver to function optimally, limiting their range and convenience. This can be a significant hurdle for applications that require longer-range or higher power, such as electric vehicle charging, large-scale industrial equipment, or high-performance consumer electronics. Additionally, the efficiency of energy transfer decreases as the distance between the transmitter and receiver increases, which could hinder widespread adoption in sectors requiring substantial power. These limitations also raise concerns about potential energy losses and reduced charging speeds, which may deter consumers and industries from fully embracing wireless power solutions in some applications.
High Costs and Infrastructure Development
The implementation of wireless power transmission solutions often involves high initial costs for both manufacturers and consumers. The development of wireless charging systems, including the required transmitters, receivers, and integration technologies, requires substantial investment in research, design, and production. Furthermore, infrastructure deployment, particularly for large-scale applications like electric vehicles or public transportation, demands significant capital expenditure. For example, establishing wireless charging pads for EVs on roads and highways or installing wireless charging systems in public spaces can be expensive and logistically challenging. These high costs can slow down market adoption, especially in regions or industries with limited budgets. Additionally, there are infrastructure compatibility concerns, as existing devices and systems may need to be modified or replaced to accommodate wireless charging. The need for standardization and regulatory frameworks also poses challenges to ensuring interoperability between different wireless power technologies and devices, further complicating widespread adoption.
Market Segmentation Analysis
By technology
Wireless power transmission can be categorized into near-field and far-field technologies. Near-field technology relies on electromagnetic induction to transfer energy over short distances, typically a few millimeters to centimeters, and is commonly used in smartphones, wearables, and consumer electronics. Its adoption is driven by low cost, ease of integration, and well-established standards like Qi for mobile devices, though its short range limits its use to smaller devices placed close to a charging pad. Far-field technology, on the other hand, uses radiofrequency (RF) or microwave power transfer to deliver energy over longer distances, ranging from centimeters to meters. It is gaining traction in applications like electric vehicle (EV) charging, industrial equipment, and IoT devices due to its flexibility and the ability to charge devices without precise alignment. However, challenges like reduced efficiency over long distances and regulatory concerns hinder its widespread adoption, though advancements such as beamforming and adaptive resonance are improving its performance and driving growth in this segment.
By Type
Segments
Based on Technology
- Near-Field Technology
- Far-Field Technology
Based on Type
- Devices with Battery
- Devices without Battery
Based on Application
- Receiver
- Transmitter
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (30%):
North America holds a significant share of the global wireless power transmission market, accounting for approximately 30% of the market in 2023. The region is a leader in technological innovation and adoption, with a high concentration of key market players and research institutions. The demand for wireless power solutions in North America is primarily driven by the increasing adoption of wireless charging technology in consumer electronics, electric vehicles, and medical devices. The United States, in particular, has seen widespread integration of wireless charging systems in smartphones, wearables, and other portable devices. The development of infrastructure for wireless EV charging and government policies supporting clean energy solutions further enhance the market growth in this region. The market is expected to continue growing due to strong technological advancements and the region's early adoption of new technologies.
Asia-Pacific (35%)
The Asia-Pacific region is the largest and fastest-growing market for wireless power transmission, capturing about 35% of the market share in 2023. This dominance is largely due to the strong manufacturing base in countries like China, Japan, and South Korea, where there is extensive production of consumer electronics, smartphones, and electric vehicles. The region's rapid urbanization and the growing popularity of electric mobility also contribute significantly to the market's expansion. China, in particular, is a major player in the production of wireless charging components, and the increasing integration of wireless power technologies in consumer electronics, such as smartphones, is boosting market growth. The government's support for the development of wireless power solutions and infrastructure is expected to further accelerate growth in the region.
Key players
- Analog Devices Inc.
- Energous Corporation
- Koninklijke Philips N.V.
- NXP Semiconductors N.V.
- Powermat Technologies Ltd.
- Renesas Electronics Corporation
- Samsung Electronics Co. Ltd.
- Semtech Corporation
- TDK Corporation
- WiTricity Corporation
Competitive Analysis
The wireless power transmission market is highly competitive, with several key players leading technological advancements and driving innovation. Analog Devices Inc. and NXP Semiconductors N.V. are prominent for their semiconductor solutions that support wireless power transmission, catering to industries ranging from automotive to consumer electronics. WiTricity Corporation and Energous Corporation are pioneers in long-range wireless power technologies, aiming to expand wireless charging capabilities beyond short distances. Samsung Electronics Co. Ltd. and Koninklijke Philips N.V. leverage their strong presence in consumer electronics, offering integrated wireless charging solutions for mobile devices, wearables, and home appliances. Companies like TDK Corporation and Renesas Electronics Corporation focus on providing components that enhance efficiency and integration. As the market grows, collaboration and strategic partnerships are expected to intensify, with leading players striving to improve power transfer efficiency, range, and compatibility across a diverse range of applications.
Recent Developments
- In **February 2024**, Analog Devices showcased its advanced 5G wireless technologies at Mobile World Congress (MWC) 2024, including innovations in Radio Units (RU) that reduce energy consumption by more than 40%. This technology is part of their RadioVerse Transceiver SoC family, which helps improve the efficiency of 5G networks.
- In **March 2023**, Energous received U.S. FCC approval for its WattUp 900MHz Active Energy Harvesting transmitter technology, enabling wireless power transfer over longer distances for IoT devices. This development supports the simultaneous charging of multiple devices and enhances IoT deployment in sectors like retail and industrial applications.
- In **November 2023**, Philips introduced a new line of smart healthcare devices integrated with wireless charging capabilities, aimed at improving patient care by reducing cable clutter and enhancing device portability in clinical environments (no specific source available).
- In **August 2023**, NXP launched the first Qi 1.3 certified automotive wireless charging reference design, which includes secure authentication features to ensure safe wireless power transfer in vehicles. This design allows developers to create Qi-certified wireless chargers for automotive applications.
- In **July 2023**, Powermat announced a collaboration with Powercast to offer comprehensive wireless power solutions that combine short- and long-range wireless charging technologies, targeting consumer electronics and industrial applications.
- In **October 2023*, Renesas launched a new wireless power receiver IC designed for industrial IoT applications, enabling efficient power transfer for sensors and monitoring devices in harsh environment.
- In **January 2024**, Samsung unveiled its latest Galaxy smartphones featuring enhanced wireless charging speeds using their proprietary Fast Wireless Charging 2.0 technology, further improving user convenience and device performance.
- In **March 2024**, Semtech introduced the Tri-Edge™ GN2256 chipset for high-speed data transmission in 5G networks, paving the way for future advancements in 6G technology. This innovation supports Dense Wavelength Division Multiplexing (DWDM) systems to enhance network capacity.
- In **June 2023**, TDK launched a new small, low-output wireless power transfer system capable of simultaneously charging multiple devices with improved positioning flexibility, addressing challenges in electromagnetic induction systems for wearables and healthcare devices.
- In **April 2024**, WiTricity launched a pilot program at the Port of Long Beach to wirelessly charge Ford E-Transit electric vehicles using its Halo™ wireless EV charging system. This initiative aims to reduce operational costs and enhance fleet electrification efforts.
Market Concentration and Characteristics
The Global Wireless Power Transmission Market exhibits moderate to high market concentration, with a few key players holding significant market share, while numerous smaller companies and startups contribute to innovation and market growth. Leading players like Samsung Electronics, WiTricity Corporation, Analog Devices Inc., and Energous Corporation dominate the market, primarily through advanced technological solutions, strong intellectual property portfolios, and large-scale investments in research and development. These players are driving the adoption of wireless power transmission in sectors such as consumer electronics, automotive, healthcare, and industrial applications. Despite the dominance of these key players, the market remains dynamic with ongoing technological advancements, such as the development of long-range power transmission and higher efficiency systems, fostering healthy competition. The market is characterized by rapid innovation, strategic partnerships, and collaborations, aimed at enhancing charging speed, distance, and overall energy efficiency, contributing to market fragmentation and diversity.
Report Coverage
The research report offers an in-depth analysis based on Technology, Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continuous advancements in wireless power technologies, such as resonant inductive coupling and radiofrequency-based transmission, will increase charging range, speed, and efficiency. This will make wireless power solutions more viable for a wider array of applications.
- The rising adoption of electric vehicles will drive the demand for wireless EV charging infrastructure, particularly as the automotive industry pushes for cleaner and more convenient charging solutions.
- As the Internet of Things (IoT) continues to expand, wireless power transmission will be crucial in supporting the energy demands of a growing network of interconnected smart devices, sensors, and systems.
- The growing demand for wireless charging in smartphones, wearables, and other consumer electronics will remain a key driver for the market, with increased integration of wireless power systems into everyday devices.
- The development of universal wireless charging standards will drive market adoption, ensuring that devices across various industries are compatible with different wireless power solutions.
- Wireless power transmission will see greater application in medical devices, particularly for implantable devices like pacemakers, insulin pumps, and neurostimulators, improving patient comfort and device reliability.
- The rise of smart homes will accelerate the demand for wireless charging solutions, as consumers seek seamless, cable-free environments to power their devices and appliances.
- Industries will increasingly adopt wireless power transmission for powering robots, automated systems, and other equipment, enhancing operational efficiency and reducing the need for maintenance.
- Governments worldwide are expected to implement supportive regulations and standards, promoting the development of wireless power infrastructure and encouraging businesses to adopt these technologies.
- While North America and Asia-Pacific dominate the market, significant growth is anticipated in regions like Europe, Latin America, and the Middle East, driven by infrastructure investments and the adoption of green technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of Consumer Electronics and Portable Devices
The widespread adoption of smartphones, wearables, and other portable electronics is fueling demand for convenient, cable-free charging solutions, making wireless power transmission increasingly essential for everyday device usage.
Growth in Electric Vehicles and Automotive Applications
The rising global adoption of electric vehicles is driving the need for efficient, user-friendly charging infrastructure, with wireless charging offering enhanced convenience and supporting new applications like dynamic in-motion charging.
Integration in Medical Devices and Healthcare
Wireless power transmission is being rapidly adopted in the healthcare sector for implantable and portable medical devices, reducing infection risks and improving patient comfort by eliminating the need for physical connectors.
Advancements in Wireless Charging Technologies
Innovations such as resonant inductive coupling, radiofrequency, and capacitive coupling are improving the efficiency, range, and reliability of wireless power systems, enabling broader adoption across diverse applications.
Supportive Regulatory Environment and Standardization
Government incentives, regulatory support, and the development of universal wireless charging standards are accelerating market adoption by ensuring interoperability and encouraging investment in wireless power infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Wireless Power Transmission Market in 2023 and 2032?
What are the key drivers for the growth of the wireless power transmission market?
Which regions are expected to lead the wireless power transmission market?
What are the technological advancements influencing the wireless power transmission market?
How are wireless power solutions impacting consumer electronics?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Devices with Battery
- 1.2.2 Devices without Battery
- 1.3 By Technology
- 1.3.1 Near-Field Technology
- 1.3.2 Far-Field Technology
- 1.4 By Application
- 1.4.1 Receiver
- 1.4.2 Transmitter
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 5,715 million → 2032: USD 26,609.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wireless Power Transmission Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wireless Power Transmission Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wireless Power Transmission Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wireless Power Transmission Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wireless Power Transmission Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wireless Power Transmission Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wireless Power Transmission Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wireless Power Transmission Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 5,715 million → 2032: USD 26,609.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wireless Power Transmission Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Devices with Battery
- 12.3.7.2 Devices without Battery
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Near-Field Technology
- 12.4.7.2 Far-Field Technology
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Receiver
- 12.5.7.2 Transmitter
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wireless Power Transmission End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wireless Power Transmission Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wireless Power Transmission Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wireless Power Transmission Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 WiTricity Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Qualcomm Incorporated
- 18.4 Energous Corporation
- 18.5 Samsung Electronics Co., Ltd.
- 18.6 Texas Instruments, Inc.
- 18.7 Analog Devices Inc.
- 18.8 NXP Semiconductors N.V.
- 18.9 Powermat Technologies Ltd.
- 18.10 TDK Corporation
- 18.11 Renesas Electronics Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

