
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Coffee Packaging Market Size 2024 | USD 816.7 million |
| Coffee Packaging Market, CAGR | 4.54% |
| Coffee Packaging Market Size 2032 | USD 1,165.16 million |
Market Overview
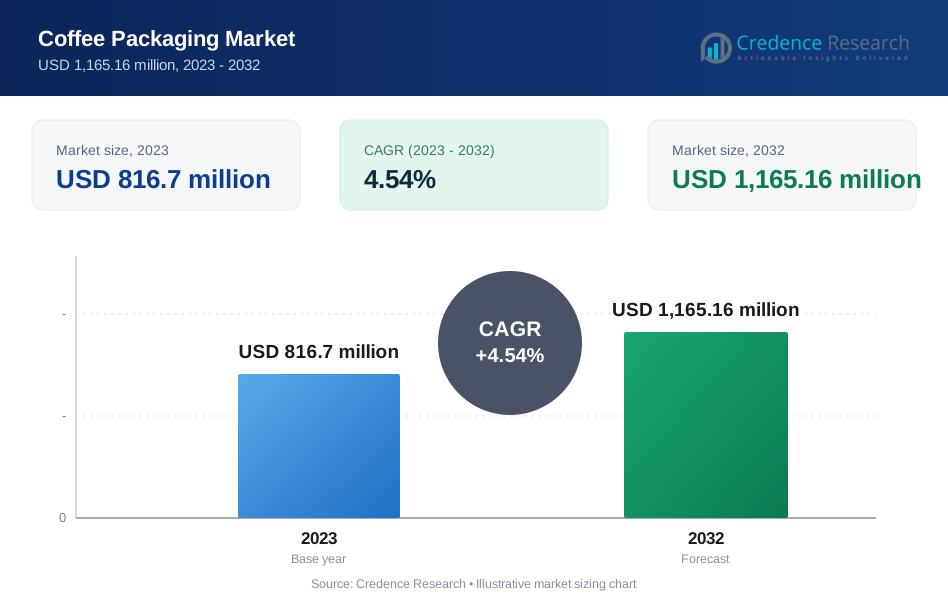
The Global Coffee Packaging Market is projected to grow from USD 816.7 million in 2023 to an estimated USD 1,165.16 million by 2032, with a compound annual growth rate (CAGR) of 4.54% from 2024 to 2032. This growth is driven by the increasing demand for coffee consumption worldwide and a rising emphasis on premium, eco-friendly, and sustainable packaging.
Key drivers in the market include the shift towards recyclable and biodegradable materials, an expanding coffee culture, and the rising popularity of specialty coffee. Additionally, trends such as single-serve packaging and flexible packaging formats are gaining momentum as consumers seek convenience and portability. Companies are investing in new technologies that cater to these evolving preferences, aligning with broader sustainability goals and meeting consumer demand for sustainable, quality-focused packaging options.
Regionally, North America and Europe are leading the coffee packaging market due to high coffee consumption rates and a well-established premium coffee segment. However, the Asia-Pacific region is expected to experience the fastest growth, driven by a surge in coffee consumption and a growing middle-class population. Key players in the global coffee packaging market include Amcor Plc, WestRock Company, Mondi Group, and Sonoco Products Company, who are actively investing in research and development to offer innovative packaging solutions that meet both functional and aesthetic consumer needs.
Market Drivers
Rising Demand for Sustainable and Eco-Friendly Packaging Solutions
As environmental awareness grows globally, the demand for sustainable and eco-friendly packaging solutions in the coffee industry has intensified. Consumers are increasingly prioritizing products with minimal environmental impact, pushing coffee brands to adopt packaging that aligns with these values. For instance, many coffee brands are now utilizing materials like recyclable paper and biodegradable plastics to meet this demand. This transition reflects a deeper commitment to reducing waste and addressing the environmental concerns that consumers prioritize when making purchasing decisions. Coffee packaging companies are investing considerable resources into research and development to create innovative packaging that protects the product while also appealing to eco-conscious customers. This trend is further supported by regulatory frameworks in multiple countries that encourage or mandate sustainable packaging practices, thus amplifying the demand for greener options within the coffee packaging market.
Growth of Premium and Specialty Coffee Markets
The growing preference for premium and specialty coffee is another significant driver shaping the coffee packaging market. Consumers are increasingly seeking high-quality, artisanal coffee experiences, which has led to a rise in specialty coffee shops and a demand for premium products. This shift is motivating coffee packaging companies to develop sophisticated, aesthetically appealing packaging solutions that reflect the quality of the coffee inside. For instance, companies are now focusing on developing packaging that not only looks appealing but also incorporates functional features like airtight seals and one-way degassing valves, essential for preserving the flavor and aroma of premium coffee. The demand for these features is especially pronounced among younger consumers and urban dwellers, who are willing to pay more for a superior coffee experience. As a result, the coffee packaging market is evolving to cater to these discerning consumers, with a focus on both functionality and design that elevates the overall product experience.
Increasing Demand for Convenient and Portable Packaging Formats
The modern consumer’s fast-paced lifestyle has created a demand for convenient and portable coffee packaging solutions. Single-serve and ready-to-drink coffee products have seen significant growth as consumers look for options that fit seamlessly into their on-the-go routines. The popularity of single-serve options and ready-to-drink products has prompted innovations in packaging, such as resealable bags and stick packs. These formats cater to busy lifestyles, allowing consumers to enjoy their coffee on-the-go without compromising on quality or convenience. Additionally, the demand for single-use, portion-controlled packaging is on the rise, particularly in office settings, travel environments, and among consumers who value convenience. Coffee packaging companies are responding by developing lightweight, durable, and easy-to-use packaging formats that maintain the quality of the coffee while meeting the portability needs of today’s consumers. This demand for convenience is driving manufacturers to explore new materials and technologies that enhance portability while ensuring product integrity.
Technological Advancements in Packaging for Enhanced Product Freshness and Shelf Life
Technological advancements in packaging are enabling coffee brands to offer products that retain freshness and extend shelf life, which is crucial for maintaining the quality and appeal of coffee. Innovations such as active and intelligent packaging, which includes features like oxygen scavengers, moisture control systems, and temperature indicators, are becoming increasingly popular in the coffee industry. These technologies help prevent oxidation and moisture buildup, which can degrade the flavor and aroma of coffee over time. Packaging solutions with one-way degassing valves are particularly significant in the market, as they allow excess carbon dioxide to escape without letting oxygen in, thereby preserving the freshness of coffee beans and ground coffee. Coffee packaging companies are continually adopting and refining these technologies to meet consumer expectations for high-quality, long-lasting products, which in turn enhances brand loyalty and drives market growth.
Market Trends
Increased Focus on Sustainable and Biodegradable Packaging Materials
Sustainability has become a cornerstone in the global coffee packaging market as consumers and brands alike shift towards environmentally friendly practices. With growing awareness of plastic pollution and the environmental impact of traditional packaging materials, companies are increasingly adopting sustainable alternatives. For instance, brands are increasingly utilizing compostable bioplastics made from renewable resources like corn starch and sugarcane. These materials not only offer durability but also decompose naturally, significantly reducing environmental impact. Companies such as Grupo Bimbo have committed to 100% sustainable packaging, reflecting a broader industry trend towards responsible practices. Moreover, innovative materials are emerging, such as mushroom-based packaging, which is created using agricultural waste and mycelium. This type of packaging decomposes rapidly and enriches the soil, showcasing the potential of natural materials in sustainable packaging solutions. Additionally, kraft paper, derived from virgin wood pulp, is gaining traction due to its biodegradability and recyclability, making it a preferred choice for many brands focused on sustainability. Furthermore, packaging companies are integrating renewable resources and recycled content into their products to reduce waste and energy consumption during production. This trend is driven by consumer demand for transparency and responsibility in packaging, as well as government regulations that mandate sustainable practices in packaging. As brands work to enhance their environmental reputation, they are finding that sustainable packaging is not only a regulatory requirement but also a valuable differentiator in an increasingly competitive market.
Growth of Smart Packaging Solutions for Enhanced Freshness and Convenience
Technological advancements in smart packaging are transforming the coffee packaging industry, offering solutions that improve product quality, freshness, and convenience. Coffee, especially in its ground form, is sensitive to factors like oxygen, moisture, and light, which can degrade its flavor and aroma. To address this, companies are incorporating features such as one-way degassing valves that allow carbon dioxide to escape while preventing oxygen from entering the package. This innovation helps maintain the coffee's freshness for an extended period. Additionally, technologies like moisture absorbers, oxygen scavengers, and temperature indicators are being integrated into coffee packaging to further extend shelf life and preserve quality. Furthermore, the addition of QR codes on packaging enables consumers to access detailed information about the coffee’s origin, flavor profile, and brewing recommendations with a simple scan. This interactive approach not only enhances the customer experience but also builds brand loyalty by providing consumers with valuable insights into the product they are purchasing. The integration of these smart technologies reflects a broader trend in the coffee packaging market towards solutions that prioritize both quality preservation and user engagement. By ensuring that coffee remains fresh while offering a more personalized experience for consumers, brands are effectively responding to evolving consumer preferences in an increasingly competitive landscape.
Market Restraints and Challenges
High Costs Associated with Sustainable Packaging Materials
While there is strong demand for eco-friendly and sustainable packaging in the coffee market, the high costs associated with these materials present a significant challenge. Biodegradable plastics, recyclable paper, and other environmentally friendly materials often come with higher production costs compared to traditional plastics and foils. The need for specialized equipment and production processes further adds to these expenses, making sustainable packaging less accessible, especially for smaller coffee brands and emerging businesses. Additionally, the volatility in raw material prices can lead to fluctuating costs, which can be a burden for companies looking to maintain consistent pricing for their products. Although some consumers are willing to pay a premium for sustainable products, others may not be, thereby limiting the market reach and posing a challenge for coffee brands that want to balance cost-effectiveness with environmental responsibility.
Regulatory Challenges and Complex Supply Chain Logistics
Regulatory frameworks surrounding packaging materials vary significantly across regions, creating a complex landscape for coffee packaging companies to navigate. In addition to general food safety regulations, companies must adhere to specific guidelines related to sustainable packaging and waste management, which can be costly and time-consuming. As countries implement stricter regulations around single-use plastics and mandate recycling practices, companies may face increased compliance costs and operational complexities. Furthermore, supply chain logistics for sourcing sustainable materials and maintaining quality control can be challenging. Sustainable materials often require specific storage and handling conditions, and disruptions in the supply chain-such as material shortages or transportation delays-can hinder a company’s ability to produce and distribute packaging consistently. These regulatory and logistical challenges add layers of complexity, limiting the ability of coffee packaging companies to respond quickly to market demands and regulatory changes, thus impacting their overall operational efficiency.
Market Segmentation Analysis
By Packaging Type
Coffee packaging varies widely by type to cater to diverse consumer preferences and product requirements. Pouches, especially stand-up varieties, are popular for ground coffee and beans due to their lightweight, flexible design with resealable zippers and degassing valves that maintain freshness. Side gusseted bags are durable and spacious, ideal for bulk coffee and favored by specialty brands for their stability on shelves and branding potential. Block bottom bags combine the benefits of stand-up and gusseted designs, appealing to premium brands with their sturdy, space-saving structure. Stick packs provide single-serve convenience for on-the-go consumers, while bag-in-box solutions are practical for commercial settings, storing liquid concentrates in durable packaging. Bottles, typically glass or plastic, are used for ready-to-drink coffee products, offering a premium feel and portability, while cans, particularly aluminum, are valued for their recyclability and ability to preserve flavor, ideal for both ground and ready-to-drink options. Hard containers and boxes cater to luxury coffee gifts, offering robust protection and more space for branding, while sacks, often made from burlap or jute, suit bulk distribution, especially for export. Lastly, niche options like reusable tins, eco-friendly pouches, and multi-pack kits meet the specific needs of organic coffee brands and subscription services, providing flexible solutions for varying market segments.
By Packaging Material
The Global Coffee Packaging Market utilizes various materials, each catering to different needs for protection, sustainability, and consumer appeal. Plastic remains widely used due to its versatility, durability, and cost-effectiveness, with flexible films like PET and polyethylene offering lightweight protection. However, environmental concerns are driving a shift toward recyclable and biodegradable plastics. Metal, particularly aluminum, is extensively used for cans and bag-in-box solutions due to its excellent barrier properties and recyclability, appealing to eco-conscious brands. Paper packaging, favored for its natural, eco-friendly image, is often chosen for pouches and bags, with many brands enhancing its durability through laminates and coatings. Glass, typically used for ready-to-drink bottles and premium products, offers an upscale appearance and complete recyclability, despite being heavier and less portable. Additionally, innovative materials such as biodegradable films, compostable bioplastics, and plant-based solutions are emerging, catering to niche segments focused on sustainable practices and aligning with consumer preferences for ethical packaging options.
Segments
Based on Packaging Type
- Pouches
- Side Gusseted Bag
- Block Bottom Bag
- Stick Pack
- Bag in Box
- Bottles
- Cans
- Containers and Boxes
- Sacks
- Others
Based on Packaging Material
- Plastic
- Metal
- Paper
- Glass
- Others
Based on Application
- Retail Sales
- Institutional Sales
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
North America (28%):
North America holds a substantial portion of the global coffee packaging market, accounting for approximately 28% of the market share. This region is characterized by a high demand for premium and specialty coffee products, particularly in the United States and Canada, where coffee consumption is an integral part of daily life. Consumers in North America are increasingly focused on sustainable packaging solutions, prompting manufacturers to innovate with eco-friendly materials. Additionally, the growing trend of ready-to-drink (RTD) coffee products has boosted the demand for convenient, portable packaging such as cans, bottles, and single-serve options.
Europe (25%):
Europe closely follows North America, with around 25% of the market share, fueled by the region’s well-established coffee culture. Countries such as Germany, Italy, and France are prominent consumers, with a strong emphasis on quality and premiumization in coffee products. European consumers are also highly conscious of environmental impacts, which drives demand for recyclable and biodegradable packaging materials, especially in Western Europe. In response to stringent European Union regulations on single-use plastics, coffee packaging companies are focusing on sustainable alternatives, such as paper-based and plant-derived materials, to meet regional preferences and regulatory requirements.
Key players
- Amcor Limited
- Constantia Flexibles Group GmbH
- Goglio S.p.A.
- Graham Packaging Company
- Huhtamaki Oyj
- ProAmpac
- Roastar Inc.
- Sonoco Products Company
- Swiss Pack
- WestRock Company
Competitive Analysis
The Global Coffee Packaging Market is highly competitive, with leading players such as Amcor Limited, Constantia Flexibles, and WestRock Company driving innovation through sustainable and premium packaging solutions. These companies are investing in research and development to meet consumer demands for recyclable, biodegradable, and high-quality packaging materials. Additionally, players like ProAmpac and Sonoco are focused on expanding their product portfolios and enhancing production capabilities through acquisitions and partnerships. Smaller players such as Roastar Inc. and Swiss Pack differentiate themselves by offering customized and flexible packaging solutions tailored to niche markets, such as specialty coffee brands. To maintain their competitive edge, many of these companies are increasingly aligning with eco-friendly initiatives, responding to both regulatory pressures and consumer preferences for sustainability. As competition intensifies, companies that can balance innovation, cost-effectiveness, and sustainability are likely to capture greater market share and build lasting customer loyalty.
Recent Developments
- In October 2023, Amcor partnered with Löfbergs to launch a new recycle-ready coffee packaging solution. This innovative mono-material pouch is designed for both chemical and mechanical recycling and boasts a 55% reduced carbon footprint compared to previous packaging. The product is now available in stores across Sweden, marking a significant step towards sustainable coffee packaging solutions in the industry.
- In September 2023, Constantia Flexibles announced the introduction of its new line of biodegradable coffee packaging. This initiative aims to meet the growing consumer demand for sustainable options while ensuring product freshness and quality. The new packaging is made from renewable resources and is designed to decompose naturally, aligning with the company's commitment to environmental sustainability.
- In August 2023, Goglio launched a new range of multi-layered coffee packaging films that enhance barrier properties while remaining eco-friendly. This development aims to extend the shelf life of coffee products without compromising on sustainability. The new films are made from recyclable materials and are expected to attract environmentally conscious consumers.
- In July 2023, Graham Packaging unveiled its latest line of lightweight, recyclable coffee containers. These containers are designed to reduce plastic usage while maintaining the integrity of the coffee inside. The initiative is part of Graham's broader strategy to innovate sustainable packaging solutions across various beverage sectors.
- In June 2023, Huhtamaki launched a new compostable coffee cup that can be used for both hot and cold beverages. This product is aimed at reducing single-use plastic waste in the coffee industry and has been well-received by environmentally conscious consumers looking for sustainable options.
- In May 2023, ProAmpac introduced its new line of flexible coffee packaging that incorporates post-consumer recycled content. This initiative not only enhances sustainability but also responds to consumer demand for more environmentally friendly products in the coffee sector
- In April 2023, Roastar launched an innovative custom printing option for their coffee bags, allowing brands to showcase their identity while using eco-friendly materials. This development emphasizes Roastar's commitment to sustainability and customer engagement in the coffee packaging market.
- In March 2023, Sonoco announced a partnership with several coffee brands to develop sustainable paper-based coffee packaging solutions. This collaboration aims to reduce reliance on plastic and enhance recyclability within the industry.
- In February 2023, Swiss Pack introduced a new line of biodegradable coffee bags that feature enhanced barrier properties. These bags are aimed at preserving freshness while being environmentally friendly, catering to the increasing demand for sustainable packaging options.
- In January 2023, WestRock launched its latest eco-friendly coffee packaging solutions made from recycled materials. This initiative reflects WestRock's commitment to sustainability and addresses consumer preferences for responsible packaging choices in the coffee market.
Market Concentration and Characteristics
The Global Coffee Packaging Market is moderately fragmented, with a mix of large multinational corporations and smaller specialized companies competing to meet diverse consumer needs. Market concentration is influenced by the presence of key players such as Amcor, Constantia Flexibles, and WestRock, which hold significant shares due to their extensive product portfolios, technological advancements, and global reach. These larger players leverage economies of scale and invest heavily in sustainable packaging solutions to stay ahead in the competitive landscape. Meanwhile, smaller companies like Roastar Inc. and Swiss Pack focus on niche segments, offering customized and flexible packaging options that cater to artisanal and specialty coffee brands. The market is characterized by a strong emphasis on innovation, driven by rising consumer demand for convenience, premiumization, and eco-friendly packaging materials. As environmental regulations continue to shape the industry, companies are increasingly adopting sustainable practices to align with consumer preferences and regulatory requirements.
Report Coverage
The research report offers an in-depth analysis based on Packaging Type, Packaging Material, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As environmental concerns grow, the market will continue to shift toward eco-friendly packaging solutions, with increased use of recyclable, biodegradable, and compostable materials across all packaging formats.
- Companies will invest in advanced designs, such as resealable pouches, multi-layered bags, and packaging with one-way valves, to enhance product freshness, improve convenience, and meet premium market demands.
- With the rise in demand for RTD coffee products, particularly among younger consumers, packaging companies will expand offerings of bottles, cans, and single-serve formats that cater to on-the-go lifestyles.
- Asia-Pacific, Latin America, and Africa are expected to witness significant growth in coffee consumption, driving demand for diverse and affordable coffee packaging solutions tailored to these regions' unique preferences.
- The integration of smart packaging technologies, such as QR codes and NFC tags, will grow, allowing consumers to access information about coffee origins, sustainability practices, and product details.
- Customizable packaging options will become increasingly popular, as brands seek to differentiate their products and engage customers with unique and visually appealing designs.
- As the demand for high-quality, specialty coffee rises, packaging companies will develop luxury-oriented solutions, including sleek glass bottles, elegant containers, and artistic pouches that reflect premium quality.
- With countries implementing stricter environmental regulations, packaging companies will need to adapt to evolving compliance standards, particularly concerning plastic reduction and sustainable waste management.
- Flexible packaging formats, like pouches and stick packs, will continue to gain popularity due to their lightweight, cost-effective nature, and adaptability to different coffee product types and consumer preferences.
- To expand their market presence and enhance technological capabilities, companies will pursue mergers, acquisitions, and partnerships, especially as larger players seek to integrate smaller, innovative firms into their portfolios.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Sustainable and Eco-Friendly Packaging
Growing environmental awareness and regulatory pressures are pushing coffee brands to adopt recyclable, biodegradable, and compostable packaging materials, driving innovation and investment in sustainable solutions.
Expansion of Premium and Specialty Coffee Segments
Rising consumer demand for high-quality, artisanal coffee is motivating brands to invest in premium packaging with features like airtight seals and attractive designs, enhancing product appeal and shelf presence.
Growth in Single-Serve and Convenient Packaging Formats
Busy lifestyles and the popularity of on-the-go coffee consumption are fueling demand for single-serve, portable packaging such as stick packs, cans, and resealable pouches, prompting manufacturers to develop more convenient solutions.
Technological Advancements for Product Freshness
Innovations such as one-way degassing valves, multi-layered barrier films, and smart packaging technologies are helping to preserve coffee freshness and extend shelf life, meeting consumer expectations for quality.
Rising Coffee Consumption in Emerging Markets
Increasing coffee consumption in Asia Pacific, Latin America, and Africa, driven by urbanization and a growing middle class, is expanding the market for diverse and affordable coffee packaging solutions tailored to regional preferences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Coffee Packaging Market?
What are the primary drivers of the Global Coffee Packaging Market?
Which regions are leading the coffee packaging market?
What types of packaging are most popular in the coffee industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Retail Sales
- 1.2.2 Institutional Sales
- 1.3 By Packaging Type
- 1.3.1 Pouches
- 1.3.2 Side Gusseted Bag
- 1.3.3 Block Bottom Bag
- 1.3.4 Stick Pack
- 1.3.5 Bag in Box
- 1.3.6 Bottles
- 1.3.7 Cans
- 1.3.8 Containers and Boxes
- 1.3.9 Sacks
- 1.3.10 Others
- 1.4 By Packaging Material
- 1.4.1 Plastic
- 1.4.2 Metal
- 1.4.3 Paper
- 1.4.4 Glass
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 816.7 million → 2032: USD 1,165.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Coffee Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Coffee Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Coffee Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Coffee Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Coffee Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Coffee Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Coffee Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Coffee Packaging Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 816.7 million → 2032: USD 1,165.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Coffee Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Retail Sales
- 12.3.7.2 Institutional Sales
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pouches
- 12.4.7.2 Side Gusseted Bag
- 12.4.7.3 Block Bottom Bag
- 12.4.7.4 Stick Pack
- 12.4.7.5 Bag in Box
- 12.4.7.6 Bottles
- 12.4.7.7 Cans
- 12.4.7.8 Containers and Boxes
- 12.4.7.9 Sacks
- 12.4.7.10 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging Material - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Plastic
- 12.5.7.2 Metal
- 12.5.7.3 Paper
- 12.5.7.4 Glass
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Coffee Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Coffee Packaging Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Coffee Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Coffee Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Constantia Flexibles Group GmbH
- 18.4 Goglio S.p.A.
- 18.5 Graham Packaging Company
- 18.6 Huhtamaki Oyj
- 18.7 ProAmpac
- 18.8 Roastar Inc.
- 18.9 Sonoco Products Company
- 18.10 Swiss Pack
- 18.11 WestRock Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

