
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Underground Mining Equipment Market Size 2023 | USD 6,444.71 Million |
| Europe Underground Mining Equipment Market, CAGR | 3.72% |
| Europe Underground Mining Equipment Market Size 2032 | USD 8,959.58 Million |
Market Overview
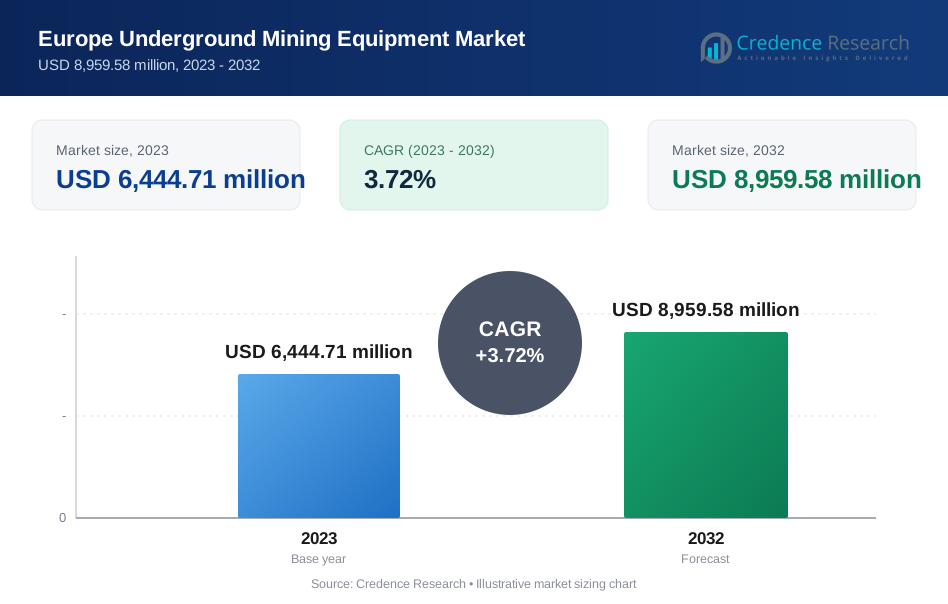
The Europe Underground Mining Equipment Market is projected to grow from USD 6,444.71 million in 2023 to an estimated USD 8,959.58 million by 2032, with a compound annual growth rate (CAGR) of 3.72% from 2024 to 2032. This growth is driven by the increasing demand for underground mining equipment, fueled by advancements in technology and growing mineral extraction activities across the region.
Key drivers of this market include the increasing demand for minerals such as coal, metals, and industrial minerals, which are essential for industrial activities. Technological advancements, such as automation, electrification, and innovations in equipment efficiency, are expected to continue shaping the landscape. Moreover, stringent regulations around safety and environmental concerns are pushing mining companies to invest in modern and advanced underground mining solutions.
Geographically, Europe holds a significant position in the underground mining equipment sector, with countries like Germany, Russia, and Sweden being key contributors. The market is driven by a combination of established mining infrastructure and a focus on improving operational efficiency. Key players in this market include Caterpillar Inc., Sandvik AB, Komatsu Ltd., and Volvo Group, all of whom are actively investing in research and development to meet the evolving demands of the underground mining sector in Europe.
Market Drivers
Increasing Demand for Minerals and Natural Resources
The demand for minerals such as coal, metals, and industrial minerals is one of the primary drivers of the underground mining equipment market in Europe. As industrial activities continue to rise across various sectors, including construction, manufacturing, and energy production, the need for raw materials such as copper, iron ore, and coal has become crucial. These minerals are integral to the production of steel, electronics, and energy generation, among others. For instance, the increasing industrial activities across Europe have led to a significant rise in the demand for essential minerals. The European Union's commitment to reducing reliance on external sources for critical raw materials has resulted in heightened local mining operations, thereby necessitating advanced underground mining equipment. This shift is evident as mining companies are actively investing in new technologies and machinery to enhance extraction efficiency and meet the growing resource needs. Additionally, with ongoing exploration projects and the requirement for deeper mining operations, there is a clear trend towards the adoption of specialized equipment designed for efficient and safe underground mining practices. As a result, mining companies are increasing their investments in mining equipment to enhance productivity and meet the growing demand for these resources. In particular, the European Union’s focus on reducing dependency on external sources for critical raw materials has also led to a boost in local mining activities, further increasing the demand for advanced underground mining equipment. With new exploration projects underway and existing mines requiring deeper operations, the need for specialized underground mining machinery to support efficient extraction processes is projected to grow.
Technological Advancements in Underground Mining Equipment
Technological innovation plays a critical role in the growth of the Europe underground mining equipment market. Innovations in automation, digitization, and electrification are transforming how underground mining operations are carried out, contributing to increased efficiency, safety, and cost-effectiveness. Automation, in particular, is a major trend in the mining industry, as it allows for the reduction of human labor in hazardous underground environments. Automated drilling, loading, and transport systems reduce the risk of injuries and enhance operational productivity. Additionally, the integration of technologies such as remote monitoring, machine learning, and artificial intelligence enables mining companies to optimize their operations, improve decision-making, and predict equipment failures before they occur. The shift toward electric-powered mining equipment, such as battery-powered loaders and haul trucks, is another crucial development as it addresses environmental concerns and reduces carbon emissions, aligning with Europe’s sustainability goals. As technology continues to evolve, the adoption of more advanced underground mining equipment will drive the market’s growth.
Stringent Regulations and Environmental Standards
The increasing focus on safety and environmental concerns is another key driver of the underground mining equipment market in Europe. The European Union (EU) has implemented stringent regulations aimed at minimizing the environmental impact of mining activities, particularly in relation to emissions and waste management. These regulations are pushing mining companies to adopt more sustainable practices and invest in advanced equipment that meets the required environmental standards. For example, the introduction of electric-powered machinery helps reduce air pollution and carbon emissions associated with traditional diesel-powered mining equipment. Furthermore, safety regulations in Europe are increasingly focusing on ensuring the well-being of workers in underground mining environments. Equipment designed with enhanced safety features-such as collision avoidance systems, better ventilation systems, and real-time hazard monitoring-is gaining prominence. To comply with these regulations and improve the efficiency and sustainability of operations, mining companies are increasingly turning to advanced underground mining equipment. These regulatory pressures will continue to drive the demand for modern and environmentally-friendly mining machinery, fueling market growth.
Need for Improved Operational Efficiency and Cost Reduction
The mining industry is under constant pressure to improve operational efficiency and reduce costs, which is further driving the demand for innovative underground mining equipment. Mining operations, particularly in challenging underground environments, require equipment that can operate at maximum efficiency to reduce downtime and operational expenses. Modern underground mining equipment is designed to optimize performance and enhance productivity by using automated systems that streamline workflows, improve resource allocation, and reduce energy consumption. Moreover, the adoption of real-time monitoring and data analytics allows mining companies to optimize equipment usage, identify potential issues, and extend the lifespan of machinery. These efficiency gains are crucial in an industry where margins can be thin, and operational costs can significantly affect profitability. As mining companies face increasing pressures to improve cost-effectiveness and optimize their operations, the demand for high-performance underground mining equipment is expected to grow. Additionally, equipment that is more durable and reliable, requiring less maintenance, further contributes to the reduction of operational costs. Thus, the need for enhanced operational efficiency and cost reduction remains a key driver of the underground mining equipment market in Europe.
Market Trends
Adoption of Automation and Digitization
One of the most prominent trends in the Europe Underground Mining Equipment Market is the growing adoption of automation and digitization in mining operations. Automation is reshaping underground mining by enabling processes such as drilling, blasting, loading, and hauling to be carried out with minimal human intervention. The use of automated machinery, including autonomous vehicles and robots, is improving the efficiency, safety, and productivity of mining operations, especially in challenging underground environments. For instance, the integration of advanced technologies such as autonomous haul trucks and drilling rigs is becoming commonplace in European underground mining operations. These automated systems are designed to operate with minimal human intervention, significantly enhancing operational safety and efficiency. Companies like Sandvik AB have introduced systems such as the Intelligent Automine System, which allows for real-time monitoring and control of mining equipment, thereby reducing risks associated with manual operations. This shift not only streamlines processes but also aligns with the broader trend toward Industry 4.0, where interconnected devices improve productivity and reduce environmental impacts. Digitization is also playing a vital role, with the integration of Internet of Things (IoT) sensors, machine learning, and real-time data analytics in mining equipment. These technologies help operators monitor the health of equipment, predict maintenance needs, and optimize the performance of mining operations. Real-time monitoring enables better decision-making and more precise control of underground operations, ensuring optimal resource utilization and minimizing downtime. The demand for more advanced, automated, and data-driven solutions is expected to grow as mining companies seek to improve their operational efficiency, reduce costs, and comply with increasingly stringent safety regulations.
Shift Towards Electrification and Sustainable Practices
Another significant trend in the Europe Underground Mining Equipment Market is the shift towards electrification and more sustainable mining practices. For example, many European mining firms are transitioning to electric-powered equipment to comply with stringent environmental regulations. Electric loaders and haul trucks are being adopted due to their ability to minimize carbon emissions while providing lower operational costs compared to traditional diesel-powered machines. Innovations in battery technology are facilitating this transition, making electric vehicles more viable for widespread use in underground mining. In response to environmental concerns and regulatory pressures, mining companies are increasingly investing in electric-powered underground mining equipment. Electric loaders, haul trucks, and drills are gaining popularity as they offer several advantages over traditional diesel-powered equipment, including reduced carbon emissions, lower energy consumption, and quieter operations. Additionally, the shift towards electrification is aligned with Europe’s aggressive sustainability goals, including reducing the carbon footprint of industrial sectors. Several European mining companies are setting ambitious targets to reduce their environmental impact, and the adoption of electric mining equipment is a key part of these efforts. The push for cleaner, greener mining solutions is expected to continue to shape the market, driving demand for advanced, sustainable mining machinery that meets both regulatory standards and the industry's long-term environmental goals.
Market Restraints and Challenges
High Initial Investment and Operational Costs
One of the primary challenges faced by the Europe Underground Mining Equipment Market is the high initial investment required for advanced machinery and equipment. The cost of purchasing, installing, and maintaining sophisticated underground mining equipment, such as automated systems, electric-powered vehicles, and advanced drilling machines, can be prohibitive, particularly for small and medium-sized mining companies. Additionally, the upfront cost of implementing automation and electrification technologies may deter companies from making the necessary investments, despite the long-term benefits. Moreover, even though automated and electric-powered equipment can lead to significant operational savings in terms of fuel and labor costs, the operational expenses associated with training personnel, maintaining sophisticated systems, and ensuring compatibility with existing infrastructure are still considerable. These factors contribute to a reluctance among some mining companies to adopt the latest technologies, especially in regions where the mining industry is facing cost-cutting pressures or where profit margins are thin. This restraint could slow the adoption of newer technologies and, in turn, limit overall market growth.
Geological and Environmental Challenges
Underground mining operations face inherent geological and environmental challenges that can impede the efficient extraction of resources and the effective deployment of mining equipment. In Europe, mines often operate in complex geological formations, which can make it difficult to predict ore body locations, increase operational risks, and complicate the design and execution of mining processes. The difficult terrain and varying ground conditions can place additional demands on mining equipment, leading to increased wear and tear and the need for frequent maintenance. Furthermore, environmental factors, such as stringent regulations on emissions, waste management, and safety standards, continue to pose challenges for mining companies. Compliance with these regulations often requires significant investments in specialized equipment, monitoring systems, and personnel training. While there is a strong drive for sustainability in Europe, some mining operations still struggle to balance profitability with these rigorous environmental standards, which can result in delays and higher costs. These geological and environmental challenges create hurdles for efficient and cost-effective mining operations, potentially limiting the pace of market growth in the region.
Market Segmentation Analysis
By Product Type
The Europe underground mining equipment market by product type includes mining loaders, trucks, drills, bolters, and shearers, each playing a vital role in mining operations. Mining loaders, essential for transporting materials from underground sites, are increasingly sought after for their productivity-enhancing and fuel-efficient capabilities, with automated options gaining traction to improve safety. Mining trucks, designed for high-capacity transport in challenging conditions, are evolving with innovations that enhance payload, fuel efficiency, and maneuverability. Drilling equipment remains crucial for underground exploration, with advanced drills offering greater precision and lower costs to optimize operations. Mining bolters ensure structural stability by reinforcing rock surfaces, with rising safety demands spurring automation and enhanced features. Meanwhile, mining shearers, used in longwall mining, benefit from advancements that boost productivity and reduce operational wear.
By Mining Technique
The demand for underground mining equipment in soft rock mining, including coal and salt extraction, remains strong, with a focus on precision cutting and productivity in less complex geological settings. In contrast, hard rock mining, which involves extracting valuable minerals such as gold, copper, and zinc, requires highly specialized equipment capable of operating under extreme pressure and challenging conditions. This segment is driven by increased exploration activities and evolving needs in ore extraction, spurring continual innovation and technological advancement.
Segments
Based on Product Type
- Mining Loaders
- Mining Trucks
- Mining Drills
- Mining Bolters
- Mining Shearer
Based on Mining Technique
- Soft Rock Mining
- Hard Rock Mining
Based on End User
- Mining Operators
- Rental Service Providers
Based on Region
- Southern Europe
- Northern Europe
- Western Europe
- Eastern Europe
Regional Analysis
Western Europe (45%):
Western Europe dominates the Europe Underground Mining Equipment Market, holding the largest market share. Countries such as Germany, the United Kingdom, France, and Italy are the major contributors to this region. The market is driven by a combination of advanced mining technology adoption, stringent safety and environmental regulations, and the continued extraction of minerals such as coal, copper, and precious metals. Germany, in particular, has a strong presence in mining equipment manufacturing and is a key player in the mining equipment supply chain. Additionally, the shift towards automation, electrification, and sustainability is prominent in Western Europe, where mining companies are focused on reducing environmental impacts while enhancing efficiency and productivity. The implementation of cleaner technologies, such as battery-powered underground mining equipment, is expected to further boost growth in this region.
Eastern Europe (35%):
Eastern Europe is another significant region in the underground mining equipment market. Countries like Russia, Poland, and Ukraine are the primary contributors to this segment. Russia, in particular, plays a critical role in the mining sector, with vast mineral resources and a strong demand for mining equipment. The demand for underground mining equipment in this region is influenced by large-scale coal mining and metal extraction activities. Eastern European countries are increasingly investing in advanced mining technologies, including automation and equipment with enhanced safety features. However, the market is also challenged by aging infrastructure and the need for modernization in some parts of the region. Despite these challenges, Eastern Europe continues to show steady growth, driven by increased resource extraction activities and the development of new mining projects.
Key players
- Caterpillar Inc.
- Sandvik AB
- Epiroc AB
- Komatsu Ltd.
- Volvo Construction Equipment
- Liebherr Group
Competitive Analysis
The Europe Underground Mining Equipment Market is highly competitive, with key players such as Caterpillar Inc., Sandvik AB, Epiroc AB, Komatsu Ltd., Volvo Construction Equipment, and Liebherr Group leading the sector. Caterpillar Inc. remains a dominant player, known for its extensive portfolio of high-performance underground mining machines and a focus on automation and sustainability. Sandvik AB and Epiroc AB, both established in Sweden, are strong contenders with advanced technology solutions for mining equipment, including drilling, bolting, and cutting machinery. Komatsu Ltd. offers a diverse range of mining machinery, integrating automation and electrification technologies to improve operational efficiency. Volvo Construction Equipment focuses on sustainable solutions, providing electric-powered mining equipment and innovations to reduce environmental impact. Liebherr Group, with its robust engineering capabilities, continues to expand its presence in the underground mining sector, emphasizing reliability and innovative design. These companies are continually investing in R&D to maintain their competitive edge and meet evolving market demands.
Recent Developments
- In December 2023, Caterpillar demonstrated its first battery electric prototype underground mining truck to Newmont Corporation. This truck is part of Caterpillar's growing portfolio of sustainable underground solutions, including autonomous and semi Inautonomous technologies. The truck is designed to reduce carbon emissions and improve safety in underground mining operations.
- In May 2024, Sandvik secured a major order from Hindustan Zinc Limited for underground mining equipment, valued at approximately SEK 345 million. The order includes development drills, production drills, trucks, and loaders, with deliveries scheduled through the end of 2024.
- In October 2024, Epiroc received a large order for underground mining equipment, including battery In electric vehicles, from Eurasian Resources Group (ERG) in Kazakhstan. Some machines will operate driverless (tele In remotely), enhancing safety and efficiency.
- In July 2024, Komatsu completed the acquisition of GHH Group GmbH, a German manufacturer specializing in underground mining and tunneling equipment. This acquisition expands Komatsu’s offerings in loaders and articulated dump trucks for the underground market.
Market Concentration and Characteristics
The Europe Underground Mining Equipment Market is moderately concentrated, with a few dominant players holding significant market share, while numerous smaller companies contribute to the market's diversity. Major players such as Caterpillar Inc., Sandvik AB, Epiroc AB, Komatsu Ltd., and Volvo Construction Equipment lead the market, driven by their extensive product portfolios, technological innovations, and strong brand presence. These companies focus on automation, electrification, and sustainability to meet evolving industry demands and regulatory pressures. The market is characterized by continuous advancements in mining technology, with an increasing shift towards energy-efficient, automated, and environmentally-friendly solutions. Despite the dominance of key players, the presence of regional players and specialized manufacturers adds a layer of competition, especially in niche applications. As mining companies seek to improve efficiency, safety, and environmental sustainability, the market is expected to remain competitive, with ongoing investments in research and development shaping the future landscape.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Mining Technique, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe Underground Mining Equipment Market will see ongoing technological advancements, particularly in automation and electrification. These innovations will enhance operational efficiency, safety, and sustainability.
- Environmental sustainability will remain a key driver, with increasing adoption of electric-powered mining equipment and energy-efficient solutions. These technologies align with Europe’s strict environmental regulations and carbon reduction goals.
- Automation will continue to revolutionize underground mining, with more equipment being remotely controlled and operated autonomously. This shift will improve productivity and reduce the need for human intervention in hazardous environments.
- Hard rock mining, particularly in regions like Scandinavia and Eastern Europe, will experience growth due to rising demand for critical minerals. This will increase the need for specialized, high-performance underground mining equipment.
- As safety regulations tighten, mining companies will invest more in advanced safety technologies, such as collision detection systems, automated roof support, and improved ventilation solutions to ensure worker protection in underground environments.
- The use of IoT sensors and data analytics will expand, enabling real-time monitoring and predictive maintenance of mining equipment. These technologies will improve equipment uptime and reduce operational costs for mining operators.
- Europe’s growing demand for both energy and industrial minerals will drive more investments in mining exploration projects. This will further boost the demand for advanced underground mining machinery and technology.
- The competitive landscape will see further consolidation as large players acquire smaller, innovative companies to expand their technology portfolios and market reach. Strategic partnerships and mergers will be common as companies focus on strengthening their positions.
- Stringent regulations on emissions and operational safety will push mining companies to adopt advanced, clean technologies. This trend will lead to higher investments in equipment that complies with evolving legal standards.
- Emerging markets in Central and Eastern Europe, where mining industries are expanding, will present significant opportunities for equipment manufacturers. These regions will see a rise in demand for modern mining equipment as their mining infrastructure develops.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Europe Underground Mining Equipment Market in 2023 and 2032?
What are the main challenges in the Europe Underground Mining Equipment Market?
How does high initial investment affect mining companies?
What role do geological challenges play in underground mining?
How do environmental regulations impact the underground mining industry?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Underground Mining Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Underground Mining Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 6,444.71 million → 2032: USD 8,959.58 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Underground Mining Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Underground Mining Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Underground Mining Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Underground Mining Equipment Market Drivers
- 3.3 Europe Underground Mining Equipment Market Restraints & Challenges
- 3.4 Europe Underground Mining Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Underground Mining Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Underground Mining Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Underground Mining Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Underground Mining Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Underground Mining Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Underground Mining Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Underground Mining Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Underground Mining Equipment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Underground Mining Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Underground Mining Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Underground Mining Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Underground Mining Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Underground Mining Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Underground Mining Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Underground Mining Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Underground Mining Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Underground Mining Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Underground Mining Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Underground Mining Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
