
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
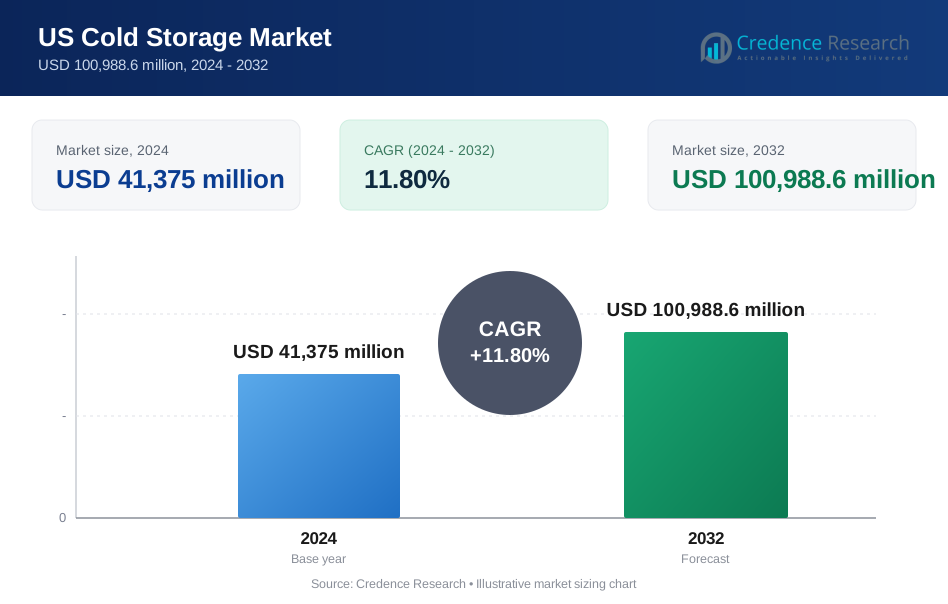
| Cold storage market Size 2023 | USD 41,375 million |
| Cold storage market, CAGR | 11.8% |
| tCold storage market Size 2032 | USD 100,988.6 million |
Market Overview:
The U.S. cold storage market is projected to grow significantly, from USD 41,375 million in 2024 to USD 100,988.6 million by 2032, reflecting a compound annual growth rate (CAGR) of 11.8%. This expansion is driven by increasing demand for temperature-controlled warehousing to support the pharmaceutical, food, and beverage industries. Cold storage facilities play a crucial role in maintaining the quality and shelf life of perishable goods, particularly as consumer preferences shift toward fresh and frozen foods. Furthermore, the COVID-19 pandemic highlighted the importance of robust cold storage infrastructure, particularly for vaccine distribution, further accelerating investments in this sector. The increasing adoption of advanced technologies, such as automation and IoT, is enhancing operational efficiency and supporting the rapid growth of the U.S. cold storage market.
Key drivers of the U.S. cold storage market include the rising demand for frozen and perishable foods, driven by changing consumer diets and increased spending on convenience foods. The growth of e-commerce, particularly in the grocery and meal delivery sectors, has intensified the need for temperature-controlled logistics. Additionally, the pharmaceutical industry relies heavily on cold storage for the distribution of temperature-sensitive products, such as vaccines and biologics. As biopharmaceuticals continue to expand, companies are investing in cold storage facilities to ensure product integrity. Environmental sustainability is also a priority, with companies investing in energy-efficient refrigeration technologies to reduce their carbon footprint and comply with increasingly stringent regulations.
Regionally, the U.S. cold storage market is concentrated in areas with high agricultural output and dense population centers, such as California, Texas, and the Midwest. California leads the market due to its significant agricultural production, especially in fruits and vegetables, which require extensive cold storage facilities. The Midwest, known for its meat and dairy production, is another key region, supported by established cold storage networks. Additionally, the Southeast is witnessing rapid growth, driven by investments in cold storage infrastructure to meet the needs of the food distribution and pharmaceutical sectors. These regional dynamics underscore the growing demand for advanced cold storage solutions across the United States, influenced by both geographic and sector-specific factors.
Market Drivers:
Growing Demand for Frozen and Perishable Foods:
The increasing demand for fresh and frozen foods is a significant driver of the U.S. cold storage market. As consumer preferences shift toward healthier options, there has been a noticeable increase in the consumption of fruits, vegetables, and plant-based foods, many of which require temperature-controlled storage. For instance, The U.S. Department of Agriculture (USDA) reports that consumption of frozen foods has risen by approximately 10% over the past five years, driven by the growing popularity of convenient, ready-to-eat meals and healthier frozen options. This trend necessitates expanded cold storage infrastructure to maintain food quality and meet consumer demand for fresh and perishable products.
Expansion of the Pharmaceutical and Biotech Sectors:
The pharmaceutical industry’s reliance on cold storage is intensifying as new biologic drugs and temperature-sensitive vaccines become more prevalent. During the COVID-19 pandemic, vaccine distribution highlighted the essential role of cold storage in maintaining the efficacy of pharmaceutical products. The U.S. Centers for Disease Control and Prevention (CDC) emphasize that temperature control is critical for storing vaccines, with specific requirements for ultra-low temperatures. As biologics and gene therapies continue to grow, the pharmaceutical sector is investing in advanced cold storage solutions to ensure product integrity, stability, and regulatory compliance. This increased demand from the pharmaceutical industry is fueling the growth of specialized cold storage facilities.
Growth of E-commerce and Online Grocery Sales:
The rise of e-commerce, especially in the grocery and meal delivery sectors, has greatly increased the need for cold storage. According to a survey by the U.S. Census Bureau, online grocery sales in the U.S. surged by over 50% between 2020 and 2022, driven by shifting consumer preferences for home delivery services. For instance, Companies like Amazon and Walmart have expanded their cold storage capabilities to support the efficient distribution of perishable groceries and frozen goods. As more consumers opt for online grocery shopping, the demand for temperature-controlled logistics networks and last-mile delivery solutions continues to expand, prompting further investment in cold storage infrastructure.
Advancements in Cold Storage Technology and Sustainability Efforts:
echnological advancements in automation and sustainable refrigeration are enhancing cold storage efficiency. Many cold storage facilities now incorporate Internet of Things (IoT) solutions to monitor temperature in real time and optimize energy usage. The U.S. Environmental Protection Agency (EPA) has reported that cold storage facilities are increasingly adopting environmentally friendly refrigerants to reduce carbon emissions. Companies are investing in solar power, efficient refrigeration systems, and energy management technologies to minimize environmental impact and reduce operational costs. These sustainability efforts, combined with enhanced technological capabilities, are driving the modernization of cold storage facilities across the United States.
Market Trends:
Automation and Smart Warehousing:
The adoption of automation in cold storage facilities is increasing, driven by the need for efficiency and temperature accuracy. Automated storage and retrieval systems (AS/RS) enable precise handling of perishable goods, minimizing temperature fluctuations and reducing human labor costs. For instance, companies like Americold have invested in robotics and automation, which allow for faster sorting and retrieval of items, improving overall throughput. Additionally, many facilities are incorporating Internet of Things (IoT) devices to monitor temperature, humidity, and inventory in real time. According to a report from the U.S. Department of Energy, IoT integration in cold storage facilities can reduce energy usage by up to 20%, reflecting the cost-saving potential of automation.
Expansion of Cold Chain Logistics for Pharmaceuticals:
With the rise of biologics and other temperature-sensitive pharmaceuticals, the demand for specialized cold chain logistics is expanding. The U.S. Food and Drug Administration (FDA) has emphasized the importance of maintaining strict temperature control for these products, which often require ultra-low-temperature environments. Companies like UPS and FedEx have expanded their cold storage facilities to cater to the pharmaceutical industry, providing storage and distribution solutions that comply with FDA regulations. This trend has grown in importance following the COVID-19 pandemic, which highlighted the critical role of cold storage in vaccine distribution and other healthcare supply chains.
Sustainability Initiatives in Cold Storage:
As environmental sustainability becomes a priority, many cold storage operators are adopting green technologies to reduce their carbon footprint. For instance, the U.S. Environmental Protection Agency (EPA) has noted that cold storage facilities are increasingly using eco-friendly refrigerants, such as ammonia and CO2, to replace traditional hydrofluorocarbon (HFC) refrigerants. Additionally, some companies are investing in solar panels and energy-efficient insulation to reduce energy consumption. For example, Lineage Logistics, a leading cold storage provider, has implemented solar power in several facilities, reducing reliance on conventional energy sources. These sustainability efforts not only benefit the environment but also improve operational efficiency and appeal to eco-conscious clients.
Growth of E-commerce and Demand for Last-Mile Delivery:
The rise of e-commerce, especially in food and grocery sectors, has intensified the need for cold storage facilities that support last-mile delivery. Online grocery sales surged during the COVID-19 pandemic, and this trend continues as consumers increasingly opt for home delivery of perishable goods. Retail giants like Amazon and Walmart are expanding their cold storage networks to facilitate same-day and next-day delivery services. According to the U.S. Census Bureau, e-commerce grocery sales have continued to grow, prompting retailers to invest in temperature-controlled logistics. This trend highlights the importance of efficient cold storage solutions that can support fast and reliable delivery, particularly in densely populated urban areas.
Market Challenges Analysis:
High Energy Costs and Environmental Regulations:
old storage facilities are highly energy-intensive, with refrigeration systems running continuously to maintain required temperatures. Rising energy costs significantly increase operational expenses, particularly in states with higher electricity rates. Additionally, stringent environmental regulations, such as those from the U.S. Environmental Protection Agency (EPA), mandate the use of low-emission refrigerants and energy-efficient equipment to minimize carbon footprints. Compliance with these regulations can be costly, especially for facilities needing to retrofit or replace existing systems to meet updated standards. While these changes support environmental goals, they add financial strain to cold storage operators, impacting their profitability.
Infrastructure and Location Challenges:
The need for well-located cold storage facilities near urban centers and key distribution hubs is crucial for efficient last-mile delivery. However, securing suitable locations can be challenging due to high real estate costs, zoning restrictions, and limited availability of large, industrial-zoned spaces in densely populated areas. The U.S. Department of Transportation has emphasized the importance of logistics infrastructure for economic growth, yet congestion in urban areas complicates access to critical cold storage hubs. Additionally, building new facilities requires significant capital investment and time, creating barriers for market entry and limiting expansion in regions with increasing demand.
Labor Shortages and Workforce Management:
Labor shortages pose a considerable challenge for the U.S. cold storage market, as these facilities rely on skilled workers to operate specialized equipment and manage inventory efficiently. The U.S. Bureau of Labor Statistics has reported a decline in available warehouse labor, driven by competition for workers and challenging work environments in cold storage facilities. High turnover rates and the need for continuous training to ensure safety in refrigerated environments further strain operational capacity. As a result, cold storage operators face increasing labor costs and must invest in automation and training programs to maintain productivity, adding to overall operational expenses.
Temperature Control and Maintenance Costs:
Maintaining consistent temperature control in cold storage facilities is essential for product safety and regulatory compliance, but it comes with significant maintenance costs. According to the U.S. Food and Drug Administration (FDA), any temperature fluctuations can compromise product quality, particularly for pharmaceuticals and perishable foods. Routine maintenance of refrigeration systems is necessary to prevent breakdowns, but these costs are high due to the complexity of the equipment and the need for specialized technicians. Facilities must also invest in backup power systems to prevent losses during power outages, further driving up operational expenses and presenting ongoing financial challenges for the industry.
Market Segmentation Analysis:
By Type:
The market is divided into refrigerated storage and frozen storage facilities. Refrigerated storage is used for products that require controlled, cool temperatures, such as dairy, fresh produce, and some pharmaceuticals. In contrast, frozen storage is essential for long-term preservation of items like meat, fish, and certain vaccines, which require sub-zero temperatures. The frozen storage segment is expanding due to the increasing demand for frozen foods and the need for temperature-controlled storage in the pharmaceutical industry, particularly for vaccines and biologics that require ultra-cold environments.
By Technology:
The cold storage market employs various technologies, including blast freezing, vapor compression, and cryogenic systems. Vapor compression systems are commonly used for general refrigeration and are valued for their efficiency and temperature control capabilities. Blast freezing is increasingly used for quick-freezing perishable items to preserve quality and extend shelf life, a critical feature for food processing and pharmaceutical sectors. Additionally, some facilities are investing in automated storage and retrieval systems (AS/RS) and Internet of Things (IoT) technology for real-time monitoring and temperature management, which enhance operational efficiency and reduce human error.
By End User:
Primary end users of cold storage facilities include the food and beverage, pharmaceutical, and healthcare industries. The food and beverage industry is the largest segment, driven by the demand for fresh and frozen foods. Cold storage also plays a critical role in the pharmaceutical and healthcare sectors, as temperature-sensitive drugs and biologics require specialized storage solutions to maintain efficacy. Retail and e-commerce companies increasingly rely on cold storage facilities to ensure the quality of perishable goods throughout the supply chain, reflecting the market’s versatility in serving diverse industry needs.
Segmentations:
By Warehouse Type
- Private
- Public
BY Temperature Type
- Chilled
- Frozen
By Application
- Fruits And Vegetables
- Dairy
- Fish Meet and Seafood
- Processed Food
- Others
Regional Analysis:
West
The West region, led by California, holds the largest share of the U.S. cold storage market, accounting for approximately 25% of total market revenue. California’s significant agricultural output, particularly in fruits, vegetables, and dairy, drives demand for cold storage facilities. The state’s prominent role in food production and export necessitates robust refrigerated and frozen storage infrastructure to preserve product quality and extend shelf life. Additionally, the West Coast is home to several major ports, such as the Port of Los Angeles, which facilitates the import and export of perishable goods. This region also emphasizes sustainability, with many cold storage facilities adopting energy-efficient technologies and eco-friendly refrigeration systems to meet state environmental regulations.
Midwest
The Midwest represents around 20% of the U.S. cold storage market, largely driven by the region’s meat and dairy production. States like Illinois, Iowa, and Wisconsin are prominent in the livestock and dairy industries, which require extensive cold storage solutions to maintain product safety and quality. The Midwest’s central location within the United States also makes it a strategic hub for food distribution across the country. Cold storage facilities in this region often incorporate advanced freezing technologies, such as blast freezing, to support meat processing and extend product shelf life. Additionally, as the Midwest’s food production and export activities expand, investments in cold storage infrastructure are expected to grow accordingly.
Northeast
The Northeast holds approximately 15% of the U.S. cold storage market share. Major metropolitan areas like New York City and Boston drive demand for cold storage, primarily due to high population density and strong consumer demand for fresh and frozen foods. The food and beverage industry is the largest user of cold storage facilities in this region, supported by a well-developed transportation network that facilitates efficient distribution. Cold storage providers in the Northeast are investing in technologies to improve operational efficiency and meet growing demand from e-commerce grocery services. Additionally, the region’s healthcare sector increasingly relies on cold storage for pharmaceuticals and other temperature-sensitive products, further supporting market growth.
Southeast
The Southeast accounts for about 20% of the market share, driven by the region’s agricultural output, which includes poultry, seafood, and produce. Florida, Georgia, and North Carolina are major contributors, supported by warm climates that make cold storage essential for preserving food quality. The Southeast has also seen increased investment in cold storage facilities to support the region’s growing food distribution and export activities. This region benefits from proximity to major ports, such as the Port of Miami, which facilitates the import of perishable goods. The Southeast is witnessing rapid growth in cold storage capacity, fueled by rising e-commerce and grocery delivery services.
Southwest The Southwest region, including states like Texas and Arizona, holds around 20% of the market share. Texas, with its expansive agricultural sector and strategic position as a trade hub, is a major player in this region. Cold storage facilities in the Southwest support a wide range of industries, from food and beverage to pharmaceuticals. Texas’ ports and highways facilitate cross-border trade with Mexico, enhancing demand for cold storage. Additionally, the Southwest is experiencing growth in temperature-controlled logistics to support the pharmaceutical sector, especially for the distribution of vaccines and biologics that require strict temperature control.
Key Player Analysis:
- Lineage Logistics
- Americold Logistics
- United States Cold Storage (USCS)
- XPO Logistics
- AGRO Merchants Group
- VersaCold Logistics Services
- Burris Logistics
- Kool Pak
- NewCold Advanced Cold Logistics
- Preferred Freezer Services
Competitive Analysis:
The U.S. cold storage market is highly competitive, dominated by key players such as Lineage Logistics, Americold Logistics, and United States Cold Storage (USCS), which collectively hold a significant portion of the market. These companies maintain extensive networks of temperature-controlled facilities across the country, catering to the food, beverage, and pharmaceutical sectors. The competitive landscape is driven by investments in advanced technologies, including automation and Internet of Things (IoT) solutions, which enhance operational efficiency, reduce energy costs, and improve inventory management. Additionally, market leaders are increasingly focused on sustainability initiatives, such as using energy-efficient refrigeration systems and eco-friendly refrigerants, to meet regulatory requirements and appeal to environmentally conscious clients. Newer entrants and regional players are also leveraging strategic partnerships to expand their presence in high-demand areas, intensifying competition. This dynamic environment pushes companies to continually innovate and optimize their cold storage solutions to retain and grow market share.
Recent Developments:
- In a strategic move to enhance its U.S. port presence and international reach, Lineage Logistics acquired Emergent Cold in 2023. This acquisition expanded Lineage's network with new facilities in major U.S. port cities like New Orleans and Houston, and it strengthened the company’s position in the Asia-Pacific region by adding locations in Australia, New Zealand, and other countries.
- In 2022, Lineage unveiled a new fully automated cold storage facility, the South East Superhub in Peterborough, which significantly expands its capacity in the region. This facility incorporates cutting-edge automation and precision cooling technology, allowing Lineage to meet high demand from both retail and foodservice clients while reducing energy consumption and enhancing operational efficiency.
- Lineage announced a $42 million expansion at its Jourdan Road facility in New Orleans, increasing the facility’s footprint to over 304,000 square feet. This development aims to boost capacity to serve key industries in the region and is expected to create 50 new jobs, supporting local economic growth and furthering Lineage’s commitment to strategic port-based cold storage.
- In 2024, Lineage began constructing a state-of-the-art automated warehouse in Hazleton, PA, designed to support the company’s growing portfolio of fully automated facilities. The facility will span 386,000 square feet and feature advanced technologies like automated layer picking and computer vision systems to enhance product receiving processes. This facility, set to open by fall 2024, is expected to support over 100 new jobs, contributing to local employment and operational efficiency.
Market Concentration & Characteristics:
The U.S. cold storage market is moderately concentrated, with major players such as Lineage Logistics, Americold Logistics, and United States Cold Storage (USCS) holding substantial market shares due to their extensive facility networks and investments in automation and sustainability. These companies dominate by leveraging advanced technologies like automated storage and retrieval systems (AS/RS) and IoT-enabled temperature monitoring, which enhance operational efficiency and ensure product integrity. High entry barriers, including significant capital investments and stringent regulatory requirements for temperature-controlled storage, restrict new market entrants, favoring established players. Additionally, the market is characterized by increasing consolidation, as leading companies expand their footprints through acquisitions to secure strategic locations near major ports and urban centers. This concentration drives continuous innovation and sustainability efforts, as key players adopt energy-efficient refrigeration systems and eco-friendly refrigerants to meet evolving environmental standards and reduce operational costs across their networks.
Report Coverage:
The research report offers an in-depth analysis based on Warehouse Type, Temperature Type, and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for temperature-controlled storage will continue as consumer preferences shift toward frozen foods.
- Growth in e-commerce, especially in grocery and meal delivery, will fuel expansion in cold storage to support last-mile delivery.
- Technological advancements, such as automation and IoT integration, will become more prevalent, improving inventory management, operational efficiency.
- Rising investments in green technology will push facilities to adopt energy-efficient refrigeration systems and eco-friendly refrigerants, aligning with sustainability goals and regulatory requirements.
- Increased consolidation and acquisitions among leading companies will drive market concentration, allowing key players to expand their facility networks and service capabilities.
- Expansion of cold chain logistics for the pharmaceutical sector, including biologics and vaccines, will boost demand for ultra-low temperature storage, particularly in centralized hubs near urban centers.
- Strategic development near major ports and urban centers will continue to grow, enabling streamlined import, export, and domestic distribution of temperature-sensitive goods.
- Investment in data-driven technologies, such as predictive analytics, will enhance operational insights, allowing companies to optimize storage capacity and minimize spoilage risks.
- Rising real estate costs and location restrictions will drive companies to innovate with multi-level cold storage facilities in dense urban areas, maximizing available space.
- Public and private partnerships will support cold storage infrastructure development, especially in underserved regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth of E-commerce and Online Grocery Sales
The surge in e-commerce, particularly in grocery and meal delivery, has intensified the need for temperature-controlled logistics and last-mile delivery solutions, prompting significant investment in cold storage infrastructure to support rapid and reliable distribution of perishable goods.
Expansion of Pharmaceutical and Biotech Sectors
The increasing prevalence of biologics, vaccines, and other temperature-sensitive pharmaceuticals requires specialized cold storage solutions, driving investments in ultra-low temperature facilities to ensure product integrity and regulatory compliance.
Technological Advancements and Automation
Adoption of automation, IoT-enabled monitoring, and advanced refrigeration technologies is improving operational efficiency, reducing energy costs, and minimizing human error, making cold storage facilities more attractive and scalable for diverse industry needs.
Rising Demand for Frozen and Perishable Foods
Shifting consumer preferences toward fresh, healthy, and convenient frozen foods are increasing the need for expanded cold storage capacity to maintain product quality and extend shelf life, especially for fruits, vegetables, and ready-to-eat meals.
Sustainability and Regulatory Compliance
Growing emphasis on environmental sustainability and stricter regulations are pushing operators to invest in energy-efficient refrigeration systems and eco-friendly refrigerants, both to reduce operational costs and to meet evolving environmental standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Cold Storage Market?
What factors are driving the growth of the U.S. Cold Storage Market?
What are some challenges faced by the U.S. Cold Storage Market?
Who are the major players in the U.S. Cold Storage Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Blast Freezing
- 1.2.2 Vapor Compression
- 1.2.3 Cryogenic Systems
- 1.2.4 Automated Storage and Retrieval Systems (AS/RS)
- 1.2.5 IoT-enabled Monitoring
- 1.3 By Application
- 1.3.1 Fruits and Vegetables
- 1.3.2 Dairy
- 1.3.3 Fish, Meat and Seafood
- 1.3.4 Processed Food
- 1.3.5 Others
- 1.4 By Warehouse Type
- 1.4.1 Private
- 1.4.2 Public
- 1.5 By Temperature Type
- 1.5.1 Chilled
- 1.5.2 Frozen
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 41,375 million → 2032: USD 100,988.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 US Cold Storage Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 US Cold Storage Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 US Cold Storage Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 US Cold Storage Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 US Cold Storage Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 US Cold Storage Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 US Cold Storage Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 US Cold Storage Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 41,375 million → 2032: USD 100,988.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 US Cold Storage Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Blast Freezing
- 12.3.7.2 Vapor Compression
- 12.3.7.3 Cryogenic Systems
- 12.3.7.4 Automated Storage and Retrieval Systems (AS/RS)
- 12.3.7.5 IoT-enabled Monitoring
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fruits and Vegetables
- 12.4.7.2 Dairy
- 12.4.7.3 Fish, Meat and Seafood
- 12.4.7.4 Processed Food
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Warehouse Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Private
- 12.5.7.2 Public
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Temperature Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Chilled
- 12.6.7.2 Frozen
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 US Cold Storage End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 US Cold Storage Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 US Cold Storage Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 US Cold Storage Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lineage Logistics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Americold Logistics
- 18.4 United States Cold Storage (USCS)
- 18.5 XPO Logistics
- 18.6 AGRO Merchants Group
- 18.7 VersaCold Logistics Services
- 18.8 Burris Logistics
- 18.9 Kool Pak
- 18.10 NewCold Advanced Cold Logistics
- 18.11 Preferred Freezer Services
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

