
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
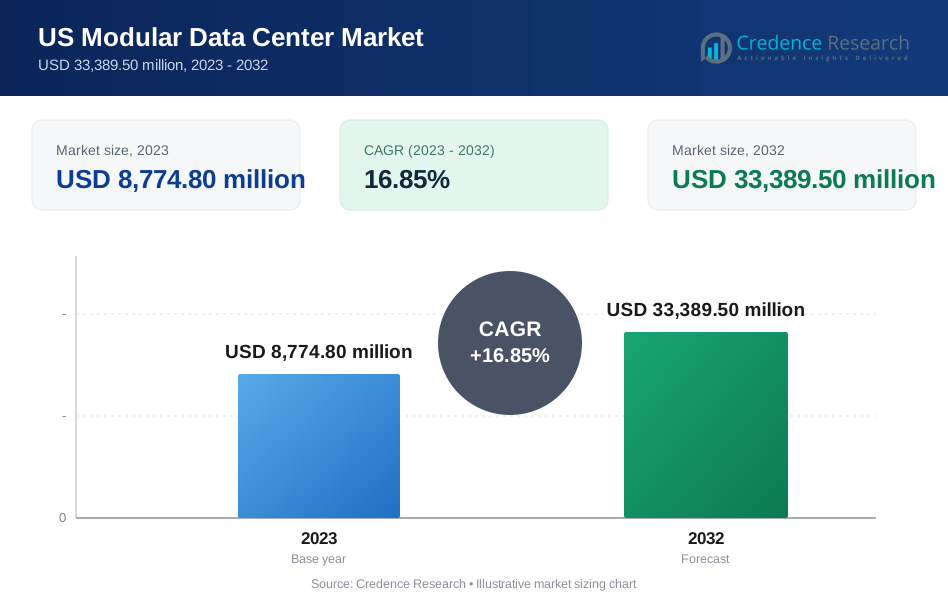
| US Modular Data Center Market Size 2024 | USD 8,774.80 million |
| US Modular Data Center Market, CAGR | 16.85% |
| US Modular Data Center Market Size 2032 | USD 33,389.50 million |
Market Overview
The US Modular Data Center Market is projected to grow from USD 8,774.80 million in 2023 to an estimated USD 33,389.50 million by 2032, with a compound annual growth rate (CAGR) of 16.85% from 2024 to 2032. This significant growth reflects the increasing demand for scalable and energy-efficient data centers, driven by the rapid expansion of cloud computing, edge computing, and the rising volume of data generation across industries.
Key drivers of the market include the heightened adoption of advanced technologies such as artificial intelligence (AI), the Internet of Things (IoT), and 5G, which require more adaptable and efficient data storage solutions. Additionally, the trend toward sustainability and energy efficiency is encouraging enterprises to invest in modular data centers, which offer flexibility, cost-effectiveness, and lower environmental impact. These data centers are also gaining traction due to their ability to support disaster recovery and business continuity efforts in critical sectors.
Geographically, the US market leads due to the presence of large technology companies, increasing digital transformation initiatives, and high demand for data center infrastructure. Key players in the market include Vertiv Group, Dell Technologies, Hewlett Packard Enterprise, IBM Corporation, and Schneider Electric. These companies are focusing on innovation and strategic partnerships to expand their market presence and meet the evolving needs of customers in various sectors, including telecommunications, IT, and healthcare.
Market Drivers
Increasing Adoption of Cloud Computing and Edge Computing
The rise of cloud computing and edge computing is one of the most prominent drivers of the modular data center market. Cloud computing enables businesses to scale their operations quickly by providing virtual storage and computing power without requiring significant upfront investments in physical infrastructure. However, as more industries adopt cloud services, the need for highly flexible and scalable data centers becomes critical.Modular data centers offer the flexibility to scale up or down based on demand, making them an ideal solution for cloud service providers and enterprises expanding their digital infrastructure. The demand for edge computing, which focuses on processing data closer to its source to reduce latency, is also pushing the need for modular data centers. These centers can be deployed in remote or urban areas, enabling quicker data processing and improving overall efficiency for applications like autonomous vehicles, smart cities, and the Internet of Things (IoT). This flexibility is key to handling the increasing volume of data generated by emerging technologies. For instance, a report by Cisco Systems predicts that global cloud data center traffic will reach 19.5 zettabytes per year by 2021, highlighting the increasing demand for flexible data center solutions. Additionally, IDC forecasts that the number of edge computing devices will grow to 55 billion by 2022, further driving the need for modular data centers in various locations.
Demand for Energy Efficiency and Sustainability
Energy efficiency and environmental sustainability are growing concerns for businesses and data center operators. Traditional data centers are highly energy-intensive, contributing to significant operational costs and environmental impact. Modular data centers, on the other hand, are designed to be more energy-efficient, offering improved power usage effectiveness (PUE) and cooling capabilities. The ability to deploy modular systems with optimized energy management ensures that data center operators can lower their carbon footprint while reducing costs associated with energy consumption.Additionally, with stringent government regulations and corporate sustainability goals, companies are actively seeking greener solutions. Modular data centers can be equipped with advanced cooling systems, energy-efficient power sources, and the use of renewable energy, making them a sustainable alternative to traditional facilities. Many organizations, particularly in the US, are adopting modular data centers as part of their overall sustainability initiatives, thus driving the market's growth.
Faster Deployment and Lower Capital Expenditure
The modular nature of these data centers allows for rapid deployment, which is crucial for organizations looking to scale their IT infrastructure in a short timeframe. Traditional data centers often require years to build and come with high upfront costs. Modular data centers, however, can be constructed and deployed within months, offering faster time-to-market capabilities.Businesses in sectors such as telecommunications, healthcare, and financial services are under constant pressure to enhance their IT infrastructure to meet growing consumer demands. Modular data centers provide a cost-effective solution, with pre-fabricated modules that can be quickly assembled, tested, and deployed at any location. This scalability reduces capital expenditures (CAPEX) since organizations can invest in smaller modules based on current needs and expand as necessary, avoiding large upfront investments. The ability to move these modular units as needed adds further appeal for companies seeking agility and flexibility in their operations.
Growing Importance of Disaster Recovery and Business Continuity
The increasing frequency of natural disasters, cyberattacks, and unexpected disruptions has made disaster recovery and business continuity top priorities for organizations. Data centers play a critical role in ensuring that business operations can continue even in the face of disruptions. Modular data centers, due to their portable and flexible design, offer an excellent solution for disaster recovery planning.In the event of a failure or disaster, modular data centers can be quickly deployed to backup sites or moved to areas less affected by the crisis. Their plug-and-play design allows for rapid deployment and integration into existing infrastructure, minimizing downtime and ensuring data integrity. Additionally, modular data centers can serve as backup facilities for mission-critical applications, reducing the risk of data loss and maintaining operational continuity. This ability to provide fast, reliable disaster recovery solutions is driving organizations in sectors like healthcare, financial services, and government to invest in modular data centers as part of their risk management strategies.
Market Trends
Integration of Advanced Technologies and Hybrid Cloud Solutions
One of the most notable trends in the US modular data center market is the increasing integration of advanced technologies such as artificial intelligence (AI), machine learning (ML), the Internet of Things (IoT), and 5G. These technologies are significantly reshaping data center requirements, leading to more sophisticated modular data center designs. The demand for real-time data processing is rising, particularly with the expansion of IoT devices and 5G networks, driving the adoption of edge computing. Modular data centers are well-suited for these applications as they can be deployed at the edge, closer to end-users, and configured to meet the specific needs of emerging technologies.Furthermore, many organizations are shifting toward hybrid cloud environments, combining public cloud services with private infrastructure to optimize their IT operations. Modular data centers provide the flexibility needed for such hybrid deployments, offering a customizable and scalable solution that can easily be integrated with cloud-based platforms. This trend is particularly important for industries like telecommunications, healthcare, and finance, where data security and regulatory compliance are critical, and organizations require a mix of on-premises and cloud solutions to meet their needs.
Focus on Energy Efficiency and Sustainable Infrastructure
Sustainability is an increasingly critical focus in the US modular data center market, as businesses face mounting pressure to reduce their carbon footprint and comply with environmental regulations. Modular data centers are designed to improve energy efficiency, offering features such as advanced cooling systems, optimized airflow, and the ability to use renewable energy sources like solar and wind power. For instance, a recent study by the Uptime Institute found that modular data centers can achieve a Power Usage Effectiveness (PUE) as low as 1.1, compared to the industry average of 1.59 for traditional data centers, demonstrating significant energy efficiency improvements. As a result, many enterprises are adopting modular data centers as part of their broader sustainability initiatives, which include reducing operational costs associated with power consumption and achieving long-term environmental goals.In addition to improved energy efficiency, there is a growing emphasis on utilizing sustainable construction materials in the development of modular data centers. The ability to relocate and repurpose these centers also contributes to their sustainability, as companies can avoid the environmental impact of building entirely new facilities when expanding or relocating their operations. This focus on energy-efficient and sustainable data centers is expected to remain a key trend as organizations prioritize eco-friendly practices and look for ways to align their IT infrastructure with sustainability goals.
Market Restraints and Challenges
High Initial Capital Expenditure and Customization Costs
While modular data centers are known for their flexibility and faster deployment, one of the key challenges the US market faces is the high initial capital expenditure (CAPEX) involved in setting up these infrastructures. Although they offer cost efficiencies in the long run, particularly in terms of operational expenses and scalability, the upfront costs can be significant, especially for small- and medium-sized enterprises (SMEs). Customization, which is often necessary to meet specific business requirements, further drives up the costs. The need for specialized designs, unique power configurations, or particular cooling technologies can elevate expenses beyond what some organizations are prepared to invest in the short term. This cost barrier may deter certain businesses from adopting modular data centers, especially those with limited IT budgets, despite the potential long-term benefits.
Challenges with Integration and Legacy Systems
Another restraint in the US modular data center market is the challenge of integrating modular solutions with legacy systems and existing IT infrastructure. Many organizations, particularly large enterprises, still rely heavily on traditional data centers that have been in place for years. Transitioning to a modular data center setup can involve complex integration efforts, requiring businesses to overhaul outdated hardware and software, which can be both time-consuming and costly. The lack of interoperability between modular data centers and older systems may lead to disruptions during migration, further complicating the transition. Moreover, concerns about the technical expertise required to manage these new systems, as well as potential downtime during the integration process, make some organizations hesitant to fully embrace modular data centers, thereby restraining market growth.
Market Segmentation Analysis
By Component
The US modular data center market is segmented by component into solutions and services. In the solutions segment, all-in-one modules offer pre-configured units that integrate IT, power, and cooling components for rapid deployment with minimal customization, ideal for organizations seeking simplicity. Individual modules provide separate IT, power, and cooling systems, giving businesses flexibility to scale and optimize efficiency based on their specific needs. IT modules focus on core computational infrastructure, including servers and storage, while power modules ensure stability through systems like UPS and PDUs, and cooling modules enhance energy efficiency and temperature control. In the services segment, design and consulting helps businesses customize their modular data center setups, while integration and deployment services ensure smooth implementation with minimal downtime. Maintenance and support services provide ongoing operations management, including routine updates and troubleshooting, ensuring continuous and efficient performance.
By Organisation Size
Large enterprises and small to medium-sized enterprises (SMEs) both play significant roles in the US modular data center market. Large enterprises, with their demand for scalable and high-performance IT infrastructure, often require customized modular solutions to manage vast amounts of data and ensure business continuity. On the other hand, SMEs are increasingly adopting modular data centers due to their cost-effectiveness and scalability. Although their initial investments may be limited by budget constraints, the flexibility of modular systems allows SMEs to scale incrementally, aligning growth with evolving business needs.
Segments
Based on Component
- Solutions
- All-in-One Modules
- Individual Modules
- IT
- Power
- Cooling
- Services
- Design and Consulting
- Integration and Deployment
- Maintenance and Support
Based on Organization Size
- Large Enterprises
- Small & Medium Enterprises (SMEs)
Based on Industry Vertical
- Banking, Financial Services, and Insurance (BFSI)
- IT & Telecom
- Government & Defense
- Healthcare
- Others
Based on Region
- North-East
- Mid-West
- West
- South
Regional Analysis
West Region (35%)
The West region holds the largest share of the US modular data center market, contributing approximately 35% of the total market revenue. This dominance is largely driven by the presence of major technology companies and cloud service providers, especially in California's Silicon Valley, which is a global hub for innovation. The region’s high concentration of IT, telecom, and technology firms fuels significant demand for scalable, energy-efficient data center solutions. The West also leads in the adoption of advanced technologies such as artificial intelligence (AI), the Internet of Things (IoT), and 5G, all of which require high-performance, low-latency data processing capabilities that modular data centers can provide. Additionally, the region’s strong focus on sustainability and energy efficiency aligns with the modular data center market's emphasis on reducing carbon footprints and optimizing energy use.
Mid-West Region (20%)
The Mid-West region also contributes 20% to the total market, driven by its growing importance as a strategic location for data center expansion. States like Ohio, Illinois, and Michigan are becoming key players due to their central location, which provides low-latency connectivity across the US. The region is also home to several manufacturing and industrial sectors, which are increasingly adopting digital technologies, further boosting the need for modular data centers. Additionally, the Mid-West has seen a rise in colocation facilities and disaster recovery centers, both of which rely heavily on the flexibility and efficiency offered by modular data centers.
Key players
- Dell Inc.
- IBM Corporation
- Schneider Electric
- Vertiv Group Corp.
- Cisco Systems, Inc.
- ZTE Corporation
- Baselayer Technology, LLC
- Eaton
- Delta Electronics, Inc.
- FiberHome
Competitive Analysis
The US modular data center market is highly competitive, with key players focusing on innovation, strategic partnerships, and expanding their product portfolios. Dell Inc., IBM Corporation, and Schneider Electric are leaders due to their extensive global presence, comprehensive solutions, and strong financial standing. Vertiv Group Corp. and Cisco Systems, Inc. leverage their expertise in IT infrastructure and network solutions to maintain a competitive edge, particularly in the growing cloud and edge computing markets. ZTE Corporation and FiberHome are strengthening their market positions through advanced technological innovations, particularly in telecom and 5G infrastructure. Companies like Eaton and Delta Electronics focus on energy-efficient solutions, addressing the increasing demand for sustainability. Baselayer Technology, LLC distinguishes itself by offering highly customizable modular data center solutions, targeting enterprises requiring flexible, scalable infrastructures. This competitive landscape fosters continuous innovation as companies seek to address evolving industry needs.
Recent Developments
- In November 2023, Dell Technologies partnered with NHN Cloud to power South Korea's new AI data center in Gwangju. The data center uses Dell PowerEdge XE9680 servers equipped with NVIDIA H100 Tensor Core GPUs, making it the first NVIDIA H100 GPU-based data center designed specifically for AI and HPC workloads in South Korea.
- In April 2024, Vertiv introduced the SmartAisle 3, a next-generation micro modular data center with AI features,. While not specific to South Korea, this product is available in Southeast Asia and could potentially be introduced to the South Korean market. The SmartAisle 3 incorporates AI functionality and self-learning features to optimize operational and energy efficiency.
- In October 2024, Eaton launched its new modular data center solution called SmartRack. Although not specifically mentioned for South Korea, this global launch could impact the South Korean market. The SmartRack modular data center combines racks, cooling, and service enclosures to withstand up to 150kW of equipment load and is designed to meet the growing demand for edge computing, machine learning, and AI.
- In September 2024, Schneider Electric deployed a new modular data center at The Pirbright Institute in the UK. While this deployment was not in South Korea, it demonstrates Schneider Electric's continued innovation in modular data center solutions, which could potentially be applied to the South Korean market in the future.
Market Concentration and Characteristics
The US modular data center market is characterized by a moderately concentrated structure, with a few key players dominating the landscape while numerous smaller firms also contribute to the market’s diversity. Companies like Dell Inc., IBM Corporation, Schneider Electric, and Vertiv Group Corp. hold significant market shares due to their strong product portfolios, extensive expertise, and global reach. The market is marked by high competition, with participants focusing on innovation, energy efficiency, and rapid deployment solutions to meet the growing demand from industries such as IT, telecommunications, and healthcare. Furthermore, the modular nature of these data centers appeals to a wide range of enterprises seeking flexibility and scalability. The emphasis on sustainability, cost-effectiveness, and quick deployment times continues to shape the market’s characteristics, driving growth and differentiation among competitors.
Report Coverage
The research report offers an in-depth analysis based on Component, Organisation Size, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The US modular data center market is expected to continue its robust growth, driven by increasing demand for scalable, efficient, and cost-effective data infrastructure solutions.
- As cloud computing and edge computing become more prevalent, modular data centers will play a critical role in supporting decentralized data processing and reducing latency.
- The growing integration of artificial intelligence (AI) and the Internet of Things (IoT) will drive the need for modular data centers that can handle vast amounts of real-time data processing at the edge.
- Sustainability will remain a key focus, with modular data centers increasingly designed to optimize energy efficiency, reduce operational costs, and meet environmental regulations.
- The trend toward hybrid cloud environments will continue to grow, with modular data centers providing flexible, on-premise solutions that complement cloud-based services.
- The importance of business continuity and disaster recovery will boost the demand for modular data centers, which offer fast deployment and portability in critical situations.
- Innovations in cooling technologies will be a major focus, with modular data centers incorporating advanced systems to manage heat more efficiently and reduce power consumption.
- Small and medium-sized enterprises (SMEs) will increasingly invest in modular data centers as they seek affordable, scalable solutions that can grow with their business needs.
- Industries such as healthcare, retail, and manufacturing will adopt modular data centers to meet the growing demands of digital transformation and data-driven applications.
- As digital infrastructure expands, more regions across the US, particularly in the South and Mid-West, will see an increase in modular data center deployments, driven by lower operating costs and strategic advantages.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the US modular data center market in 2023 and 2032, and what is its CAGR?
What are the key drivers of growth in the US modular data center market?
Why are modular data centers considered energy-efficient?
What industries are driving the demand for modular data centers?
How does the modular design contribute to faster deployment?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 US Modular Data Center Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global US Modular Data Center Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 8,774.80 million → 2032: USD 33,389.50 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 US Modular Data Center Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. US Modular Data Center Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 US Modular Data Center Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 US Modular Data Center Market Drivers
- 3.3 US Modular Data Center Market Restraints & Challenges
- 3.4 US Modular Data Center Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 US Modular Data Center Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 US Modular Data Center Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, US Modular Data Center category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 US Modular Data Center Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. US Modular Data Center Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the US Modular Data Center market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 US Modular Data Center Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 US Modular Data Center Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 US Modular Data Center Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in US Modular Data Center (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New US Modular Data Center Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global US Modular Data Center Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America US Modular Data Center Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe US Modular Data Center Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific US Modular Data Center Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America US Modular Data Center Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East US Modular Data Center Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa US Modular Data Center Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. US Modular Data Center Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
