
Market Overview
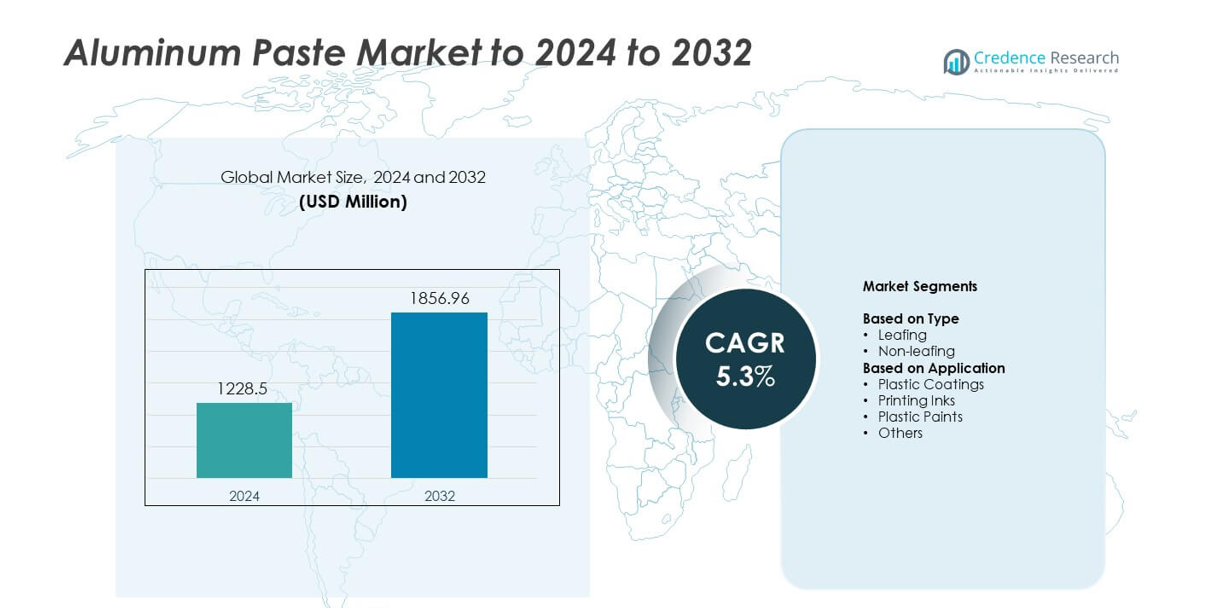
Aluminum Paste Market size was valued USD 1228.5 million in 2024 and is anticipated to reach USD 1856.96 million by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aluminum Paste Market Size 2024 | USD 1228.5 million |
| Aluminum Paste Market, CAGR | 5.3% |
| Aluminum Paste Market Size 2032 | USD 1856.96 million |
The Aluminum Paste Market includes leading companies such as Sun Chemical Corporation, Zhangqiu Metallic Pigment Co., Ltd., Alcoa Corporation, Carl Schlenk AG, Toyo Aluminium, ECKART GmbH, Silberline Manufacturing Co., Inc., and Asahi Kasei Corporation. These players compete through advanced metallic pigment technologies, improved dispersion quality, and expanded production capacity to meet rising demand across automotive, electronics, packaging, and industrial coatings. Asia Pacific led the market in 2024 with about 36% share due to strong manufacturing activity, while Europe followed with nearly 31% share driven by high-performance coating adoption. North America accounted for around 28% share, supported by automotive refinishing and industrial demand.
Market Insights
- The Aluminum Paste Market reached USD 1228.5 million in 2024 and is projected to hit USD 1856.96 million by 2032, growing at a CAGR of 5.3%.
- Demand grows due to rising use of metallic coatings in automotive and industrial sectors, with leafing grades holding about 57% share.
- Trends include expansion of eco-friendly, low-VOC formulations and increasing adoption of high-purity pigments for premium finishes in electronics and packaging.
- Competition intensifies as major players invest in advanced dispersion technologies, high-brightness grades, and regional production to reduce supply gaps.
- Asia Pacific leads the market with around 36% share, followed by Europe at 31% and North America at 28%, while plastic coatings remain the dominant application with nearly 42% share.
Market Segmentation Analysis:
By Type
Leafing aluminum paste held the dominant position in 2024 with about 57% share. Leafing grades formed a reflective layer on the surface, which improved brightness and metallic appearance in coatings. Strong use in automotive basecoats, industrial finishes, and decorative paints supported higher demand. The segment also benefited from growth in premium coatings where uniform sparkle and high opacity were required. Non-leafing grades expanded at a steady pace due to rising adoption in printing inks, plastics, and applications that required stronger adhesion and deeper pigment integration.
- For instance, the Sunrise Group (including Hefei Sunrise) operates multiple aluminum pigment facilities across four production bases, with a total annual capacity of approximately 20,000 metric tons for various paste, powder, and pelletized aluminum pigment products.
By Application
Plastic coatings led the application segment in 2024 with nearly 42% share. This category grew due to rising use in consumer electronics housings, automotive interior parts, and decorative plastic components. Manufacturers preferred aluminum paste in these coatings because it delivered strong metallic effects, smooth dispersion, and high durability. Printing inks gained wider use in packaging and label designs, while plastic paints and other uses increased with demand for metallic finishes in appliances, toys, and industrial goods.
- For instance, PPG opened a waterborne automotive coatings plant in Thailand designed for 2,000 tons of production annually, targeting high-performance coatings for metal and plastic vehicle parts.
Key Growth Drivers
Rising Demand for Metallic Automotive and Industrial Coatings
Growing use of metallic finishes in automotive and industrial sectors drives steady consumption of aluminum paste. Automakers use these pigments to enhance surface gloss, depth, and reflective appeal in both exterior and interior coatings. Industrial machinery and equipment makers also adopt metallic coatings to improve product appearance and surface durability. Expanding vehicle production in Asia-Pacific and the shift toward premium finishes support higher demand. Strong use in powder coatings and water-based systems further boosts the driver as manufacturers focus on durable and eco-friendly finishes.
- For instance, BASF Coatings expanded its Jiangmen site in South China so that automotive refinish coatings capacity reached 30,000 metric tons per year, directly supporting growing vehicle and equipment repaint volumes.
Expanding Use in Printing Inks and Packaging Applications
The packaging industry uses aluminum paste to achieve metallic effects in labels, flexible packaging, and decorative prints. Brand owners seek high-impact visual designs to improve product visibility on shelves, which increases demand for metallic inks. Growth in consumer goods, cosmetics, and beverage packaging enhances this trend. Digital and gravure printing workflows also integrate aluminum pigments to meet the rising need for fine dispersion and print clarity. The shift toward premium packaging and wider adoption of special-effect inks strengthens this driver across global markets.
- For instance, Sun Chemical increased perylene pigment output at its Ludwigshafen site by up to 200 metric tons of additional finished goods and intermediates, strengthening supply for high-impact packaging inks.
Growing Application in Plastics and Consumer Electronics
Manufacturers use aluminum paste in plastics to deliver glossy, metallic, and uniform finishes for consumer electronics, appliances, toys, and interior automotive components. Rising production of smartphones, wearables, and smart appliances expands the need for high-quality coated plastics. Aluminum paste supports improved heat resistance and color stability, which boosts adoption in high-performance plastic parts. Increased demand for lightweight components in automotive and electronics further accelerates usage. The rapid growth of decorative and functional plastic coatings makes this one of the key growth drivers for the market.
Key Trends & Opportunities
Shift Toward Eco-Friendly and Low-VOC Coating Formulations
Environmental regulations push coating producers to adopt water-based and low-VOC systems. Aluminum paste manufacturers develop improved dispersions and surface treatments to maintain brightness and stability in these formulations. Growing focus on sustainable manufacturing practices accelerates this trend as industries replace solvent-heavy coatings. Regulatory compliance in Europe and North America strengthens the opportunity for eco-designed metallic pigments. Expansion of green buildings and low-emission automotive coatings further supports demand for advanced, eco-aligned aluminum pastes.
- For instance, AkzoNobel’s Guangzhou decorative paints plant increased water-based capacity from 88 million liters to 140 million liters per year, converting the site to exclusively water-based production.
Advancements in High-Purity and Specialized Aluminum Pigments
Producers invest in high-purity grades that offer controlled particle size, enhanced brightness, and stronger orientation. These pigments support premium automotive coatings, electronics casings, and specialized printing applications. Innovation in encapsulation technology improves corrosion resistance and chemical stability, creating new opportunities in harsh-environment applications. Demand for brighter metallic effects in luxury goods and high-end consumer products also drives this trend. Rapid development of customized pigment formulations enables broader use across emerging industrial segments.
- For instance, According to a 2011 report, Ruxing Technology had an annual production capacity of 8,000 tons for aluminum paste, with a sales volume of approximately 3,000 tons in 2010.
Growing Demand from Smart Devices and Lifestyle Products
The rise of smart home devices, personal gadgets, and premium appliances increases need for metallic-coated plastic components. Consumers prefer sleek and modern finishes, creating opportunities for aluminum paste producers to supply advanced coating solutions. Expansion of lifestyle-driven product categories such as headphones, wearables, and gaming accessories supports this trend. Manufacturers focus on achieving consistent metallic effects on complex plastic geometries, which boosts adoption of engineered aluminum pigments across these fast-growing markets.
Key Challenges
Volatility in Aluminum Prices and Raw Material Availability
Fluctuations in aluminum prices affect production stability and cost planning for manufacturers. Supply disruptions, energy price shifts, and geopolitical conditions increase volatility in raw material markets. This pressure reduces margins for producers and forces frequent pricing adjustments across supply chains. Smaller manufacturers face greater challenges in maintaining stable sourcing. Variability in availability can also slow production schedules, making this one of the key challenges restraining market growth.
Stringent Regulatory Requirements for Safety and Environmental Compliance
Regulatory bodies enforce strict guidelines on emissions, chemical handling, and worker safety in pigment production. Meeting these standards requires investments in advanced processing equipment and cleaner production technologies. Compliance increases operational costs and lengthens development timelines for new formulations. Restrictions on hazardous substances also limit certain coating uses, especially in highly regulated regions. Manufacturers must balance performance demands with evolving rules, making regulatory compliance a key challenge for long-term market expansion.
Regional Analysis
North America
North America held about 28% share in 2024 due to strong consumption in automotive coatings, industrial machinery, and packaging applications. Demand rose as manufacturers focused on high-quality metallic finishes and durable coating systems. Growth in electric vehicle production and rising investments in advanced printing technologies further supported regional adoption. The United States remained the primary contributor, driven by well-established automotive and industrial sectors. Canada saw stable use in construction and appliances, while Mexico expanded demand through increasing manufacturing activity. The region continued to favor high-performance aluminum pastes with improved brightness and dispersion.
Europe
Europe accounted for nearly 31% share in 2024, supported by strong use in automotive coatings, luxury packaging, and industrial paints. Strict environmental rules encouraged the shift toward low-VOC and water-based formulations, boosting demand for engineered aluminum pastes. Germany, France, and Italy led consumption due to their large automotive and industrial bases. The region also saw growing adoption in decorative plastic components for consumer goods. Rising investment in energy-efficient buildings and advanced coating technologies helped sustain steady demand. Europe remained a key market for high-purity and specialized pigment grades.
Asia Pacific
Asia Pacific dominated the global market with about 36% share in 2024. Rapid industrialization, strong automotive production, and expanding electronics manufacturing drove significant consumption. China, Japan, South Korea, and India accounted for major demand due to large coating and plastic processing industries. Growth in packaging, appliances, and consumer electronics increased the use of metallic finishes. Rising construction activity and demand for decorative paints further supported the region. Asia Pacific continued to attract major producers due to competitive manufacturing costs and large-scale industrial output.
Latin America
Latin America held roughly 3% share in 2024, supported by moderate demand from automotive refinish, packaging, and industrial coatings. Brazil and Mexico led regional consumption due to their expanding manufacturing sectors. Growth in consumer goods and flexible packaging increased use of aluminum-based pigments. Infrastructure development and rising adoption of decorative paints added further support. However, economic fluctuations and limited local production capacity slowed broader expansion. The region relied heavily on imports of high-quality aluminum paste to meet industry needs.
Middle East and Africa
Middle East and Africa accounted for nearly 2% share in 2024, driven by industrial coatings, construction paints, and packaging applications. Gulf countries showed rising demand due to ongoing construction projects and increased use of metallic architectural coatings. South Africa contributed steady consumption through automotive refinish and consumer goods packaging. Limited regional manufacturing capacity kept reliance on imported products high. Adoption grew as industries demanded better durability, corrosion resistance, and metallic effects in coating systems. Steady infrastructure growth continued to support regional market expansion.
Market Segmentations:
By Type
- Leafing
- Non-leafing
By Application
- Plastic Coatings
- Printing Inks
- Plastic Paints
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Aluminum Paste Market features major players such as Sun Chemical Corporation, Zhangqiu Metallic Pigment Co., Ltd., Alcoa Corporation, Carl Schlenk AG, Toyo Aluminium, ECKART GmbH, Silberline Manufacturing Co., Inc., and Asahi Kasei Corporation. These companies compete through advancements in pigment dispersion, particle size control, and high-purity grades designed for premium coatings and printing applications. Producers focus on improving brightness, orientation, and stability to meet rising demand from automotive, electronics, and packaging industries. Many manufacturers expand regional production capabilities to reduce lead times and serve fast-growing markets in Asia Pacific. Strong investments in eco-friendly and low-VOC formulations align with global environmental rules, while continuous R&D supports specialized applications in plastics and industrial coatings. Competitive strategies also include supply chain optimization, product customization, and collaborative partnerships with coating formulators. As industries shift toward sustainable and high-performance finishes, leading producers strengthen technical capabilities to maintain a competitive edge.
Key Player Analysis
- Sun Chemical Corporation
- Zhangqiu Metallic Pigment Co., Ltd.
- Alcoa Corporation
- Carl Schlenk AG
- Toyo Aluminium
- ECKART GmbH
- Silberline Manufacturing Co., Inc.
- Asahi Kasei Corporation
Recent Developments
- In 2025, ECKART GmbH launched several innovative aluminium pigment pastes at the European Coatings Show (ECS), including STAPA® HD metallic pigment pastes optimized for industrial and automotive coatings with high covering power and brilliance, as well as SILVERSHINE Hydro Platinum water-based pastes for radar-transparent silver effects in autonomous driving applications.
- In 2025, Alcoa Corporation entered into a joint venture agreement with IGNIS EQT, acquiring a 75% stake in the San Ciprián production site to expand aluminum product output
- In 2024, Toyo Aluminium K.K. Introduced a new series of environmentally friendly, water-based aluminum paste products for automotive coatings, focusing on low volatile organic compounds (VOCs).
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow as demand rises for metallic automotive and industrial coatings.
- Adoption of eco-friendly, low-VOC coating systems will increase the use of advanced aluminum pastes.
- Manufacturers will expand high-purity and specialized pigment grades for premium finishes.
- Growth in consumer electronics and coated plastics will drive steady demand.
- Packaging applications will rise as brands seek stronger visual impact with metallic inks.
- Asia Pacific will remain the leading production and consumption center for the market.
- Innovation in encapsulation technology will improve durability and chemical resistance.
- Automotive electric models will push higher use of lightweight components with metallic coatings.
- Increasing construction activity will support demand for decorative and architectural coatings.
- Producers will focus on sustainable production processes to meet tightening global regulations.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Metallic Automotive and Industrial Coatings
Automotive and industrial sectors increasingly use aluminum paste for metallic finishes that enhance gloss, durability, and visual appeal. Expanding vehicle production and the shift toward premium coatings, especially in Asia Pacific, are driving higher consumption.
Expansion of Eco-Friendly and Low-VOC Formulations
Stricter environmental regulations are pushing manufacturers to develop water-based and low-VOC aluminum pastes. This shift supports market growth as industries seek sustainable solutions without compromising on metallic effect and performance.
Rising Demand in Packaging and Printing Inks
Brand owners and packaging converters are adopting aluminum paste to achieve high-impact metallic effects in labels, flexible packaging, and decorative prints. The trend toward premium packaging and special-effect inks is boosting demand in this segment.
Increased Use in Plastics and Consumer Electronics
Manufacturers of consumer electronics, appliances, and automotive interior components are using aluminum paste to deliver glossy, metallic finishes and improved heat resistance. The proliferation of smart devices and lifestyle products is accelerating this application.
Advancements in High-Purity and Specialized Pigments
Ongoing innovation in particle size control, encapsulation, and high-purity grades enables aluminum paste to meet the needs of premium automotive, electronics, and harsh-environment applications, opening new market opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Aluminum Paste Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Aluminum Paste Market projected to grow between 2025 and 2032?
What is the major growth driving factors for global Aluminum Paste market?
What are the primary factors fueling the growth of the Aluminum Paste Market?
Who are the leading companies in the Aluminum Paste Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Leafing
- 1.2.2 Non-leafing
- 1.3 By Application
- 1.3.1 Plastic Coatings
- 1.3.2 Printing Inks
- 1.3.3 Plastic Paints
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1228.5 million → 2032: USD 1856.96 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aluminum Paste Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aluminum Paste Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aluminum Paste Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aluminum Paste Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aluminum Paste Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aluminum Paste Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aluminum Paste Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aluminum Paste Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1228.5 million → 2032: USD 1856.96 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aluminum Paste Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Leafing
- 12.3.7.2 Non-leafing
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plastic Coatings
- 12.4.7.2 Printing Inks
- 12.4.7.3 Plastic Paints
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aluminum Paste End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aluminum Paste Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aluminum Paste Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aluminum Paste Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sun Chemical Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Zhangqiu Metallic Pigment Co., Ltd.
- 18.4 Alcoa Corporation
- 18.5 Carl Schlenk AG
- 18.6 Toyo Aluminium
- 18.7 ECKART GmbH
- 18.8 Silberline Manufacturing Co., Inc.
- 18.9 Asahi Kasei Corporation
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

