
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
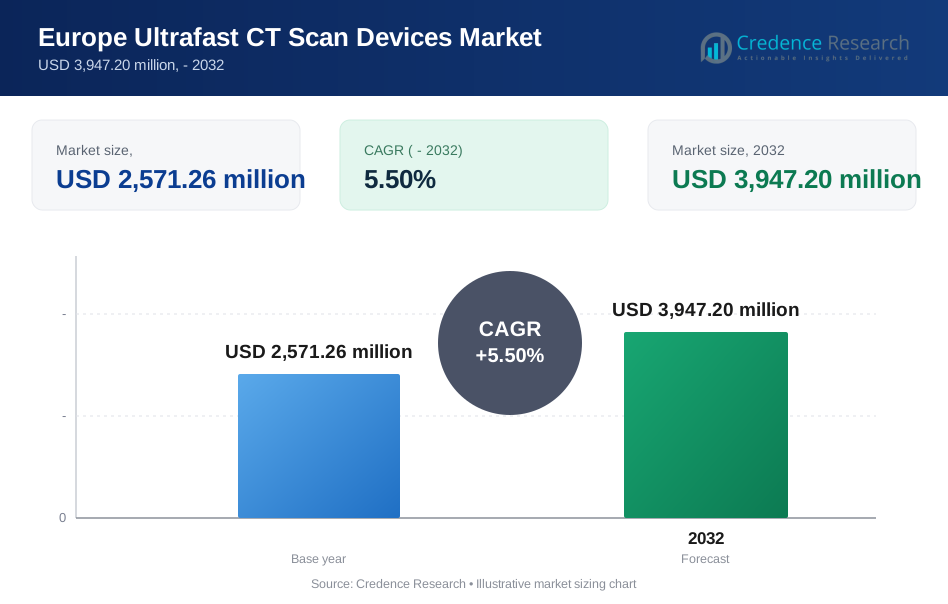
| Europe Ultrafast CT Scan Devices Market Size 2024 | USD2,571.26 million |
| Europe Ultrafast CT Scan Devices Market, CAGR | 5.50% |
| Europe Ultrafast CT Scan Devices Market Size 2032 | USD3,947.20 million |
Market Overview
The Europe Ultrafast CT Scan Devices Market is projected to grow from USD2,571.26 million in 2024 to an estimated USD3,947.20 million by 2032, with a compound annual growth rate (CAGR) 5.50% from 2025 to 2032. This growth reflects increasing adoption of advanced imaging technologies in diagnostic healthcare across the region.
Key drivers shaping this market include the rising incidence of cardiovascular and oncological conditions that require rapid and detailed imaging. Additionally, technological advancements such as AI-integrated CT platforms, low-dose imaging solutions, and enhanced data processing capabilities are pushing demand across both public and private healthcare institutions. The trend toward value-based healthcare and early disease detection is also reinforcing the shift to ultrafast CT solutions, as they offer superior time efficiency and diagnostic accuracy. The market is also witnessing a growing trend of public-private partnerships and government investments aimed at upgrading diagnostic infrastructure.
Geographically, Western Europe holds the largest share of the market, led by countries such as Germany, France, and the UK due to their well-established healthcare systems and high healthcare spending. Key players operating in the Europe Ultrafast CT Scan Devices Market include Siemens Healthineers, GE HealthCare, Philips Healthcare, and Canon Medical Systems, all of which continue to invest in R&D and regional expansion strategies.
Market Insights
- The Europe Ultrafast CT Scan Devices Market is projected to grow significantly, reaching USD 3,947.20 million by 2032, driven by increasing adoption of advanced imaging technologies and innovations in scan speed.
- The Global Ultrafast CT Scan Devices Market is projected to grow from USD 9,765.51 million in 2024 to an estimated USD 15,858.58 million by 2032, with a compound annual growth rate (CAGR) of 6.25% from 2025 to 2032.
- Key drivers include the rising prevalence of chronic diseases like cardiovascular conditions and cancer, creating a demand for rapid, high-resolution diagnostic imaging.
- AI integration, low-dose imaging solutions, and faster scanning capabilities are pushing the demand for ultrafast CT devices across healthcare institutions, improving diagnostic accuracy and efficiency.
- The growing aging population in Europe is contributing to a higher incidence of diseases that require advanced diagnostic solutions, thus increasing the need for ultrafast CT scan systems.
- The high cost of acquisition and maintenance of ultrafast CT devices remains a challenge, particularly for smaller healthcare facilities with limited budgets.
- Stringent regulatory standards and compliance requirements in Europe can delay the market entry of new CT technologies, slowing overall market growth.
- Western Europe holds the largest market share due to advanced healthcare systems in countries like Germany, France, and the UK, while Eastern Europe and Nordic countries are experiencing increased adoption.
Report Scope
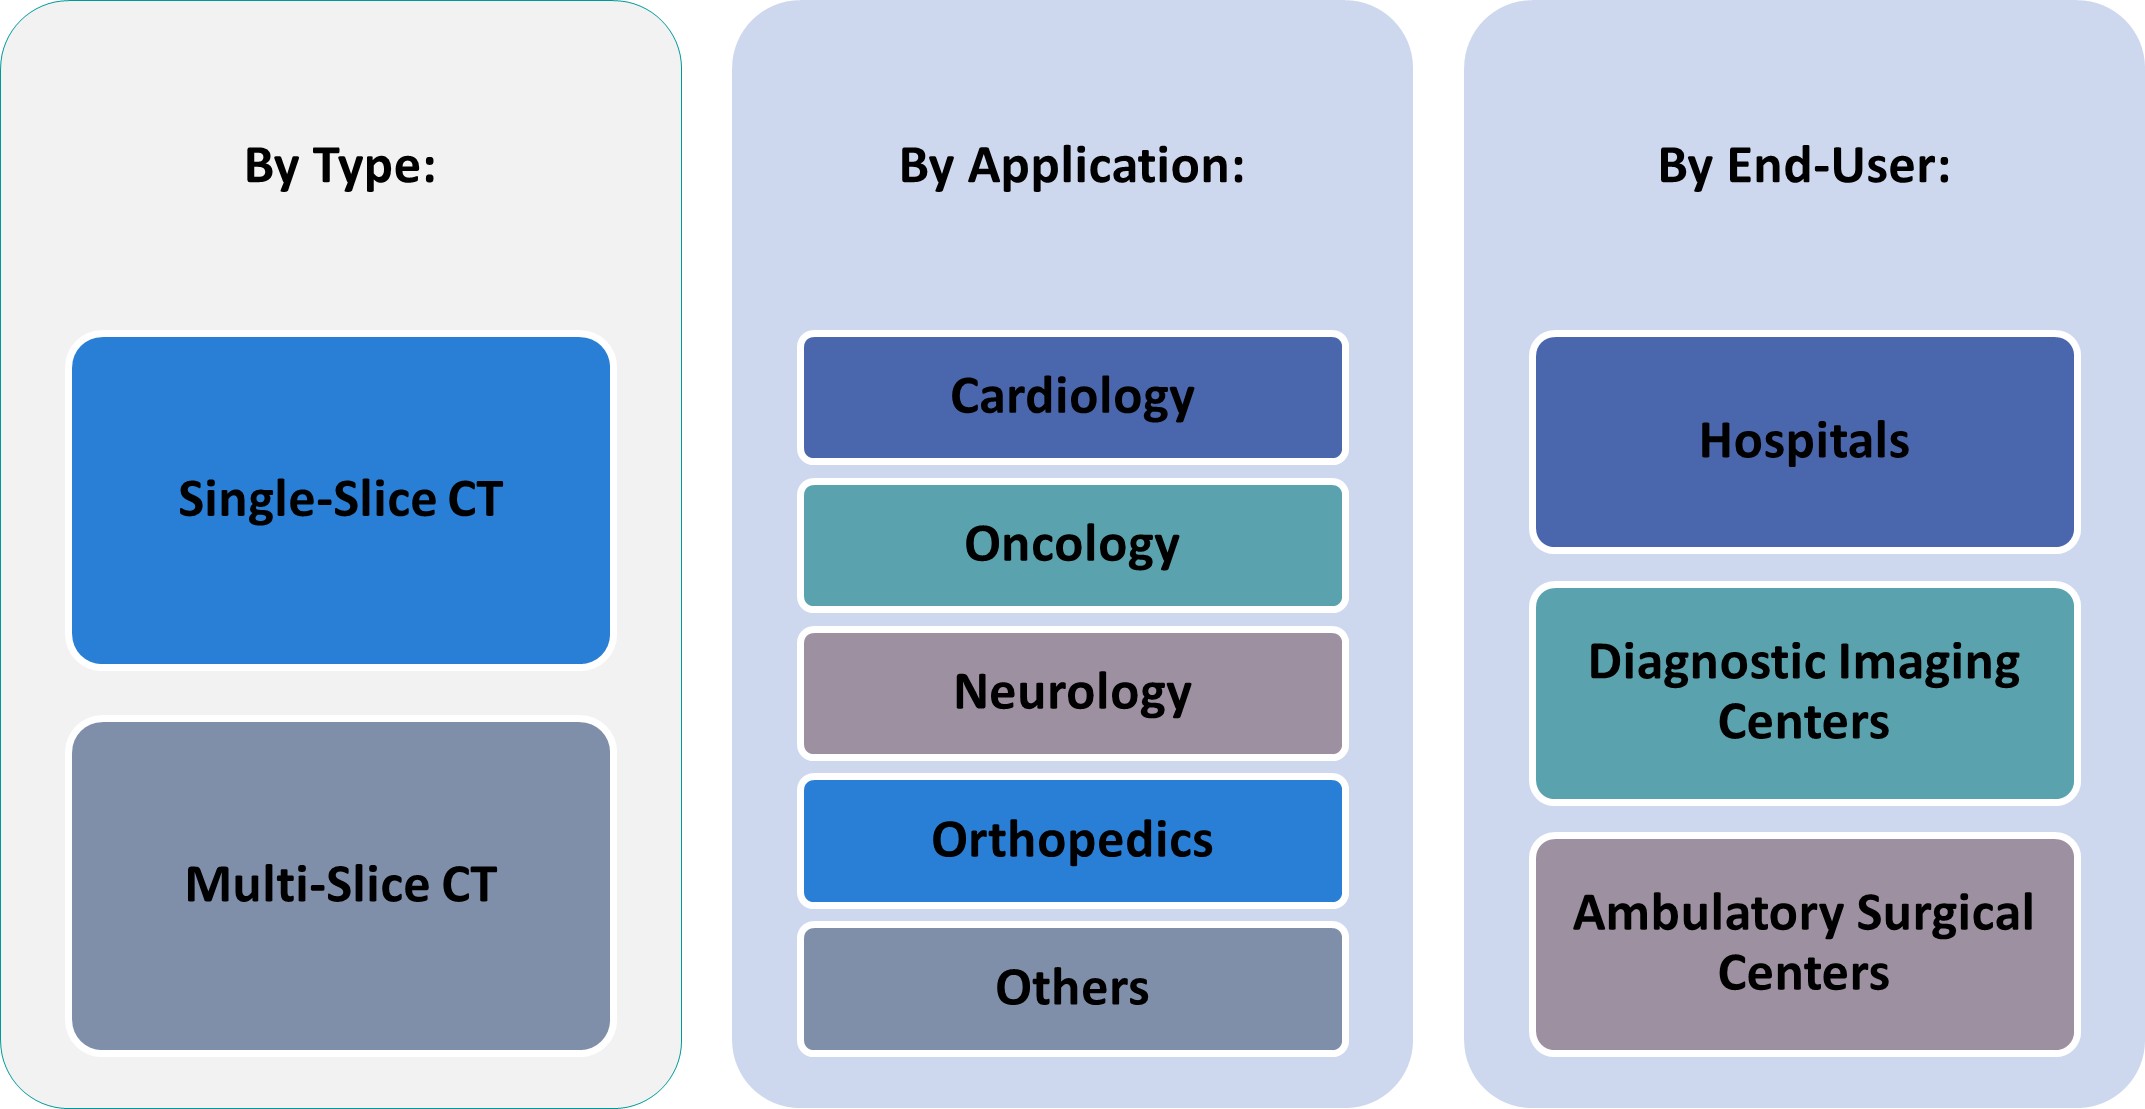
This report segments the Europe Ultrafast CT Scan Devices Market as follows:
Market Drivers
Rising Prevalence of Chronic Diseases and Aging Population
The Europe Ultrafast CT Scan Devices Market is strongly driven by the growing prevalence of chronic diseases such as cardiovascular disorders, cancer, neurological conditions, and pulmonary diseases. According to the European Society of Cardiology, cardiovascular diseases remain the leading cause of mortality in Europe, accounting for 45% of all deaths. Early detection and accurate diagnosis are critical in managing these conditions, which has escalated the demand for faster, high-resolution imaging technologies like ultrafast CT systems. Furthermore, Europe's aging population significantly contributes to market growth. Nearly 21% of the European population was aged 65 or older in 2023, a proportion expected to rise sharply in the coming decades. Elderly individuals are at a higher risk of chronic ailments, necessitating frequent and sophisticated diagnostic imaging. Ultrafast CT devices, for instance, allow healthcare providers to perform rapid and detailed assessments, leading to quicker clinical decision-making and enhanced patient care. The integration of ultrafast CT devices into routine diagnostic workflows supports preventive healthcare models, reducing hospital readmissions and optimizing treatment outcomes, thereby sustaining market expansion.
Technological Advancements and Integration of Artificial Intelligence
Technological innovations play a pivotal role in propelling the Europe Ultrafast CT Scan Devices Market forward. The integration of Artificial Intelligence (AI) and machine learning algorithms into ultrafast CT systems has revolutionized the field of diagnostic imaging. AI enhances image reconstruction, automates image analysis, and supports faster interpretation, thereby increasing diagnostic confidence while reducing the workload for radiologists. For instance, companies like Siemens Healthineers and GE HealthCare are leading developments by launching AI-driven CT solutions capable of improving workflow efficiency, minimizing scan times, and optimizing radiation dosage without compromising image quality. Moreover, advancements such as spectral imaging, photon-counting detectors, and dual-energy CT technology are further refining diagnostic capabilities by providing more detailed tissue characterization and functional information. These innovations not only increase clinical application versatility but also expand the use of ultrafast CT beyond conventional imaging to areas like oncology, cardiology, and emergency medicine. The emphasis on reducing radiation exposure while maintaining image precision continues to drive the adoption of these next-generation systems across European healthcare facilities, especially as regulations for patient safety tighten.
Growing Emphasis on Value-Based Healthcare and Early Diagnosis
The shift toward value-based healthcare models across Europe has significantly boosted the demand for technologies that enhance patient outcomes while maintaining cost-efficiency. Ultrafast CT scan devices align well with these priorities by enabling quicker diagnosis, reducing the length of hospital stays, and lowering the overall cost of treatment. As healthcare systems transition from volume-based to outcome-based frameworks, the focus on early and accurate diagnosis to prevent disease progression becomes critical. Ultrafast CT's ability to capture high-resolution images in fractions of a second supports early detection programs for life-threatening conditions such as stroke, cardiac arrest, and cancer. Additionally, emergency departments and trauma centers benefit immensely from these devices, as rapid diagnostics can be lifesaving in critical situations. Reimbursement frameworks in countries like Germany, France, and the UK increasingly favor the use of advanced diagnostic technologies that contribute to better clinical outcomes and operational efficiency. This policy environment encourages hospitals and diagnostic centers to invest in ultrafast CT systems, creating a favorable growth trajectory for the market.
Government Initiatives and Healthcare Infrastructure Modernization
Government initiatives to upgrade healthcare infrastructure and improve diagnostic capabilities are key drivers of the Europe Ultrafast CT Scan Devices Market. European governments have made significant investments in healthcare modernization projects, particularly in the post-pandemic recovery phase, where enhancing diagnostic readiness has become a strategic priority. For instance, funding programs under the European Union's Recovery and Resilience Facility (RRF) have allocated substantial resources toward digital health transformation, including upgrading imaging equipment across public hospitals. Additionally, initiatives aimed at reducing diagnostic waiting times and improving access to cutting-edge technologies in rural and underserved areas further boost the adoption of ultrafast CT devices. Collaborations between public health systems and private players also contribute to equipment renewal cycles, leading to increased installations of advanced CT systems. In countries like Italy and Spain, national healthcare reforms emphasize investments in preventive care and diagnostic innovation, positioning ultrafast CT devices as essential tools for achieving broader public health objectives. The continuous policy focus on quality care delivery, patient safety, and equitable access to high-performance diagnostic tools strongly supports the market's sustained growth.
Market Trends
Integration of Artificial Intelligence and Machine Learning
The integration of Artificial Intelligence (AI) and Machine Learning (ML) into ultrafast CT scan devices is a defining trend in the Europe market. AI-driven CT systems are transforming diagnostic imaging by automating complex processes such as image acquisition, reconstruction, and analysis. For instance, Siemens Healthineers has developed AI-powered CT platforms capable of processing up to 1,500 images daily, significantly enhancing workflow efficiency and diagnostic accuracy. These systems enable radiologists to detect abnormalities with greater precision and speed, leading to faster and more accurate clinical decisions. Furthermore, AI applications help optimize scan parameters, resulting in reduced radiation exposure while maintaining diagnostic integrity. The demand for AI-enabled ultrafast CT scanners is growing across tertiary care hospitals and specialty diagnostic centers, driven by a rising focus on precision medicine and personalized healthcare solutions. Vendors are increasingly collaborating with technology companies to introduce innovative features like automated organ segmentation, lesion detection, and disease progression tracking. As AI continues to evolve, its deeper integration into ultrafast CT devices will play a pivotal role in enhancing diagnostic capabilities, improving patient outcomes, and driving operational efficiencies across healthcare facilities.
Advancements in Low-Dose Imaging Technologies
Another significant trend shaping the Europe Ultrafast CT Scan Devices Market is the rapid advancement of low-dose imaging technologies. Concerns surrounding patient radiation exposure have driven manufacturers to develop CT systems that deliver high-quality images while minimizing radiation doses. For instance, Canon Medical Systems has introduced low-dose CT platforms equipped with advanced iterative reconstruction algorithms and spectral imaging capabilities, ensuring optimal image quality with minimal radiation exposure. These low-dose innovations are particularly crucial in pediatric imaging, oncology screenings, and routine health checks where repeated scans are necessary. Regulatory bodies in Europe, such as the European Commission, are also implementing stricter guidelines to limit radiation exposure, further encouraging healthcare providers to adopt advanced low-dose CT technologies. The growing awareness among patients about radiation safety is influencing hospitals and diagnostic centers to prefer ultrafast CT systems equipped with dose-reduction capabilities. Additionally, healthcare facilities are investing in staff training and certification programs focused on radiation protection practices. This trend is expected to persist as technological advancements continue to evolve, making ultrafast CT devices safer, more efficient, and more patient-friendly across a wide range of clinical applications.
Growing Adoption of Mobile and Portable CT Solutions
The growing adoption of mobile and portable CT scan solutions represents a key trend in the Europe Ultrafast CT Scan Devices Market. Healthcare systems across Europe are increasingly prioritizing accessibility and flexibility in diagnostic imaging, particularly in critical care settings, emergency departments, and rural healthcare facilities. Portable ultrafast CT units allow clinicians to perform high-speed, high-quality imaging at the point of care, reducing the need to transfer critically ill patients and expediting diagnostic workflows. Companies like Siemens Healthineers are pioneering the development of compact CT systems designed for use in intensive care units (ICUs), ambulances, and battlefield medical scenarios. The COVID-19 pandemic highlighted the necessity for mobile imaging solutions, leading to sustained interest and investment in portable CT technologies. European governments and health authorities are supporting initiatives aimed at strengthening healthcare delivery infrastructure in remote and underserved regions, further boosting the demand for mobile ultrafast CT devices. These systems are being equipped with advanced networking capabilities to integrate seamlessly with hospital information systems and picture archiving and communication systems (PACS). As healthcare delivery models evolve toward decentralized and community-based approaches, the market for mobile and portable ultrafast CT solutions is poised for continued expansion.
Increasing Focus on Cardiovascular and Oncology Applications
The Europe Ultrafast CT Scan Devices Market is witnessing an increasing focus on cardiovascular and oncology applications, driven by the rising burden of heart diseases and cancers across the region. Ultrafast CT systems offer unparalleled imaging speed and high temporal resolution, making them particularly well-suited for cardiac imaging, including coronary artery assessments and calcium scoring. Leading healthcare institutions are incorporating ultrafast CT into their cardiology departments to improve diagnostic accuracy for conditions like coronary artery disease, structural heart abnormalities, and pulmonary embolism. In oncology, ultrafast CT devices facilitate early tumor detection, precise tumor staging, and treatment response monitoring. Multiphase imaging capabilities allow for detailed visualization of vascular structures and tumor perfusion, which are critical for planning surgical interventions and radiotherapy. The trend toward minimally invasive procedures, such as transcatheter interventions, also demands advanced imaging support provided by ultrafast CT systems. Additionally, clinical research initiatives and partnerships between hospitals and device manufacturers are expanding the application scope of ultrafast CT in cancer and heart disease management. As Europe continues to experience a demographic shift toward an older population with complex health needs, the demand for specialized imaging applications in cardiology and oncology is expected to significantly drive market growth.
Market Challenges
High Cost of Acquisition and Maintenance
The high cost associated with the acquisition, installation, and maintenance of ultrafast CT scan devices poses a significant challenge to market growth across Europe. Ultrafast CT systems incorporate advanced technologies such as AI integration, low-dose imaging solutions, and dual-source scanning capabilities, which substantially increase their initial purchase price. For instance, hospitals and diagnostic centers in Western Europe, such as Germany and France, have reported higher adoption rates of advanced imaging technologies due to better healthcare funding, while facilities in Eastern and Southern Europe often face financial constraints. In addition to the high capital expenditure, ongoing costs related to servicing, software updates, hardware upgrades, and specialized training for radiologists and technicians further strain financial resources. Many healthcare systems in Europe operate under strict budgetary controls, as highlighted by trends in healthcare expenditure statistics, which show significant disparities in resource allocation between regions. Consequently, despite the clinical advantages offered by ultrafast CT systems, their adoption is often limited to large urban hospitals and specialized centers, creating disparities in access to advanced diagnostic technologies across different regions. This financial barrier continues to slow market penetration, particularly in Eastern and Southern European countries where healthcare infrastructure development lags behind Western Europe.
Regulatory and Data Privacy Challenges
Navigating complex regulatory frameworks and ensuring compliance with stringent data privacy laws present another critical challenge in the Europe Ultrafast CT Scan Devices Market. Medical imaging devices must adhere to rigorous standards established by bodies such as the European Medicines Agency (EMA) and comply with the Medical Device Regulation (MDR) requirements, which demand extensive clinical validation and post-market surveillance. These regulatory processes increase the time-to-market for new ultrafast CT systems and add to development costs for manufacturers. Moreover, the integration of AI and cloud-based technologies into CT imaging raises significant data security and patient privacy concerns, especially under the General Data Protection Regulation (GDPR). Healthcare providers must invest in secure data management infrastructures, encryption protocols, and cybersecurity measures to protect sensitive patient information. Non-compliance can result in substantial financial penalties and reputational damage. Managing these regulatory and privacy challenges requires continuous investments in quality assurance, legal compliance teams, and IT security, placing additional operational burdens on manufacturers and healthcare institutions alike.
Market Opportunities
Expansion of AI-Driven Diagnostic Capabilities
One of the most significant opportunities in the Europe Ultrafast CT Scan Devices Market lies in the integration and expansion of Artificial Intelligence (AI)-driven diagnostic tools. As healthcare systems increasingly emphasize precision medicine and personalized healthcare, the demand for AI-enhanced ultrafast CT systems is expected to rise substantially. AI technologies enable more accurate image interpretation, automating tasks such as lesion detection, organ segmentation, and disease classification. This leads to quicker diagnoses, improved clinical decision-making, and enhanced workflow efficiency. Manufacturers have the opportunity to further refine AI applications, offering solutions that assist radiologists in not only detecting abnormalities but also predicting disease progression. By developing AI-enhanced systems tailored to specific medical fields such as cardiology, oncology, and neurology, companies can open new market segments. Additionally, the European market is becoming more receptive to AI-powered technologies due to government-driven initiatives aimed at digitalizing healthcare and improving diagnostic accuracy. This creates a clear opportunity for vendors to lead the way in creating next-generation imaging solutions.
Increasing Demand for Point-of-Care and Mobile Imaging Solutions
Another key opportunity in the Europe Ultrafast CT Scan Devices Market is the growing demand for mobile and point-of-care imaging solutions. The rise of decentralized healthcare models, spurred by the COVID-19 pandemic and ongoing healthcare reforms, has created a need for portable and flexible diagnostic tools. Mobile ultrafast CT devices, which can be deployed in emergency rooms, ambulances, and rural or remote healthcare settings, are gaining significant traction. These portable devices allow for faster patient triage, quicker diagnostics, and better access to healthcare in underserved regions. Companies can capitalize on this demand by developing compact, lightweight ultrafast CT systems with advanced connectivity features, enabling integration with cloud-based platforms for remote diagnosis and consultation.
Market Segmentation Analysis
By Type
The Europe Ultrafast CT Scan Devices Market is divided into two primary types: Single-Slice CT and Multi-Slice CT. Single-Slice CT scanners, though less commonly used in advanced applications, are still widely employed in routine imaging due to their affordability and simpler design. However, Multi-Slice CT scanners, which offer multiple slices per rotation, are rapidly gaining preference due to their superior image quality, faster scan times, and ability to capture more detailed anatomical structures. Multi-Slice CT devices are particularly favored for complex diagnostic procedures, including cardiovascular and oncology imaging, where higher resolution is critical. The shift towards Multi-Slice CT devices is driven by advancements in technology that enhance processing speed, reduce radiation exposure, and improve diagnostic outcomes, making them ideal for both emergency and routine diagnostic procedures.
By Application
The key applications of ultrafast CT devices in Europe include cardiology, oncology, neurology, orthopedics, and other specialized areas. In cardiology, ultrafast CT systems are used to assess coronary artery disease, detect heart anomalies, and evaluate vascular conditions with high precision and speed. On the oncology front, these devices are essential for early cancer detection, tumor staging, and monitoring treatment efficacy. The ability of ultrafast CT to generate high-resolution images of soft tissues plays a pivotal role in detecting tumors and assessing their progression. Neurology also benefits from ultrafast CT in the diagnosis of brain disorders, including stroke, epilepsy, and neurodegenerative diseases, due to the system’s ability to capture detailed brain images rapidly. Orthopedic applications are critical as ultrafast CT scans help in diagnosing bone fractures, joint issues, and musculoskeletal conditions with improved accuracy. Additionally, the "Others" category covers various niche applications where ultrafast CT devices are used in trauma care, emergency rooms, and other specialized clinical settings.
Segments
Based on Type
- Single-Slice CT
- Multi-Slice CT
Based on Application
- Cardiology
- Oncology
- Neurology
- Orthopedics
- Others
Based on End User
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers
Based on Region
- Western Europe
- Eastern Europe
- Nordic countries
Regional Analysis
Western Europe (65%)
Western Europe holds the largest market share in the Europe Ultrafast CT Scan Devices Market, accounting for approximately 65% of the total market in 2024. This dominance can be attributed to the region’s well-established healthcare systems, advanced medical infrastructure, and substantial healthcare expenditure. Countries such as Germany, the UK, France, and Italy are key contributors to the growth of the ultrafast CT market, with hospitals and diagnostic centers heavily investing in state-of-the-art imaging technologies. Western Europe also benefits from high levels of healthcare funding, government initiatives, and support for the adoption of innovative technologies in medical diagnostics. The growing focus on early disease detection and precision medicine, particularly in cardiology and oncology, is driving the demand for ultrafast CT systems in the region.
Eastern Europe (20%)
Eastern Europe is witnessing rapid growth in the adoption of ultrafast CT scan devices, contributing around 20% to the overall market share. The market in this region is expanding due to increasing healthcare investments, ongoing medical reforms, and a growing demand for advanced diagnostic technologies. Countries like Russia, Poland, and Hungary are significantly upgrading their healthcare infrastructure to provide better diagnostic solutions to their populations. Although the healthcare sector in Eastern Europe is still developing compared to Western Europe, rising disposable incomes and government-backed initiatives are helping to bridge the gap. The focus on modernizing healthcare facilities and improving access to state-of-the-art medical devices is boosting the demand for ultrafast CT scanners, especially in urban areas.
Key players
- Siemens Healthineers
- Philips Healthcare
- Canon Medical Systems Corporation
- GE HealthCare
- Fujifilm Holdings Corporation
- Hitachi Healthcare
- Shimadzu Corporation
- Carestream Health
- Esaote SpA
- Agfa HealthCare
Competitive Analysis
The Europe Ultrafast CT Scan Devices Market is highly competitive, with several key players continuously innovating to enhance their product offerings. Siemens Healthineers, a market leader, stands out due to its advanced imaging technology and AI-powered diagnostic solutions. Similarly, Philips Healthcare has a strong presence, offering high-quality CT systems with integrated advanced software for enhanced diagnostic accuracy. Canon Medical Systems Corporation and GE HealthCare are also significant competitors, with a focus on low-dose imaging and high-speed scanning technologies. Fujifilm Holdings and Hitachi Healthcare offer cost-effective solutions, targeting mid-range healthcare providers while integrating cutting-edge imaging technologies. Shimadzu Corporation and Carestream Health are known for their robust product portfolios in diagnostic imaging, providing reliable ultrafast CT systems. Esaote SpA and Agfa HealthCare focus on niche markets, including orthopedic imaging and healthcare solutions for smaller clinics. These players are constantly vying for market share through product innovations, strategic partnerships, and expanding their regional footprints.
Recent Developments
- In February 2024, Canon Medical Systems Corporation completed its second global installation of a photon-counting CT system at Radboud University Medical Center in the Netherlands, initiating clinical research led by Prof. Mathias Prokop.
- In December 2024, Samsung Medison showcased an enhanced portfolio at RSNA 2024, including the floor-mounted digital X-ray GF 85 and a pediatric cardiac-specific ultrasound probe.
- In December 2024, United Imaging Healthcare introduced the uMI Panvivo PET/CT system at RSNA 2024, featuring industry-leading NEMA PET spatial resolution and AI-driven 3D camera technology.
- In March 2025, Mindray Medical International introduced the Resona A20 at ECR 2025, featuring Acoustic Intelligence Technology to elevate ultrasound imaging capabilities.
- In March 2025, Shimadzu Corporation celebrated its 150th anniversary and opened a new R&D center in Boston, focusing on customer-oriented development to expand business in the pharmaceutical field
- In February 2025, Esaote SpA presented integrated medical imaging solutions and unveiled innovations in ultrasound technology at ECR 2025, emphasizing AI integration to optimize workflows and improve image quality.
- In March 2025, Agfa HealthCare showcased the next generation of Enterprise Imaging at ECR 2025, focusing on innovations that support a more sustainable future for clinical teams
Market Concentration and Characteristics
The Europe Ultrafast CT Scan Devices Market exhibits moderate to high concentration, dominated by a few large players that lead the technological advancements and product innovations. Companies such as Siemens Healthineers, Philips Healthcare, GE HealthCare, and Canon Medical Systems Corporation hold a significant share of the market, leveraging their established brand presence, strong R&D capabilities, and extensive distribution networks. The market is characterized by continuous innovation, particularly in areas such as AI integration, low-dose imaging, and advanced scan capabilities, which contribute to the competitive advantage of these major players. Despite the dominance of these industry giants, there is still room for smaller players like Fujifilm Holdings and Shimadzu Corporation to capitalize on niche markets, offering cost-effective solutions. The market is also witnessing increasing consolidation through strategic acquisitions and partnerships, as leading companies seek to expand their technological capabilities and regional reach, making the landscape both competitive and dynamic.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The future of the ultrafast CT market will be defined by ongoing innovations in imaging technologies, particularly AI integration and enhanced scan speed. These advancements will improve diagnostic accuracy and efficiency across various medical specialties.
- As AI continues to evolve, its integration into ultrafast CT systems will become deeper, allowing for automated image analysis and faster interpretation. This will enhance clinical decision-making and reduce the workload on radiologists.
- Emerging European markets, particularly in Eastern and Southeastern Europe, will see an increase in the adoption of ultrafast CT devices as healthcare infrastructure improves. This expansion will be fueled by government initiatives and international funding.
- Reducing radiation exposure while maintaining image clarity will remain a key focus. Technological breakthroughs in low-dose imaging techniques will make ultrafast CT systems even safer for patients, particularly in pediatrics and oncology.
- The demand for portable and mobile ultrafast CT solutions will grow, especially in emergency rooms and rural areas. These solutions will allow for rapid diagnostics in critical care and trauma situations.
- Ultrafast CT systems will see continued growth in cardiology and oncology, particularly for early disease detection, tumor staging, and heart disease management. The demand for high-speed, high-resolution imaging will drive adoption.
- Cloud connectivity will become increasingly important, enabling seamless data sharing and remote diagnostics. This will facilitate telemedicine and support the growing need for collaborative healthcare approaches.
- European regulatory bodies will continue to support the adoption of advanced diagnostic technologies, encouraging investment in ultrafast CT systems through reimbursement policies and healthcare modernization initiatives.
- The shift toward value-based healthcare models will increase the demand for diagnostic technologies that optimize cost-efficiency and improve patient outcomes. Ultrafast CT devices align with these priorities, offering faster, more accurate diagnostics.
- We can expect more collaborations between key players in the industry and healthcare providers. Partnerships focused on research and development, as well as expanding regional reach, will further fuel market growth and product innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Europe Ultrafast CT Scan Devices Market in 2023 and 2032, and what is its CAGR?
What are the key drivers of the Europe Ultrafast CT Scan Devices Market?
How does technological advancement influence the Europe Ultrafast CT Scan Devices Market?
Who are the major players in the Europe Ultrafast CT Scan Devices Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Ultrafast CT Scan Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Ultrafast CT Scan Devices Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 2,571.26 million → 2032: USD 3,947.20 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Ultrafast CT Scan Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Ultrafast CT Scan Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Ultrafast CT Scan Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Ultrafast CT Scan Devices Market Drivers
- 3.3 Europe Ultrafast CT Scan Devices Market Restraints & Challenges
- 3.4 Europe Ultrafast CT Scan Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Ultrafast CT Scan Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Ultrafast CT Scan Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Ultrafast CT Scan Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Ultrafast CT Scan Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Ultrafast CT Scan Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Ultrafast CT Scan Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Ultrafast CT Scan Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Ultrafast CT Scan Devices Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Ultrafast CT Scan Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Ultrafast CT Scan Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Ultrafast CT Scan Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Ultrafast CT Scan Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Ultrafast CT Scan Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Ultrafast CT Scan Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Ultrafast CT Scan Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Ultrafast CT Scan Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Ultrafast CT Scan Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Ultrafast CT Scan Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Ultrafast CT Scan Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
