
Market Overview
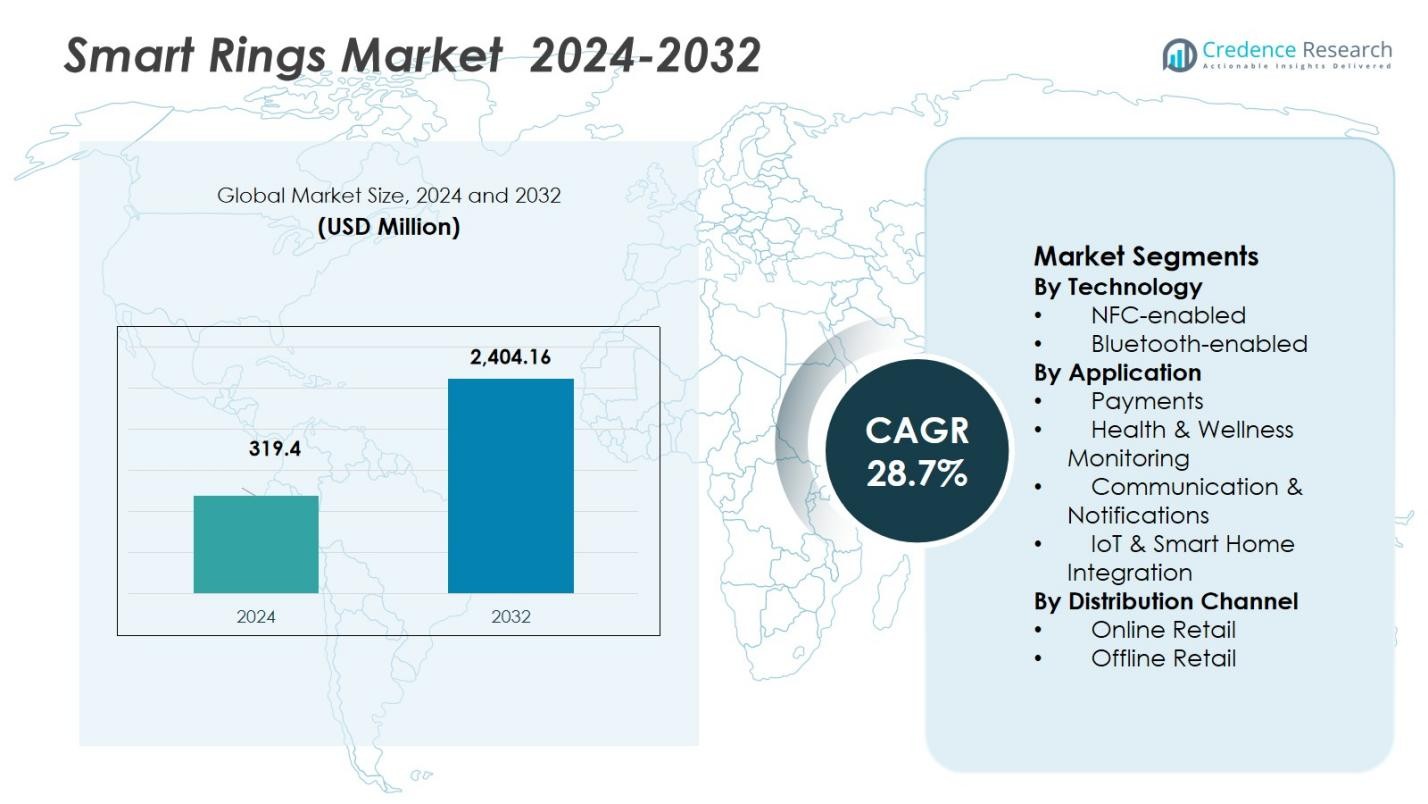
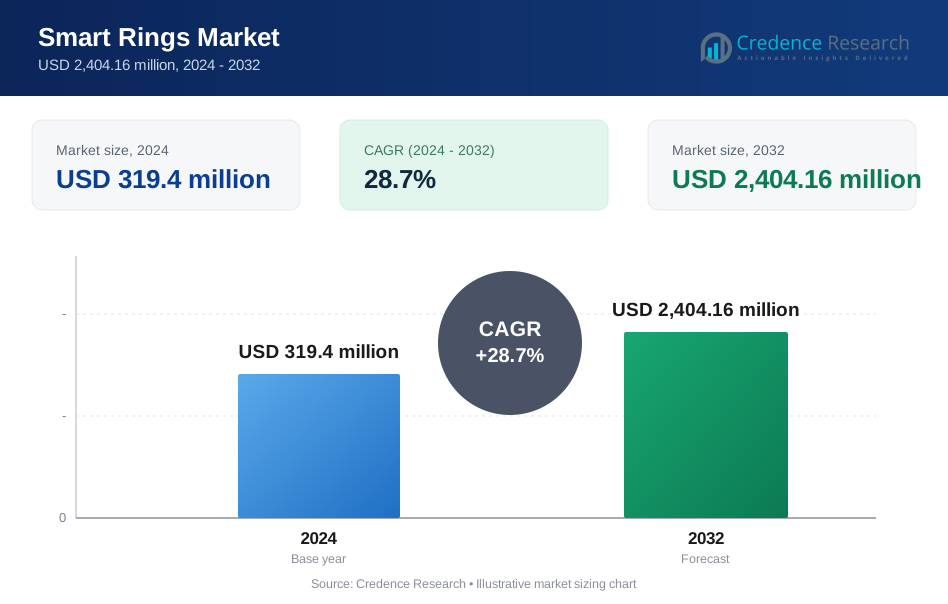
The Smart Rings Market size was valued at USD 319.4 million in 2024 and is anticipated to reach USD 2,404.16 million by 2032, at a CAGR of 28.7% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Rings Market Size 2024 | USD 319.4 Million |
| Smart Rings Market, CAGR | 28.7% |
| Smart Rings Market Size 2032 | USD 2,404.16 Million |
Smart Rings Market exhibits strong presence of leading players such as Oura Health Ltd., Motiv Inc., McLear Ltd., NFC Ring, Ringly Inc., Jakcom Technology Co., Ltd., Kerv Wearables, Tokenize Inc., Prevention Circul+ and Sleepon. These companies drive the market through diverse offerings from advanced health‑tracking rings to NFC‑enabled payment and security devices aiming at different consumer segments and use cases. The market’s leading region is North America, which held a 44.18% share in 2024. High consumer awareness of wearable technology, strong disposable incomes, and robust digital infrastructure in this region continue to support adoption of smart rings.
Market Insights
- The Smart Rings Market size was valued at USD 319.4 million in 2024 and is anticipated to reach USD 2,404.16 million by 2032, growing at a CAGR of 28.7% during the forecast period (2024-2032).
- Rising consumer demand for wearable technology, especially health and fitness monitoring devices, is a major driver for market growth.
- Key trends include the growing integration of smart rings with IoT and smart home devices, offering more functionality such as home automation and secure access control.
- The market faces challenges such as data privacy concerns and battery life limitations, which could hinder growth if not addressed by manufacturers.
- North America leads the market with a 44.18% share in 2024, followed by Europe and Asia Pacific, with Health & Wellness Monitoring being the dominant application, representing 37.2% of the market share in 2024.
 Market Segmentation Analysis:
By Technology:
The Smart Rings market is primarily segmented by technology into NFC-enabled and Bluetooth-enabled rings. Bluetooth-enabled smart rings dominate this segment, holding a substantial market share of 68.5% in 2024. The growth of Bluetooth technology is driven by its widespread adoption in consumer electronics, offering reliable connectivity, low power consumption, and ease of use. Bluetooth-enabled rings are increasingly used for communication, notifications, and health tracking, which has contributed to their strong market position. NFC-enabled rings, though emerging, account for the remaining 31.5% share, primarily driven by secure payment applications.
- For instance, Oura’s third-generation smart ring leverages Bluetooth Low Energy (BLE) for continuous sleep and heart rate monitoring while maintaining a battery life of up to seven days.
By Application:
The Smart Rings market's applications are divided into Payments, Health & Wellness Monitoring, Communication & Notifications, and IoT & Smart Home Integration. Among these, Health & Wellness Monitoring holds the largest share, representing 37.2% in 2024. The growing consumer focus on personal health and fitness has driven demand for wearable health tech, such as smart rings capable of tracking vital signs and sleep patterns. Payments follow closely, contributing 29.4% to the market, spurred by the increasing adoption of contactless payment solutions. Communication & Notifications, along with IoT & Smart Home Integration, also contribute significantly to the market.
- For instance, Oura Ring Gen 3 monitors heart rate, SpO₂, temperature, and sleep cycles, and has been adopted by organizations like the NBA for player health tracking.
By Distribution Channel:
The Smart Rings market is distributed through Online Retail and Offline Retail channels. Online Retail leads the distribution landscape, capturing 58.7% of the market share in 2024. The ease of access to a wide range of smart rings through e-commerce platforms and growing consumer preference for online shopping fuel this dominance. Offline Retail holds a 41.3% share, benefiting from consumers' desire to physically examine and test the products before purchase. Both channels are expected to grow steadily, with online sales continuing to outpace offline sales due to the convenience and broader product selection available online.
Key Growth Drivers
Rising Consumer Demand for Wearable Technology
The increasing adoption of wearable technology is a significant growth driver for the Smart Rings market. As consumers seek more discreet and stylish alternatives to traditional wearables like smartwatches, smart rings offer a compact and convenient solution. With advancements in technology, smart rings are becoming capable of tracking fitness, health metrics, and facilitating communication, all while maintaining a sleek design. This growing interest in wearable health and wellness products contributes significantly to the market’s expansion, appealing particularly to tech-savvy and health-conscious consumers.
- For instance, Circular Ring Pro 2, FDA-cleared for atrial fibrillation detection, provides detailed ECG monitoring and AI-powered sleep analysis, with digital sizing ensuring a perfect fit.
Expansion of Contactless Payments
The adoption of contactless payments is a major factor propelling the growth of the Smart Rings market. As consumers and businesses increasingly shift toward cashless transactions, NFC-enabled smart rings are gaining popularity for secure and convenient payments. These rings provide a seamless experience by allowing users to make purchases with just a tap, eliminating the need for physical cards or smartphones. The growing acceptance of digital payments, along with enhanced security features, is expected to drive the demand for smart rings, particularly in retail and financial sectors.
- For instance, India's 7 Ring is an NFC-enabled smart ring certified by RuPay, offering fast, secure payment by simply placing a closed fist with the ring near a POS terminal, with payment approval in less than 4 seconds.
Technological Advancements in Smart Rings
Technological innovations in smart ring functionality are fueling market growth by enhancing the overall user experience. Advancements in Bluetooth and NFC technologies enable smart rings to offer reliable connectivity, lower power consumption, and greater compatibility with various devices. Additionally, improved sensor capabilities in smart rings allow for better health monitoring, including heart rate tracking, sleep analysis, and even stress management. These innovations make smart rings more attractive to a broader range of consumers, from fitness enthusiasts to tech-savvy individuals seeking cutting-edge wearables.
Key Trends & Opportunities
Integration with IoT and Smart Home Devices
Smart rings are increasingly being integrated into the broader Internet of Things (IoT) ecosystem, creating new opportunities for growth. As smart homes become more prevalent, the ability to control devices like lights, thermostats, and security systems directly from a smart ring presents a significant trend. Consumers are looking for more intuitive and seamless ways to interact with their smart home devices, and smart rings offer a convenient and discreet solution. This integration is likely to expand the functionality of smart rings, making them a key component in the IoT market.
- For instance, McLear a pioneer in NFC smart ring technology, allows users to make contactless payments and control smart home devices with just a tap, expanding smart ring functionality beyond fitness tracking.
Focus on Personalized Health Monitoring
As health-conscious consumers demand more personalized and accurate health tracking, smart rings present a significant opportunity. The growing trend of health and wellness wearables is fueling demand for rings that can monitor a wide range of metrics, including sleep patterns, stress levels, and even blood oxygen saturation. Smart rings equipped with advanced sensors are becoming increasingly capable of offering real-time health insights, which can be personalized to meet individual needs. This trend aligns with the growing interest in preventive healthcare and fitness, creating opportunities for brands to develop tailored solutions.
- For instance, Samsung's Galaxy Ring launched in 2024 integrates AI-powered features to monitor sleep patterns, heart rate, and fitness activities, all within a sleek titanium frame offering up to seven days of battery life.
Key Challenges
Privacy and Data Security Concerns
One of the major challenges facing the Smart Rings market is the growing concern around privacy and data security. As smart rings collect sensitive data, such as health metrics and payment information, there is an increased risk of cyberattacks and unauthorized access to personal data. Consumers are becoming more cautious about sharing their private information with wearable devices, and manufacturers must prioritize robust encryption and data protection measures to ensure user trust. Addressing these concerns is essential to the market’s continued growth, particularly as the integration of smart rings with other IoT devices increases.
Battery Life Limitations
Despite significant advancements in smart ring technology, battery life remains a challenge. The compact size of smart rings restricts the capacity for large batteries, limiting how long the device can function on a single charge. As consumers increasingly demand more powerful and feature-rich devices, manufacturers are struggling to balance performance with battery longevity. Improving the battery life of smart rings without compromising size, functionality, and comfort will be critical for their continued success in the market. This challenge requires ongoing innovation in power-efficient technologies and energy management solutions.
Regional Analysis
North America
North America commands a strong position in the smart rings market, holding a 37.69% share in 2024. This dominance stems from a tech-savvy population, high disposable income, and mature adoption of wearable devices. Consumers in the region increasingly embrace smart rings for health monitoring, contactless payments, and daily convenience. Robust infrastructure supporting IoT ecosystems and the presence of leading smart-ring manufacturers further reinforce North America’s leading role in the market.
Asia Pacific
Asia Pacific leads as the largest regional market with a 27.03% share in 2024. Rapid urbanization, rising disposable incomes, and growing smartphone penetration in countries such as China and India drive the uptake of smart rings. Increasing awareness about health and wellness, combined with a large youthful population open to wearable technology, fuels demand. Government initiatives promoting digitalization and improving connectivity also support regional growth, contributing to the overall market share.
Europe
Europe exhibits a significant presence in the smart rings market, with a 22.5% market share in 2024. The region benefits from tech-aware consumers and rising interest in health tracking and contactless payment solutions. Regulatory support for data privacy and consumer protection, along with robust retail and e-commerce frameworks, further encourage adoption. Continued investment in wearable-friendly ecosystems sustains Europe’s market relevance, positioning it as a strong contender in the global market.
Latin America
Latin America represents a growing, albeit smaller, share of the global smart rings market, holding 7.1% of the market in 2024. Market growth in this region is driven by increasing smartphone penetration, rising consumer awareness of wearable health and payment convenience, and gradual improvements in digital infrastructure. As contactless payments gain traction and affordability improves, smart rings gradually gain acceptance among tech-savvy and urban consumers, further expanding the regional market share.
Middle East & Africa
The Middle East & Africa region captures a modest but rising portion of global smart rings demand, holding a 5.7% share in 2024. Growing adoption of contactless payments, urbanization, and increasing interest in health and wellness wearables underpin growth. Expansion of e-commerce platforms and improving internet connectivity also support market penetration. As disposable income rises among certain urban segments, smart rings emerge as attractive lifestyle and utility devices, contributing to the region’s increasing market share.
Market Segmentations:
By Technology
- NFC-enabled
- Bluetooth-enabled
By Application
- Payments
- Health & Wellness Monitoring
- Communication & Notifications
- IoT & Smart Home Integration
By Distribution Channel
- Online Retail
- Offline Retail
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Smart Rings Market centers on key players Oura Health Ltd., Motiv Inc., McLear Ltd. and NFC Ring. These firms lead the market by offering differentiated products that focus variously on health‑tracking, contactless payments, and seamless connectivity. Oura Health maintains leadership through its advanced health‑monitoring smart rings, widely recognized for sleep, heart rate, and physiological tracking. McLear Ltd. and NFC Ring dominate the payment and security segment, leveraging NFC technology for contactless payments and smart‑device access. Motiv Inc. contributes by targeting users who prefer minimalist design with core fitness‑tracking features. Together, their strong product portfolios and brand equity shape market expectations and push innovation. Other firms compete by addressing niche applications such as specialized security, IoT integration, or cost‑effective alternatives but the dominance of these leading players defines competitive dynamics.
Key Player Analysis
- Motiv Inc.
- NFC Ring
- Sleepon
- Jakcom Technology Co., Ltd.
- McLear Ltd.
- Tokenize Inc.
- Ringly Inc.
- Prevention Circul+
- Oura Health Ltd.
- Kerv Wearables
Recent Developments
- In November 2025, Oura launched a new premium version of its smart ring the Oura Ring 4 Ceramic and introduced a USB‑C charging case able to recharge the ring up to five times, enhancing user convenience and product appeal.
- In July 2024, Samsung unveiled the Samsung Galaxy Ring, its first smart ring with biometric health‑monitoring features, marking a major entry of a leading smartphone OEM into the smart‑ring category.
- In May 2025, Oura rolled out an algorithm update for the Oura Ring that improves step‑count accuracy and refines activity and calorie‑burn metrics via machine learning improving reliability of fitness tracking.
- In October 2025, Reebok released its first smart ring at USD 249, offering heart‑rate, blood oxygen, sleep and stress tracking marking its debut in wearable wellness.
Report Coverage
The research report offers an in-depth analysis based on Technology, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The smart rings market is poised to benefit from ongoing miniaturization of sensors and electronics, enabling ever‑smaller, more comfortable devices that can deliver accurate health, activity, and biometric tracking without compromising aesthetics.
- Rising integration with broader IoT and smart‑home ecosystems will allow smart rings to act as universal controllers for home automation, access control, and secure authentication expanding their utility beyond health tracking and payments.
- Increasing consumer emphasis on preventive health and wellness will drive rising demand for smart rings that offer continuous monitoring of vitals, sleep, stress, and recovery especially among fitness‑conscious and health‑aware populations.
- Smart rings will increasingly become preferred wearables for consumers seeking discretion and minimalism offering similar or complementary functionality to smartwatches but with more subtle design and 24/7 wear comfort.
- As contactless payment infrastructure and digital wallet adoption expand globally, NFC‑enabled smart rings will gain traction as convenient, secure alternatives to cards and smartphones for transactions and identity verification.
- Market expansion into emerging economies and high‑growth regions such as Asia‑Pacific and parts of Middle East & Africa will broaden the user base, driven by increasing smartphone penetration and rising disposable incomes.
- Manufacturers will increasingly adopt subscription‑based services and added‑value health analytics (e.g. sleep optimization, stress management, recovery recommendations) to drive recurring revenue and deepen user engagement.
- Design diversification including different materials (metal, ceramic, etc.), styles (fashion‑forward, unisex, gender‑specific) and functionalities will help smart rings appeal to broader demographics, from fashion‑oriented users to health‑conscious professionals.
- Advances in sensor and battery technologies including lower‑power processing, efficient charging, and possibly passive or hybrid power solutions will address existing pain points like battery life and device durability, boosting adoption.
- Competition and innovation from technology incumbents and new entrants will accelerate feature development, push down prices, and enhance global availability making smart rings more accessible to mainstream consumers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Consumer Shift Toward Wearable Health & Wellness Devices
Growing consumer interest in personal health and fitness is driving demand for smart rings that offer discreet, continuous monitoring of vital signs, sleep, and activity, appealing to health-conscious and tech-savvy users.
Expansion of Contactless Payment Solutions
The increasing adoption of digital and contactless payments is fueling demand for NFC-enabled smart rings, which offer secure, convenient payment options without the need for physical cards or smartphones.
Technological Advancements in Miniaturization and Sensors
Ongoing improvements in sensor technology, battery efficiency, and miniaturization are enabling smart rings to deliver more accurate health tracking and expanded features in a compact, comfortable form factor.
Integration with IoT and Smart Home Ecosystems
Smart rings are increasingly being used as controllers for smart home devices and IoT systems, providing users with seamless, intuitive ways to manage home automation, security, and access control directly from their finger.
Rising Online Retail Penetration
The dominance of online retail channels makes smart rings more accessible to a global audience, allowing consumers to easily compare features, access a wider product range, and benefit from direct-to-consumer sales models.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Smart Rings Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smart Rings Market projected to grow between 2025 and 2032?
Which Smart Rings Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smart Rings Market?
Who are the leading companies in the Smart Rings Market?
Which region commanded the largest share of the Smart Rings Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 NFC-enabled
- 1.2.2 Bluetooth-enabled
- 1.3 By Application
- 1.3.1 Payments
- 1.3.2 Health & Wellness Monitoring
- 1.3.3 Communication & Notifications
- 1.3.4 IoT & Smart Home Integration
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 319.4 million → 2032: USD 2,404.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Rings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Rings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Rings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Rings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Rings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Rings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Rings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Rings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 319.4 million → 2032: USD 2,404.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Rings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 NFC-enabled
- 12.3.7.2 Bluetooth-enabled
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Payments
- 12.4.7.2 Health & Wellness Monitoring
- 12.4.7.3 Communication & Notifications
- 12.4.7.4 IoT & Smart Home Integration
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Rings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Rings Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Rings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Rings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Oura Health Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Motiv Inc.
- 18.4 McLear Ltd.
- 18.5 NFC Ring
- 18.6 Ringly Inc.
- 18.7 Jakcom Technology Co., Ltd.
- 18.8 Kerv Wearables
- 18.9 Tokenize Inc.
- 18.10 Prevention Circul+
- 18.11 Sleepon
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

